Short-Run Production (Cambridge International A-Level Economics)
Short-run production function
-
The production function shows the relationship between inputs used in production and the level of output produced
- In the short run, at least one factor of production is fixed, meaning it cannot be changed quickly
- Firms increase output mainly by adjusting variable factors
-
When additional variable factors are added to fixed factors, output changes according to the production function
Fixed factors of production
-
Inputs that cannot be changed in the short run
-
Their quantity remains constant as output changes
-
Examples include:
- Machinery
- Buildings
- Land
- Large equipment
Variable factors of production
-
Inputs that can be changed in the short run
-
Firms adjust these to increase or decrease production
-
Examples include:
- Labour
- Raw materials
- Energy inputs
Types of product
1. Total product (TP)
-
Total product (TP) is the total quantity of output produced using a given amount of labour and other inputs
-
For example:
- A bakery produces 100 loaves of bread with one baker
- With two bakers, output increases to 180 loaves
-
As more workers are added, total output increases, although the rate of increase may change
2. Marginal product (MP)
- Marginal product (MP) is the additional output produced by employing one more unit of labour
- Formula:
-
Where:
- ΔTP = change in total product
- ΔQL = change in quantity of labour
-
For example:
- Output increases from 100 loaves to 180 loaves when a second worker is hired
- The marginal product of the second worker is 80 loaves
-
Marginal product shows how much extra output each additional worker produces
3. Average product (AP)
- Average product (AP) measures the output produced per worker
- Formula:
-
Where:
- TP = total product
- QL = quantity of labour
-
For example:
- If three bakers produce 240 loaves, then
- So the average product is 80 loaves per worker
The law of diminishing returns
-
The law of diminishing returns (also called the law of variable proportions) states that:
- When increasing amounts of a variable factor are added to a fixed factor, the marginal product of the variable factor will eventually fall
-
This occurs because the fixed factor becomes a constraint on production.
-
For instance, in a small coffee shop:
- The first barista works efficiently alone
- A second barista improves output, but not as dramatically
- By the time a sixth barista is hired, they may be crowding each other, leading to minimal gains in output
- Eventually, adding more workers does not increase total output significantly and may even reduce efficiency
-
Short-run production in a coffee shop
| Workers | Total Product | Marginal Product | Average Product |
|---|---|---|---|
| 1 | 100 | 100 | 100 |
| 2 | 180 | 80 | 90 |
| 3 | 240 | 60 | 80 |
| 4 | 280 | 40 | 70 |
| 5 | 300 | 20 | 60 |
- This table shows how output increases with each additional worker, but at a decreasing rate
- Eventually, output plateaus, illustrating diminishing returns
Stages of production
- The law of diminishing returns leads to three stages of production
- Firms usually operate in Stage 2, where production is still increasing but diminishing returns have begun
Stage 1: Increasing returns
- Marginal product increases
- Workers specialise and production becomes more efficient
Stage 2: Diminishing returns
- The marginal product begins to fall
- Additional workers still increase output but at a decreasing rate
Stage 3: Negative returns
- The marginal product becomes negative
- Too many workers cause crowding and inefficiency
- Total output may begin to fall
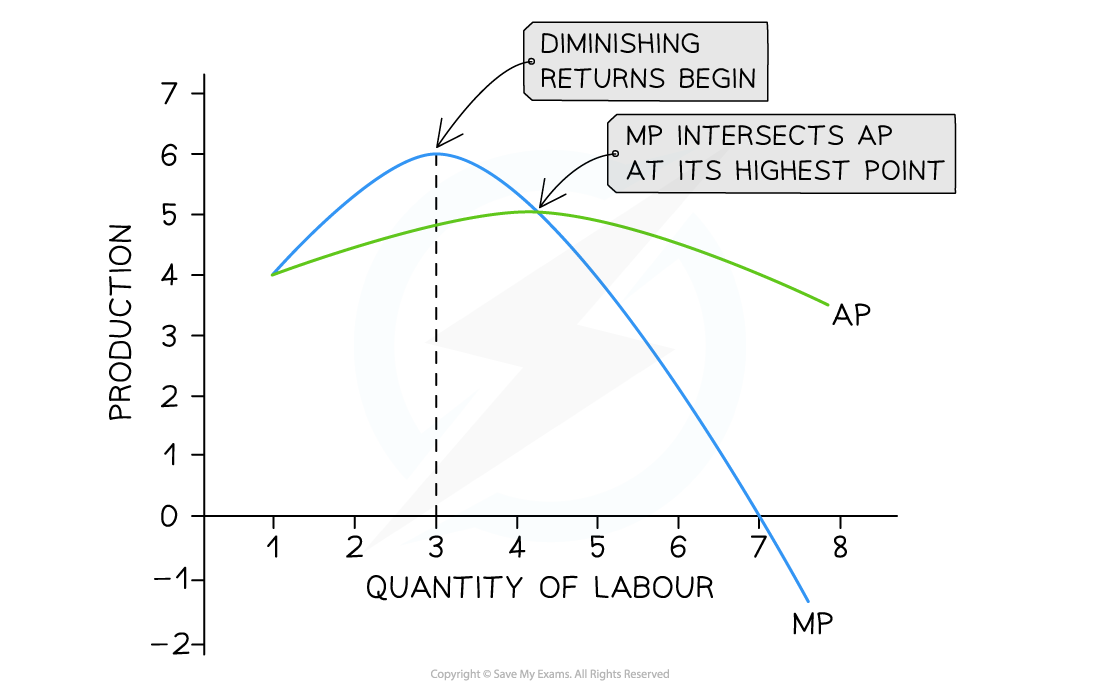
Diagram analysis
- A small food van selling burgers at a music festival increases productivity up to the third worker as workers specialise and the grill is used more efficiently
- After this point, workers begin to get in each other's way and there is limited grill space (capital), so the marginal product of labour begins to fall
- Hiring additional workers still increases total product, but at a diminishing rate
- When the 7th worker is hired, the marginal product becomes negative, causing total product to fall
Understanding the short-run production function helps firms
- Decide how many workers to hire
- Estimate the cost of increasing output
- Identify the point at which adding more labour becomes inefficient
- It also supports broader economic analysis of resource allocation, productivity, and cost structures in different industries
Was this revision note helpful?