Short-Run Costs (Cambridge International A-Level Economics)
Types of short-run costs
-
In the short run, some factors of production such as factory space or machinery are fixed, while others, such as labour or raw materials can be varied
-
This creates two types of costs:
- Fixed costs, which do not change with output
- Variable costs, which change as production increases
-
These together form the short-run cost structure of a firm
Fixed and variable costs
1. Fixed costs (FC)
-
Fixed costs are expenses that do not change with the level of output. They must be paid even if the firm produces nothing
- Examples include rent for premises, insurance premiums, and salaries of permanent staff
- A cinema pays rent and licensing fees whether it screens films or not
- On a graph, total fixed costs appear as a horizontal line, since they remain constant regardless of output
-
Firms operating in industries with high fixed costs such as hotels or airlines often aim to maximise output
-
This helps to spread these costs over more units, thereby reducing the average fixed cost per unit
2. Variable costs (VC)
-
Variable costs change directly with the level of production
- These include expenses such as wages for temporary staff, electricity used in production, and the cost of raw materials
- For example, a bakery’s flour and sugar costs rise as more cakes are baked.
- Variable costs increase with output and are crucial for calculating total cost
3. Total cost (TC)
- Total cost represents the overall cost of producing a given level of output
- It is the sum of fixed and variable costs
-
Where:
- TFC = total fixed costs
- TVC = total variable costs
-
As output increases, total cost rises because variable costs increase
Average costs
- Average costs measure the cost per unit of output
1. Average total cost (ATC)
- Average total cost shows the total cost of producing each unit of output
-
Where:
- TC = total cost
- Q = quantity of output
2. Average fixed cost (AFC)
- Average fixed cost measures the fixed cost per unit of output
-
As output increases, average fixed cost falls because the fixed costs are spread across more units
- This is sometimes called 'spreading overheads' or 'fixed cost spreading'
3. Average variable cost (AVC)
- Average variable cost measures the variable cost per unit of output
- AVC may initially fall due to better use of variable inputs, but eventually rises due to the law of diminishing returns
Marginal cost (MC)
- Marginal cost is the increase in total cost caused by producing one more unit of output
- Because fixed costs do not change with output in the short run, marginal cost can also be calculated using:
-
Marginal cost typically:
- Falls at first, due to increasing productivity
- Then rises as diminishing returns occur
-
This creates the U-shaped marginal cost curve
-
The MC curve intersects the ATC and AVC curves at their minimum points
Worked Example Cost calculations using the above formulas
Assume:
- Total fixed cost (TFC) = $200
- Variable costs rise at an increasing rate as output increases
- This reflects the law of diminishing returns, where additional workers become less productive and production becomes more expensive
This means:
- Total variable cost (TVC) increases at an increasing rate
- Marginal cost (MC) eventually rises
Short-run cost calculations example
Output (Q) TFC TVC TC = MC = AFC = AVC = ATC = 0 200 0 200 – – – – 1 200 50 250 50 200 50 250 2 200 90 290 40 100 45 145 3 200 140 340 50 66.67 46.67 113.33 4 200 200 400 60 50 50 100 5 200 280 480 80 40 56 96 6 200 380 580 100 33.33 63.33 96.67 7 200 520 720 140 28.57 74.29 102.86 8 200 700 900 180 25 87.5 112.5 What this table demonstrates
- TFC remains constant at $200 because fixed costs do not change with output
- TVC increases at an increasing rate due to the law of diminishing returns
- MC initially falls, then rises as diminishing returns begin
- AFC always falls as fixed costs are spread over more output
- ATC falls initially, then rises as increasing marginal costs dominate
Drawing and interpreting cost diagrams
Fixed costs (FC)
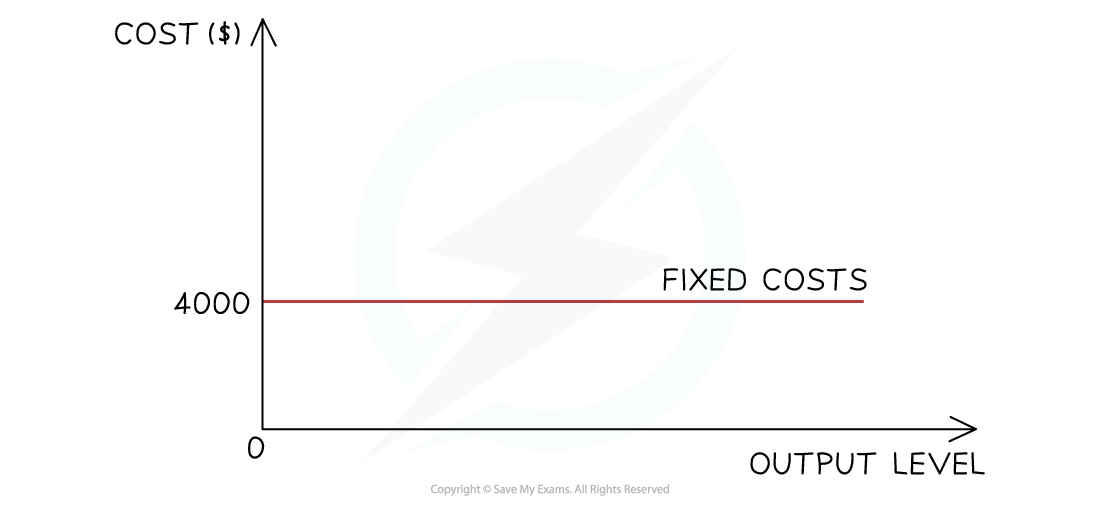
- The firm must pay its fixed costs even if output is zero
- Fixed costs do not change with the level of output
Variable costs (VC)
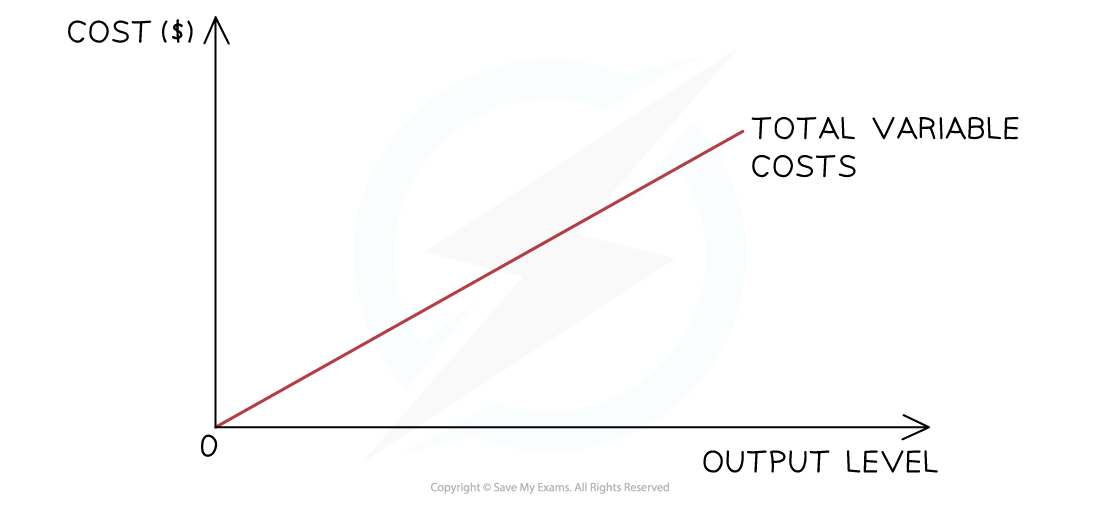
- Initially, variable costs may increase slowly as labour becomes more productive
- As more variable factors are added to fixed factors, the law of diminishing returns causes variable costs to rise at an increasing rate
Total cost (TC)
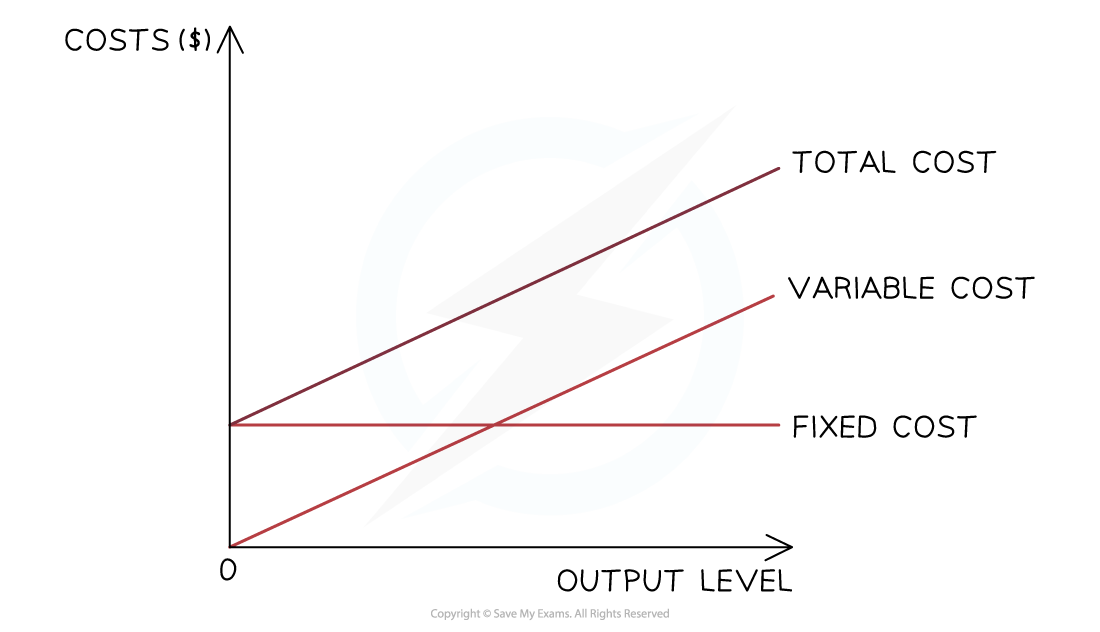
- The total cost is the sum of the variable and fixed costs
- The total costs cannot be 0, as all firms have some level of fixed costs
Average fixed cost (AFC)
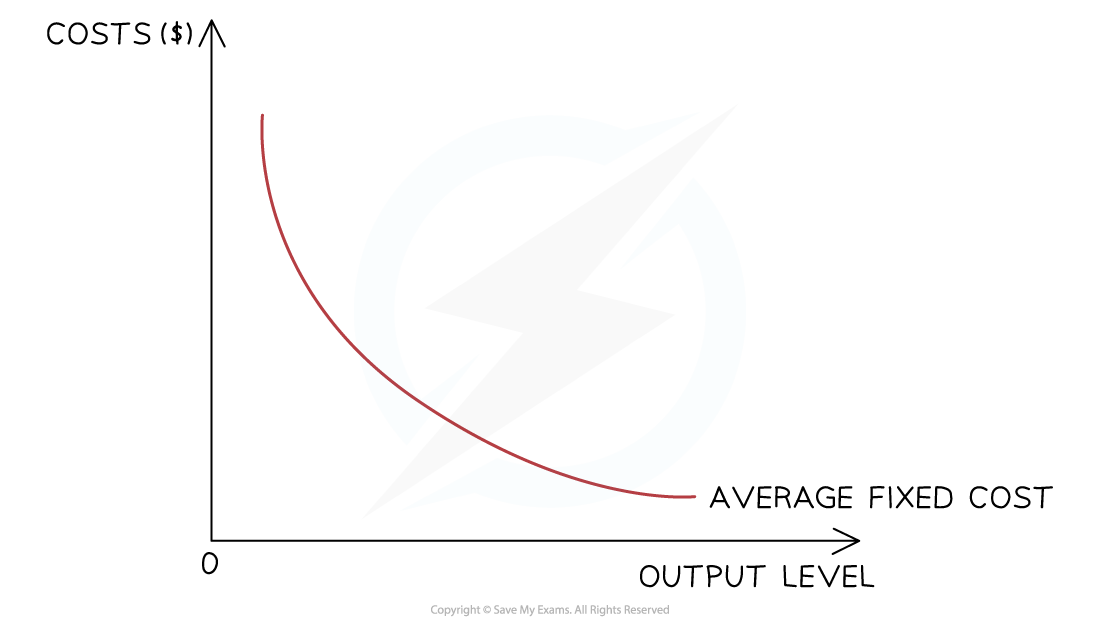
- If the fixed costs of a firm are $1,000 and it produces 1 unit of output, then its **AFC is $1,000 **($1,000/1)
- If the firm increases its output to 1000 units, then the** AFC is $1 per unit **($1000/1,000)
- The more units a firm produces, the lower its AFC will be
- This is one reasons why large levels of output help to increase the profit per unit
Average total cost (ATC)
-
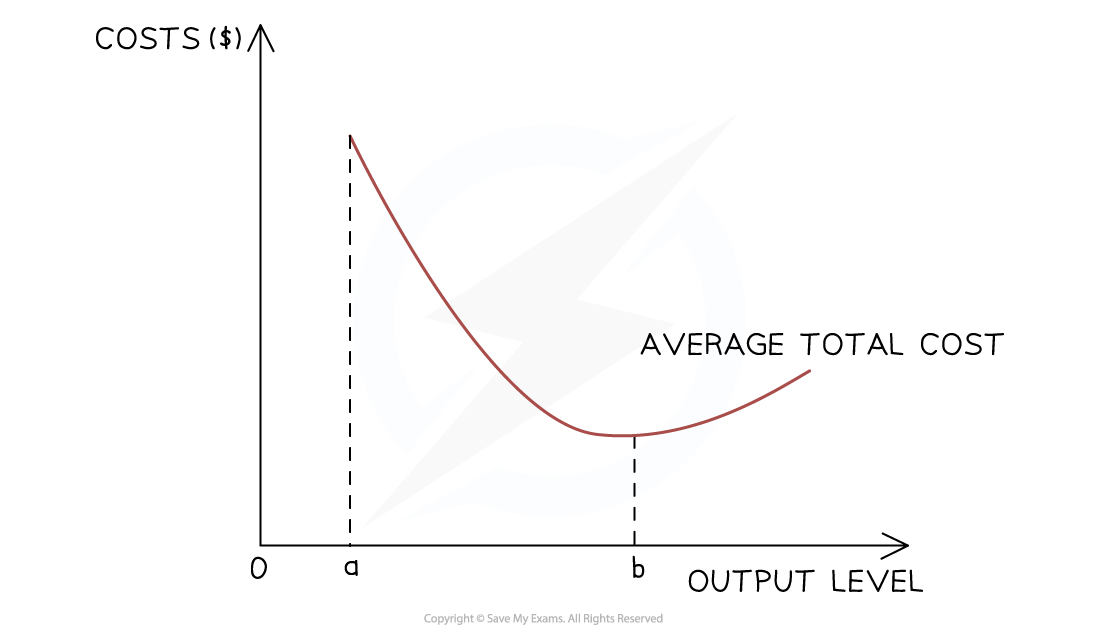
As a firm grows, it is able to increases its scale of output generating efficiencies that lower its average total costs (AC) of production
-
As a firm continues increasing its scale of output, it will reach a point where its average total costs (AC) start to increase
-
ATC is U-shaped mainly because of:
- increasing returns initially
- diminishing returns later
Marginal costs (MC)
-
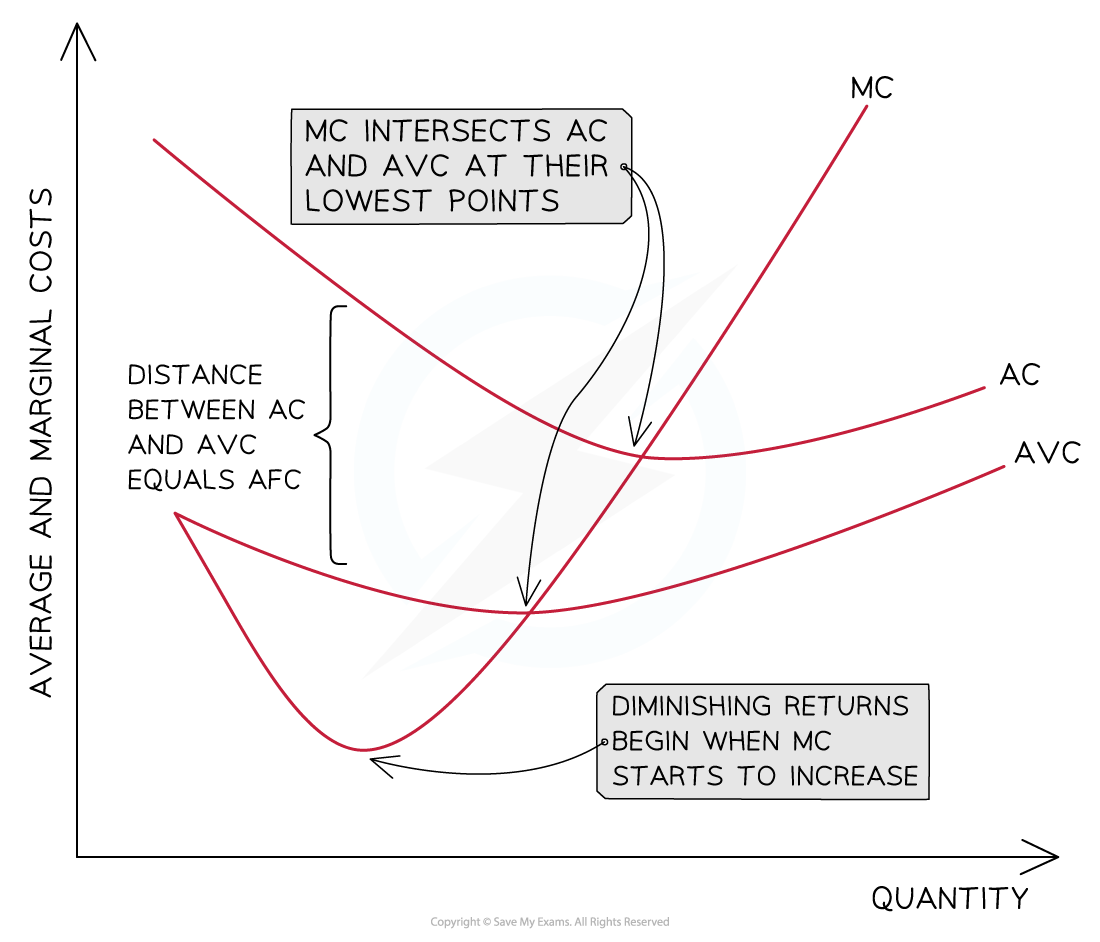
The distance between the AVC and AC = the AFC
- AVC converges towards AC as the AFC continuously decreases with an increase in output
- AVC decreases as additional workers are added and each worker produces additional product
-
Marginal costs (MC) decrease initially as additional workers are added and the marginal product is increasing
-
Diminishing returns begin when the MC starts to increase
-
MC will cross the AVC and AC curves at their lowest point
- As long as the cost of producing the next unit (MC) is lower than the average, it will pull down the average
- When the cost of producing the next unit (MC) is higher than the average, it will pull up the average
Was this revision note helpful?
Build on this topic