The Accounting Equation (Cambridge International AS Accounting)
Assets, liabilities & capital
What are assets?
-
Assets are things owned by the business
- Premises, inventory, motor vehicles, money in the bank, etc
-
Assets also include amounts that are owed to the business by other people or businesses
-
Money owed to the business by credit customers
- These are called trade receivables
-
-
Current assets are short-term assets that the business intends to liquidate within a year
- Trade receivables, inventory, money in the bank, etc
-
Non-current assets are long-term assets that the business intends to own for more than a year and they are not easily liquated
- Premises, motor vehicles, etc
What are liabilities?
-
Liabilities are the amounts that the business owes to other people or businesses
-
Bank loans, bank overdraft, etc
-
Money owed to credit suppliers by the business
- These are called trade payables
-
-
Current liabilities are short-term liabilities which the business intends to pay within a year
- Trade payables, bank overdraft, etc
-
Non-current liabilities are long-term liabilities which the business intends to take longer than a year to repay
- Bank loans, etc
What is capital or owner’s equity?
-
Capital is any resource provided by the owner to start up the business or keep it going
- This is sometimes referred to as owner’s equity
-
Capital is often in the form of money
-
However, it may also consist of other assets
- Such as buildings, furniture, equipment, motor vehicles, goods, etc
-
-
The owner invests capital into their business
- Technically the business owes these assets to the owner
-
If a business makes a profit then its capital increases
-
If a business makes a loss then its capital decreases
What are drawings?
-
Drawings refer to when an owner takes assets from the business for personal use
- This could be money, goods, motor vehicles, etc
-
If the owner takes drawings from the business then the capital decreases
The accounting equation
Spec point — the accounting equation
What is the formula for the accounting equation?
-
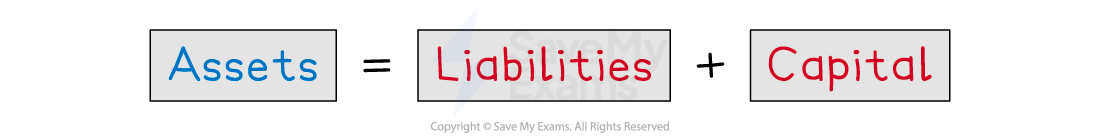
The formula for the accounting equation is: Assets = Liabilities + Capital
-
The equation states that the assets of a business are always equal to the liabilities and capital of the business
-
You can rearrange the equation so that you can find one of the three values if the other two are known
- Liabilities = Assets - Capital
- Capital = Assets - Liabilities
The accounting equation
Exam Hint You may be given examples of assets and liabilities and asked to calculate the missing figure for capital.
Worked Example The assets and liabilities are listed below for a business.
$ Premises 8 500 Equipment 7 000 Inventory 1 000 Trade receivables 5 000 Trade payables 4 500 Bank overdraft 1 200 Calculate the capital of the business.
Answer:
STEP 1 Calculate the total assets:
$ Premises 8 500 Equipment 7 000 Inventory 1 000 Trade receivables 5 000 Total assets 21 500 STEP 2 Calculate the total liabilities:
$ Trade payables 4 500 Bank overdraft 1 200 Total liabilities 5 700 STEP 3 Apply the formula Capital = Assets - Liabilities
$21 500 - $5 700 = $15 800
Why is the accounting equation important?
-
The accounting equation may be shown in the form of a statement of financial position
-
The statement of financial position will be affected every time the business makes changes to the assets, liabilities and capital
-
Every single transaction will result in at least two changes which balance out
- Both sides of the equation could increase by the same amount
- Both sides of the equation could decrease by the same amount
- Both sides of the equation could stay the same
Case Study Hannah is the owner of a business. Some of her transactions are listed below. After each transaction, the accounting equation still balances.
Transaction Effects on assets Effects on liabilities or capital A credit customer, Peter, pays the amount owed to Hannah by cheque for $1 120 **Assets increase by $1 120 because the money in the bank increases
Assets decrease by $1 120 because the amount owed by Peter decreases
Overall no change to assetsNo change in liabilities or capital Hannah pays the amount owed to a credit supplier, Rizwan, by cheque for $4 200 **Assets decrease by $4 200 **because the money in the bank decreases ** Liabilities decrease by $4 200 because the amount owed to Rizwan decreases Hannah buys additional fixtures and fittings for $5 500 on credit from FixFit Ltd **Assets increase ** **by $5 500 **because the value of Hannah's assets increases ** Liabilities increase by $5 500 because the amount owed to FixFit Ltd increases Hannah takes goods worth $500 from the business for personal use **Assets decrease by $500 **because the amount of inventory decreases ** Capital decreases by $500 because Hannah takes drawings from the business Hannah transfers $1 000 from her personal bank account into the business bank account **Assets increase by $1 000 **because the money in the bank increases ** Capital increases by $1 000 **because Hannah invests $1 000 into the business Hannah makes $20 profit by selling goods which cost $30 for $50 cash **Assets increase by $50 because the amount of cash increases
Assets decrease by $30 **because the amount of inventory decreases
**Overall assets increase by $20 **** Capital increases by $20 because a profit has been made
Worked Example A business pays one of its trade payables by cheque. Identify the effects on the business' assets and liabilities.
**Effect on assets ** Effect on liabilities A Reduce bank Reduce trade payables B Increase bank Increase trade payables C Reduce trade payables Reduce bank D Increase trade payables Increase bank Answer:
Money in the bank is an** asset** and trade payables is a liability. A payment made by cheque would reduce the money in the bank, therefore reducing the asset. Trade payable is a liability. The business debt would be reduced when payment is made.
Final answer: The answer is A.
Was this revision note helpful?
Build on this topic