Disposal Account (Cambridge International AS Accounting)
Spec point — how to prepare ledger accounts and journal entries for: – depreciation and disposal (including entries for part exchange)
Disposal account
What is a disposal account?
-
A disposal account is used to show the calculation of the profit or loss on a sale of a non-current asset
-
The profit or loss is transferred to the statement of profit or loss
- The account will then have a zero balance
How do I record the sale of a non-current asset in the ledger accounts?
-
The book of prime entry is the journal
-
Deal with each transaction one at a time
-
STEP 1 Reduce the non-current asset account by the original value
-
Credit the non-current asset account
- Because the value of the assets is decreasing
-
Debit the disposal account
-
-
STEP 2 Reduce the provision of depreciation account by the accumulated depreciation of the non-current asset
- Debit the provision for depreciation account
- Credit the disposal account
-
STEP 3 Increase the cash, bank or other receivables account
-
Debit the relevant asset account
- Cash, if received
- Bank, if money is received by cheque or bank transfer
- Other receivables account if it was sold on credit
-
Credit the disposal account
-
-
STEP 4 Include the profit or loss of the sale
-
If a profit is made, then this is an income for the business
- Credit the statement of profit or loss
- Debit the disposal account
-
If a loss is made, then this is an expense to the business
- Debit the statement of profit or loss
- Credit the disposal account
-
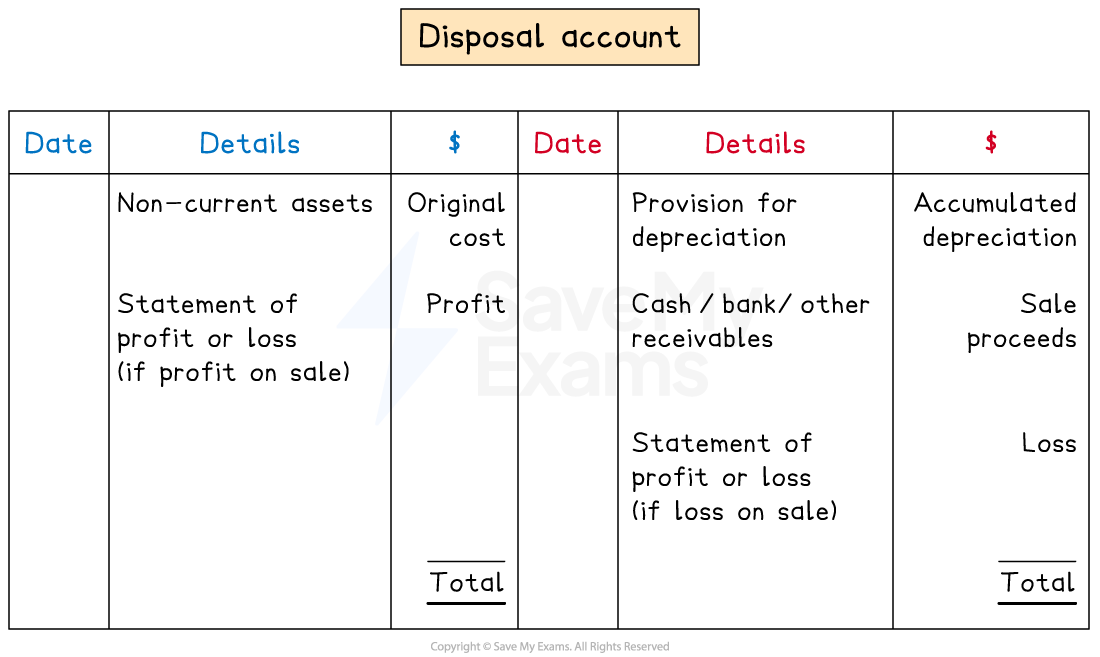
The layout of a disposal account
Exam Hint The disposals account should balance. If it does not balance, then check for any mistakes. Some students calculate the profit or loss by completing steps 1 to 3 and then finding the amount needed to balance the disposal account. If you use this method, be extra careful that you put the entries on the correct side.
Worked Example Riz owes an embroidery business and owns machinery. Riz purchased an additional machine on 1 March 2022 for $30 000. Riz depreciates machinery using the straight-line method using the assumption that machinery fully depreciates after five years. Riz charges depreciation at the end of each month. Riz sells this additional machinery on 31 December 2023 and receives a cheque for $17 500. No other non-current assets were sold in the financial year ending 29 February 2024.
Prepare the disposal account for machinery for the year ended 29 February 2024.
Answer:
Calculate the profit or loss on the sale
- Calculate the yearly depreciation charge
$30 000 ÷ 5 = $6 000
- Calculate the monthly depreciation charge
$6 000 ÷ 12 = $500
Calculate the number of months that Riz owned the machinery
- 1 March 2022 to 31 December 2023 is 22 months
Calculate the total depreciation of the machinery
22 × $500 = $11 000
- Calculate the net book value at 31 December 2023
$30 000 - $11 000 = $19 000
- Calculate the loss on the sale
$19 000 - $17 500 = $1 500
- The sale proceeds are less than the net book value so it was a loss
Fill in the disposal account
- Enter the original cost on the debit side
- Enter the total depreciation on the credit side
- Enter the sale proceeds on the credit side
- Enter the loss on the credit side
Final answer: Riz Disposal Account
Final answer: Date Final answer: Details Final answer: $** Final answer: Date Final answer: Details Final answer: **$ Final answer: 2023
Final answer: Dec 31Final answer: Machinery Final answer: 30 000 Final answer: 2023
Final answer: Dec 31Final answer: Provision for depreciation Final answer: 11 000 Final answer: Dec 31 Final answer: Bank Final answer: 17 500 Final answer: 2024
Final answer: Feb 29Final answer: Statement of profit or loss Final answer: 1 500 Final answer: 30 000 Final answer: 30 000
What is a part-exchange?
- A business might decide to offer a part-exchange when purchasing a non-current asset
- A part-exchange involves the business transferring ownership of another non-current asset to the supplier to offset some of the cost of the new non-current asset
How do I record a part-exchange?
-
A disposal account is used for the non-current asset that is being part-exchanged
-
Instead of the business receiving money, it receives a **reduction **in the amount of a new non-current asset
-
The** journal entries** for this reduction are:
- debit the account for the new non-current asset
- credit the disposal account for the old non-current asset
-
You might need to make another debit entry in the account for the new non-current asset to cover the remaining balance
- The business could pay by cash or bank
- The business could buy the asset on credit
Worked Example Taz is a trader and his accounting year runs to 31 December. On 31 December 2025, Taz purchased a new vehicle costing $25 000. Taz used an old vehicle as part exchange. Taz made a payment of $10 000. The old vehicle was purchased on 1 January 2024 and had originally cost $20 000. No other vehicles were purchased or sold during that time.
Vehicles are depreciated by 20% per annum using the reducing balance method.
(a) Prepare the vehicles at cost account for the year ending 31 December 2025 and bring down the balance on 1 January 2026.
(b) Prepare the vehicle disposal account.
Answer:
(a)
Calculate the value of the reduction offered in the part exchange
$25 000 - $10 000 = $15 000
Fill in the vehicles at cost account
- Enter the original cost of the old vehicle on the debit side at the start of the year as the opening balance
- Enter the original cost of the old vehicle on the credit side when it is part exchanged
- Enter the amount allowed for the part exchange on the debit side
- Enter the amount paid on the debit side
- Balance
Final answer: Taz Vehicles at Cost Account
Final answer: Date Final answer: Details Final answer: $** Final answer: Date Final answer: Details Final answer: **$ Final answer: 2025
Final answer: Jan 1Final answer: Balance b/d Final answer: 20 000 Final answer: 2025
Final answer: Dec 31Final answer: Disposal Final answer: 20 000 Final answer: Dec 31 Final answer: Bank Final answer: 10 000 Final answer: Dec 31 Final answer: Balance c/d Final answer: Dec 31 Final answer: Disposal Final answer: 15 000 Final answer: 45 000 Final answer: 45 000 Final answer: 2026
Final answer: Jan 1Final answer: Balance b/d Final answer: 25 000 (b)
Calculate the accumulated depreciation and net book value of the old vehicle when it was part exchanged
- Depreciation for the year ending 31 December 2024
20% × $20 000 = $4 000
- Net book value on 31 December 2024
$20 000 - $4 000 = $16 000
- Depreciation for the year ending 31 December 2025
20% × $16 000 = $3 200
- Net book value on 31 December 2025
$16 000 - $3 200 = $12 800
- Accumulated depreciation on 31 December 2025
$4 000 + $3 200 = $7 200
Calculate the profit or loss on disposal by finding the difference between this amount and the net book value
- This is a profit as the net book value is lower than the reduction
$15 000 - $12 800 = $2 200
Fill in the disposal account
- Enter the original cost on the debit side
- Enter the total depreciation on the credit side
- Enter the amount allowed for the part exchange on the credit side
- Enter the profit on the debit side
Final answer: Taz Disposal Account
Final answer: Date Final answer: Details Final answer: $** Final answer: Date Final answer: Details Final answer: **$ Final answer: 2025
Final answer: Dec 31Final answer: Vehicles Final answer: 20 000 Final answer: 2025
Final answer: Dec 31Final answer: Provision for depreciation Final answer: 7 200 Final answer: Statement of profit or loss Final answer: 2 200 Final answer: Vehicles Final answer: 15 000 Final answer: 22 000 Final answer: 22 000
Was this revision note helpful?