Reducing Balance Method of Depreciation (Cambridge International AS Accounting)
Reducing balance depreciation
Spec point — how to calculate depreciation using the reducing balance and straight-line methods
What is the reducing balance method of depreciation?
-
The reducing balance method of depreciation assumes that the non-current asset loses value at a rate proportional to its current value
- This means that the expense for its depreciation gets smaller each year as the current value decreases
-
You will be told the percentage of the current value to use for depreciation
-
This method is usually used when a non-current asset initially loses value at a fast rate
- e.g. vehicles, etc
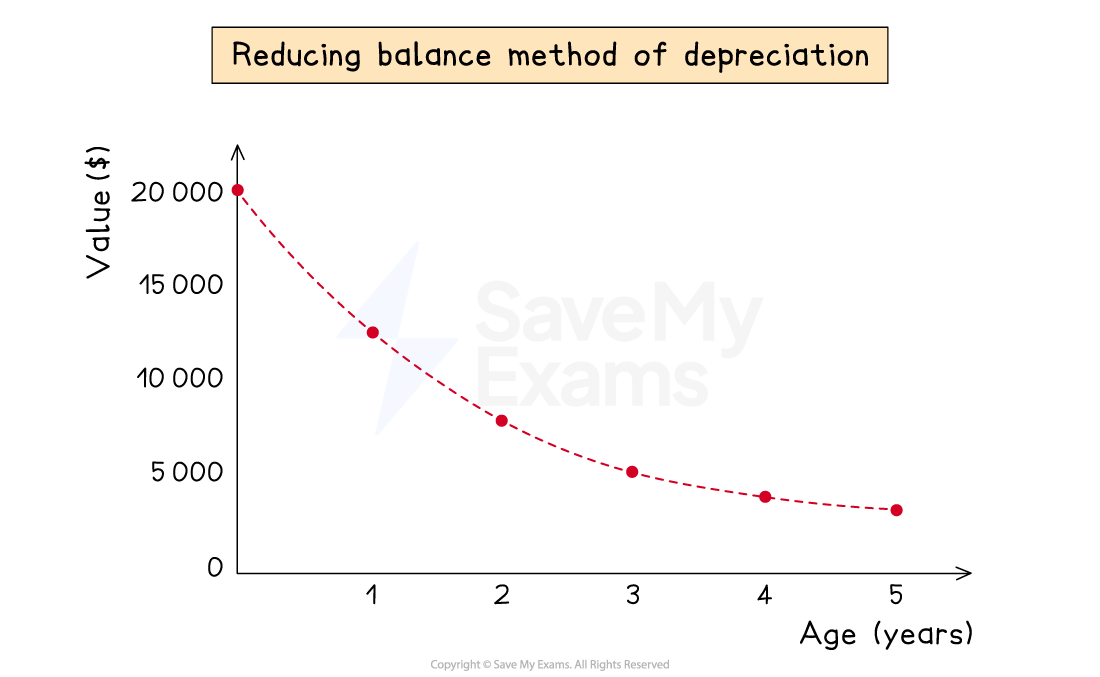
Example of an asset, which cost $20 000, being charged depreciation at 30% per annum using the reducing balance method
How do I calculate depreciation using the reducing balance method?
-
Find the percentage of the current net book value
- This will be the depreciation charge for that year
-
If you need to calculate the depreciation for multiple years, then calculate one year at a time
- Find the depreciation charge for one year using the net book value at that start of the year
- Subtract this amount from the net book value at the start of the year to find the new net book value
- Find the depreciation charge for the next year using the net book value at the start of that year
- Continue this process
-
If you just need to find the current net book value then you can use some maths skills
- Subtract the percentage from 100%
- Write this as a decimal
- Raise this to the power of the number of years
- Multiply this by the original value
Exam Hint The reducing balance method is similar to compound interest calculations used in maths.
Amounts should always be given to the nearest dollar in exams.
Worked Example Abi purchases a vehicle for $16 000. Machinery is depreciated at 25% per annum using the reducing balance method.
Calculate the net book value of the machinery after 3 years.
Answer:
Method 1: Year-by-year
- Find the depreciation charged in each year by finding the percentage of the net book value at that time
- Subtract that year’s depreciation from the net book value to find the net book value at the end of the year
End of year Depreciation charge Net book value 0 - $16 000 1 25% × $16 000 = $4 000 $16 000 - $4 000 = $12 000 2 25% × $12 000 = $3 000 $12 000 - $3 000 = $9 000 3 25% × $9 000 = $2 250 *$9 000 - $2 250 = $6 750 Method 2: Compound interest
- Subtract the percentage from 100%
100% - 25% = 75%
- Write this as a decimal
75% = 0.75
- Raise this to the power of the number of years
0.753
- Multiply this by the original value
$16 000 × 0.75*3** =* $6 750
Was this revision note helpful?