The Double Entry System (Cambridge International AS Accounting)
Spec point — the principles of the double entry system to record business transactions
The double entry system
What is the double entry system?
-
The double entry system is used by book-keepers
- The double entry system is used to improve the accuracy of financial statements
-
The double entry system is closely linked to the accounting equation
- Assets = Liabilities + Capital
-
The equation is always balanced
-
Each transaction causes both sides of the equation to:
- increase
- or decrease
- or remain the same
-
Each transaction is entered into two accounts
- One is called a debit entry
- One is called a credit entry
What is the layout of a ledger account?
-
Each account will be split into two sides
-
The debit entries appear on the left
- This side is sometimes labelled as Dr
-
The credit entries appear on the right
- This side is sometimes labelled as Cr
-
-
When you make an entry you need to include:
-
The date of the transaction
-
The details of the transaction
- This is normally the name of the other account involved
-
The value of the transaction
-
-
These accounts are sometimes referred to as T accounts
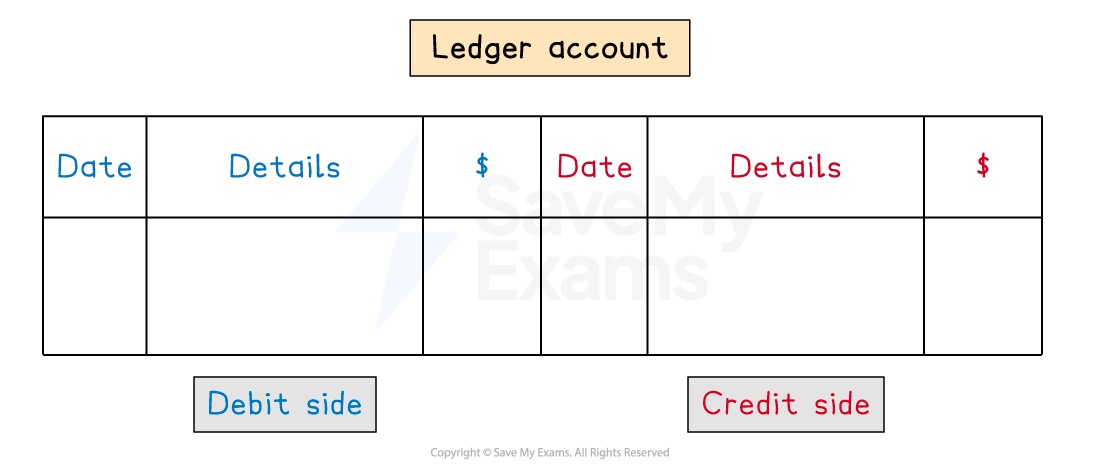
Example of a ledger account
Debits & credits
Spec point — the principles of the double entry system to record business transactions
What is a debit entry?
-
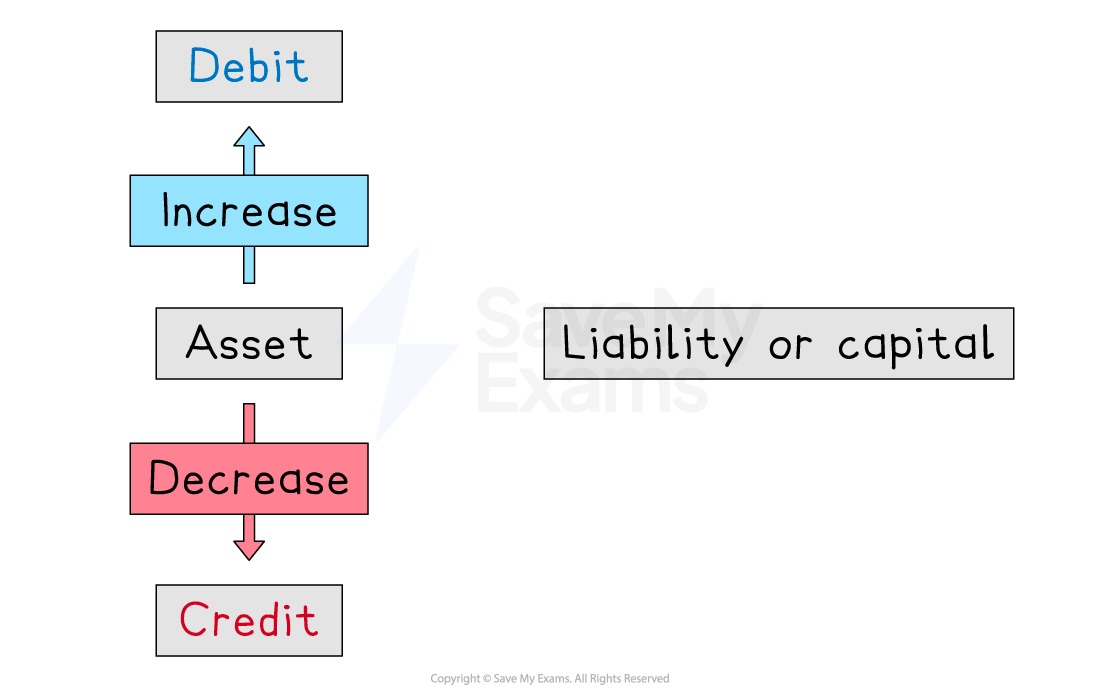
A debit entry is used to:
-
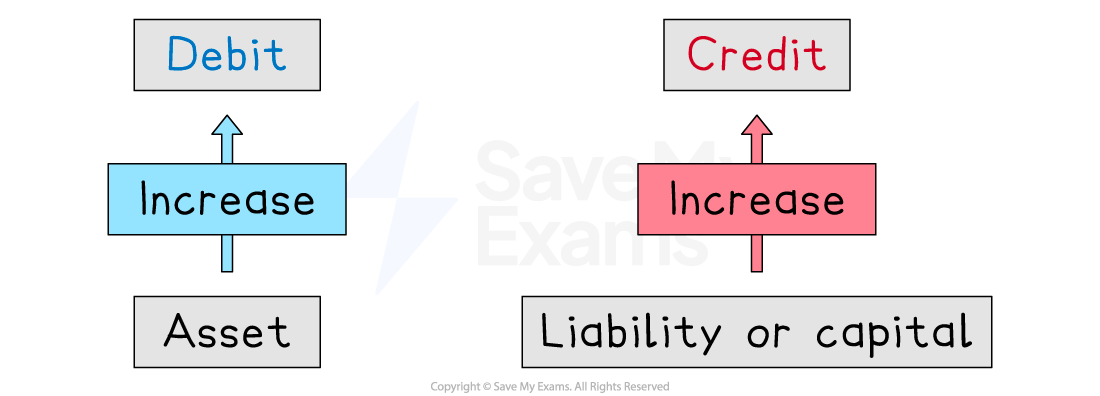
increase the value of an asset
- The left-hand side of the accounting equation increases
-
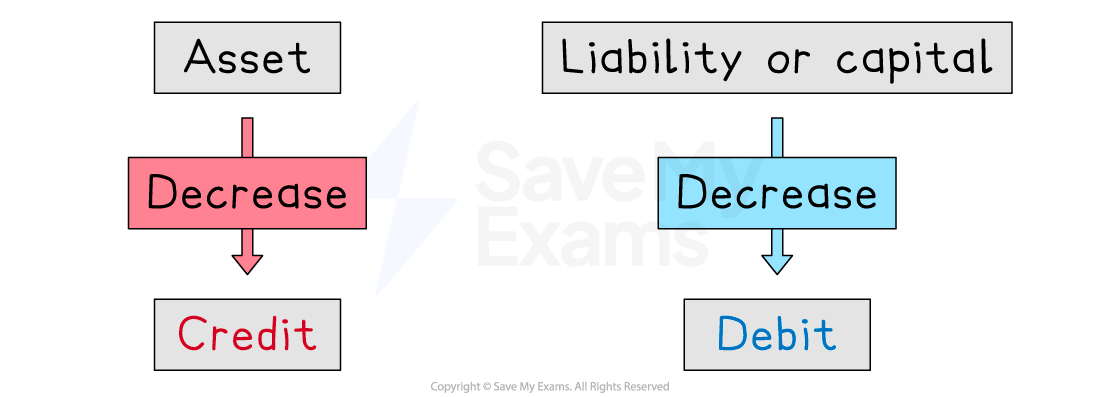
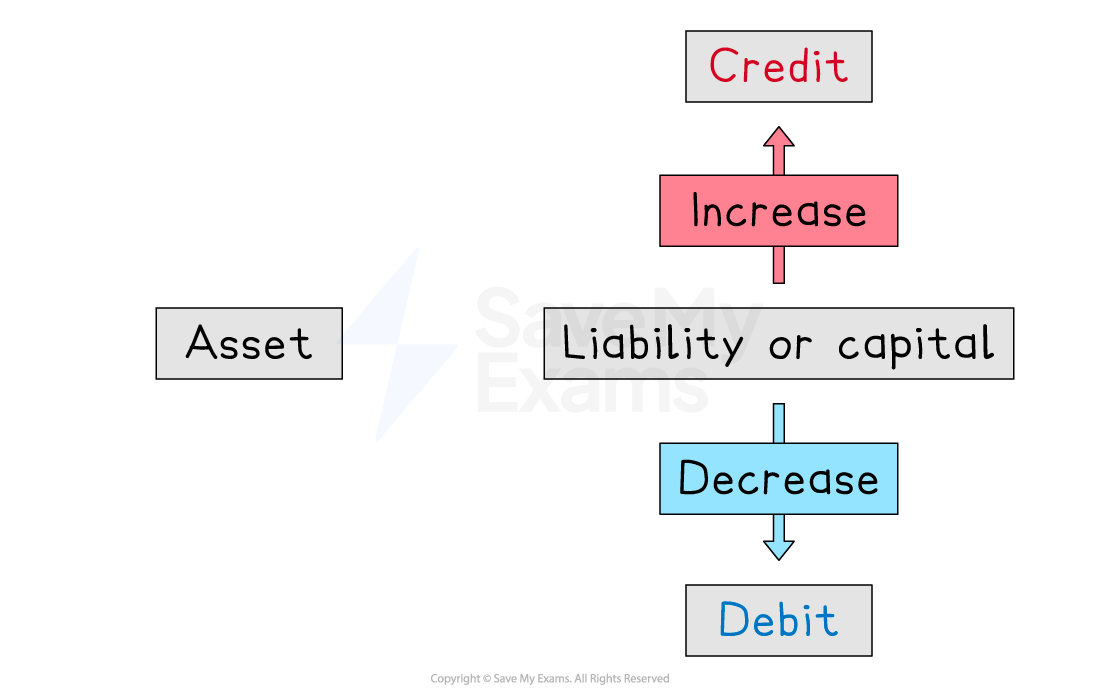
decrease the value of a liability or the capital
- The right-hand side of the accounting equation decreases
-
What is a credit entry?
-
A credit entry is used to:
-
increase the value of a liability or the capital
- The right-hand side of the accounting equation increases
-
decrease the value of an asset
- The left-hand side of the accounting equation decreases
-
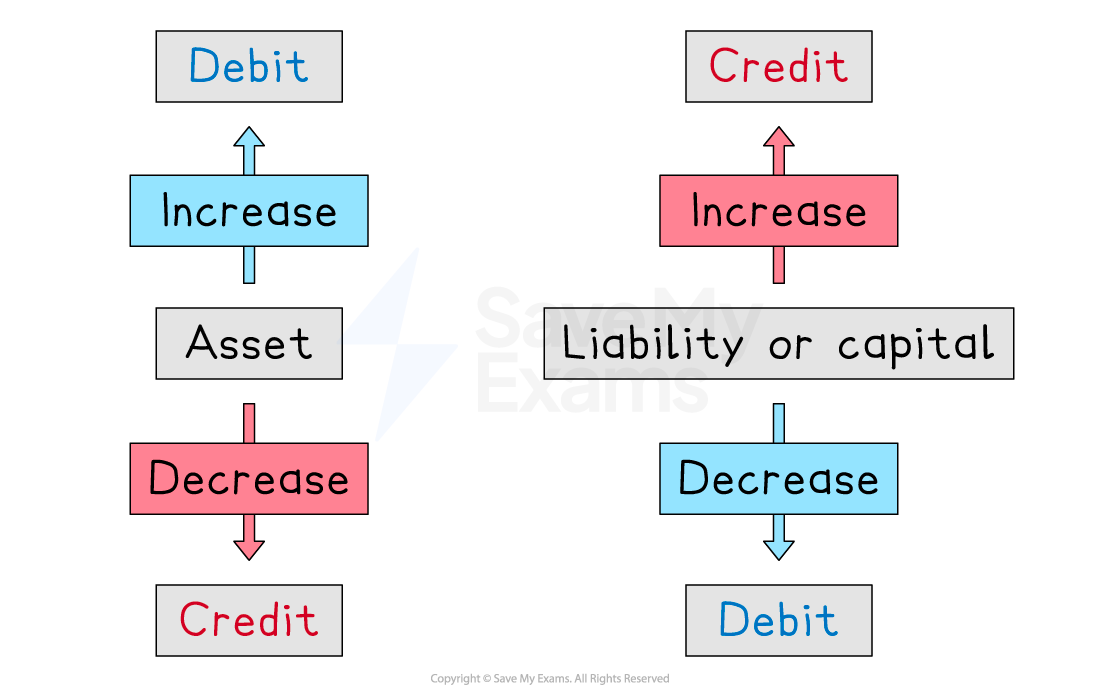
Debit and credit entries achieve specific purposes depending on the type of account
Which accounts should I debit?
-
Debit an asset account when its value is increasing
-
You receive cash
- Debit the cash account
-
A customer buys goods on credit
- Debit their trade receivables account
-
-
Debit a liability account when its value is decreasing
-
You make a repayment on a bank loan
- Debit the bank loan account
-
You pay an invoice to a credit supplier
- Debit their trade payables account
-
-
Debit other accounts when the transaction decreases the capital
-
You take assets from the business for personal use
- Debit the drawings account
-
You pay an expense which decreases the profit
- Debit the relevant expense account
- Such as purchases, rent paid, discount allowed, etc
-
Which accounts should I credit?
-
Credit a liability account when its value is increasing
-
You take out a bank loan
- Credit the bank loan account
-
You buy goods on credit from a supplier
- Credit their trade payables account
-
-
Credit an asset account when its value is decreasing
-
You pay rent by bank transfer
- Credit the bank account
-
A credit customer pays their invoice
- Credit their trade receivables account
-
-
Credit other accounts when the transaction increases the capital
-
You put more personal assets (such as money) into the business
- Credit the capital account
-
You receive income which increases the profit
- Credit the relevant income account
- Such as sales, rent received, discount received, etc
-
How do I enter the transactions into the accounts using the double-entry system?
-
STEP 1 Identify the accounts involved in the transaction
- One is usually cash, bank, trade receivables or trade payables
-
STEP 2 Identify whether each account affects the assets, liabilities or capital
- Usually this is cash, trade receivables or trade payables
-
STEP 3 Determine whether the value of each account is increasing or decreasing
-
STEP 4 Debit or credit the account
-
Debit the account if:
- It is an asset account and its value is increasing
- It is a liability or the capital account and its value is decreasing
-
Credit the account if:
- It is an asset account and its value is decreasing
- It is a liability or the capital account and its value is increasing
-
Examples where assets increase and liabilities or capital increase
| Transaction | Debit Asset that is increasing | Credit Liability or capital that is increasing |
|---|---|---|
| Credit sale to a customer | Trade receivables - The business is owed more money by the customer | Sales - Sales increase profit - Increasing profit increases capital |
| The business takes out a bank loan | Bank - The business owns more money in the bank | Bank loan - The business owes more money due to the bank loan |
| The business receives money for rent from a tenant | Bank - The business owns more money in the bank | Rent received - Income increases profit - Increasing profit increases capital |
| The owner deposits some of their personal money into the business bank account | Bank - The business owns more money in the bank | Capital - The business has more capital |
Examples where assets decrease and liabilities or capital decrease
| Transaction | Debit Capital or liability that is decreasing | Credit Asset that is increasing |
|---|---|---|
| The owner takes money out of the business bank account for personal use | Drawings - The owner takes money from the bank as drawings - Taking drawings reduces the capital | Bank - The business owns less money in the bank |
| The business pays cash for an electricity bill | Electricity - Expenses decrease profit - Decreasing profit decreases capital | Cash - The business owns less cash in hand |
| The business makes a cash payment to a credit supplier | Trade payables - The business owes less money to the supplier | Cash - The business owns less cash in hand |
Examples where assets increase and decrease
| Transaction | Debit Asset that is increasing | Credit Asset that is decreasing |
|---|---|---|
| The business receives a cash payment from a credit customer | Cash - The business owns more cash in hand | Trade receivables - The business is owed less money by the customer |
| The business withdraws cash from the business bank account | Cash - The business owns more cash in hand | Bank - The business owns less money in the bank |
| The business deposits cash into the business bank account | Bank - The business owns more money in the bank | Cash - The business owns less cash in hand |
Examples where liabilities or capital increase and decrease
| Transaction | Debit Capital or liability that is decreasing | Credit Liability or capital that is increasing |
|---|---|---|
| The business purchases goods on credit from a supplier | Purchases - Purchases decrease profit - Decreasing profit decreases capital | Trade payables - The business owes more money to the supplier |
Worked Example Hina is a sole trader.
Complete the table below to show the accounts that Hina should debit and credit for each of the following transactions.
Transaction Account to be debited Account to be credited Hina sells goods on credit to Priya Hina receives a cash payment from Priya Hina pays an electricity bill by cheque Hina buys goods on credit from Dida Hina repays some of a bank loan by bank transfer Hina takes ownership of a company vehicle for her own use Hina puts some of her own money into the business bank account Answer:
Transaction Account to be debited Account to be credited Hina sells goods on credit to Priya Final answer: Priya
- Priya is a trade receivable (she owes money to Hina)
- A trade receivable is an asset
- Priya owes more money
- The assets are increasingFinal answer: Sales
- Sales increasing profit
- Increasing profit increases the capital
- The capital is increasingHina receives a cash payment from Priya Final answer: Cash
- Hina receives cash
- Cash is an asset
- The assets are increasingFinal answer: Priya
- Priya is a trade receivable (she owes money to Hina)
- A trade receivable is an asset
- Priya owes less money
- The assets are decreasingHina pays an electricity bill by bank transfer Final answer: Electricity
- Electricity is an expense
- Expenses reduce the profit
- Decreasing profit decreases capital
- The capital is decreasingFinal answer: Bank
- The cheque pays money from the bank
- The money is the bank is an asset
- The assets are decreasingHina buys goods on credit from Dida Final answer: Purchases
- Purchases are an expense
- Expenses reduce the profit
- Decreasing profit decreases capital
- The capital is decreasingFinal answer: Dida
- Dida is a trade payable (Hina owes money to her)
- A trade payable is a liability
- Dida is owed more money
- The liabilities are increasingHina repays some of a bank loan by bank transfer Final answer: Bank loan
- The bank loan is a liability (Hina owes money)
- The amount Hina owes is reduced
- The liabilities are decreasingFinal answer: Bank
- Hina pays using money from the bank
- The money is the bank is an asset
- The assets are decreasingHina takes ownership of a company vehicle for her own use Final answer: Drawings
- Hina takes an asset from the business for personal use
- This is a form of taking drawings
- Drawings reduces the capital
- The capital is decreasingFinal answer: Vehicles
- Hina's business owns fewer vehicles
- Vehicles are assets
- The assets are decreasingHina puts some of her own money into the business bank account Final answer: Bank
- Hina's business receives money in the bank
- The money is the bank is an asset
- The assets are increasingFinal answer: Capital
- Hina is introducing extra capital to the business
- The capital is increasing
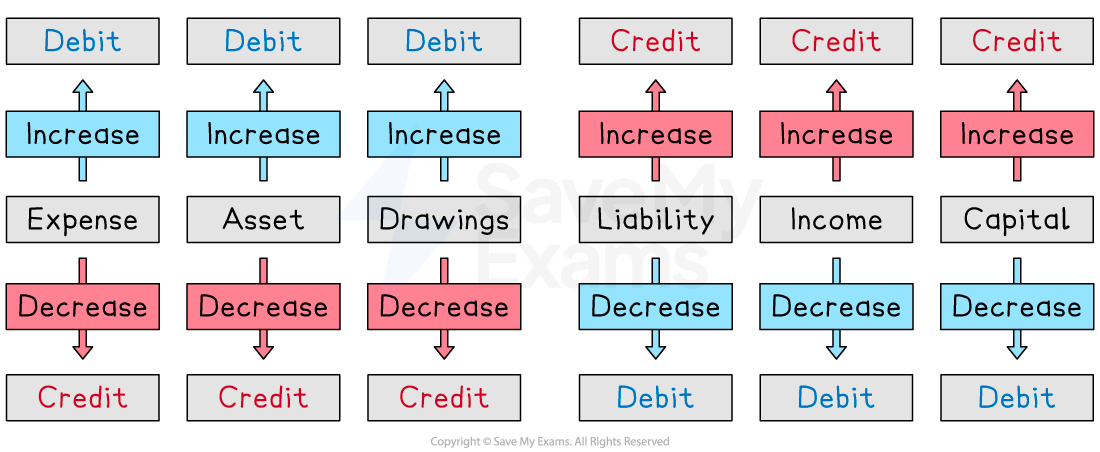
Exam Hint To remember which side of an account to record a transaction, you can use the acronym DEAD CLIC.
- The transaction is on the debit side for expense, asset, and drawings accounts if the account is increasing.
- The transaction is on the credit side for liability,income, and capital accounts if the account is increasing.
- If the account is decreasing then the transaction is recorded on the opposite side!
Another set of acronyms is:
- DIADL: Debits Increase** A**ssets or Decrease Liabilities
- CILDA: Credits** I** ncrease Liabilities or Decrease Assets
However, try to remember the connection to the accounting equation.
Was this revision note helpful?
Build on this topic