Correction of Errors Using Journal Entries (Cambridge International AS Accounting)
Spec point — how to prepare ledger accounts and journal entries to correct errors
Correction of errors using journal entries
How do I correct accounting errors?
- STEP 1 Identity how the accounts currently look with the errors
- STEP 2 Identify how the accounts should look if the transactions were entered correctly
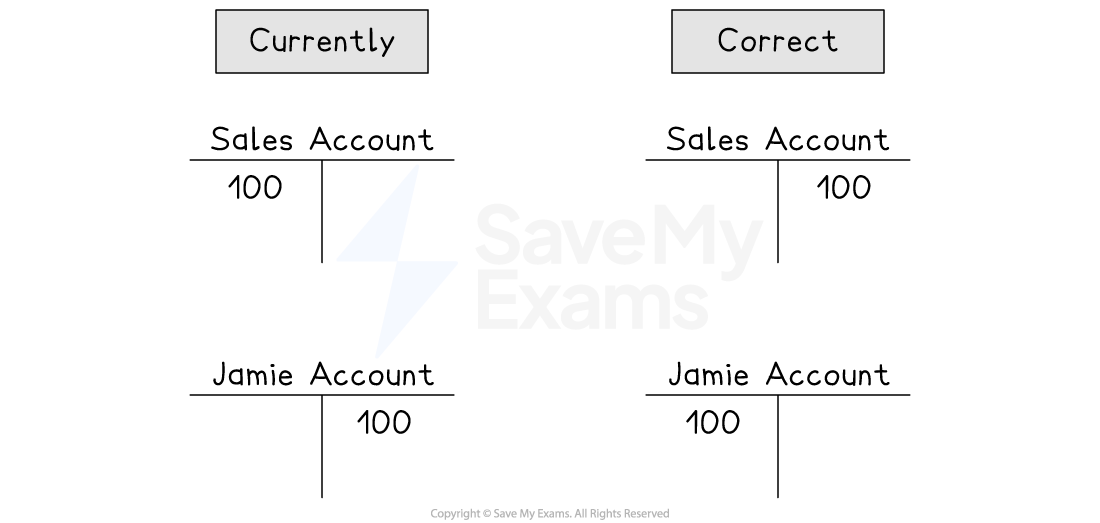
Example of errors in accounts
- STEP 3 Make the necessary entries to fix the errors
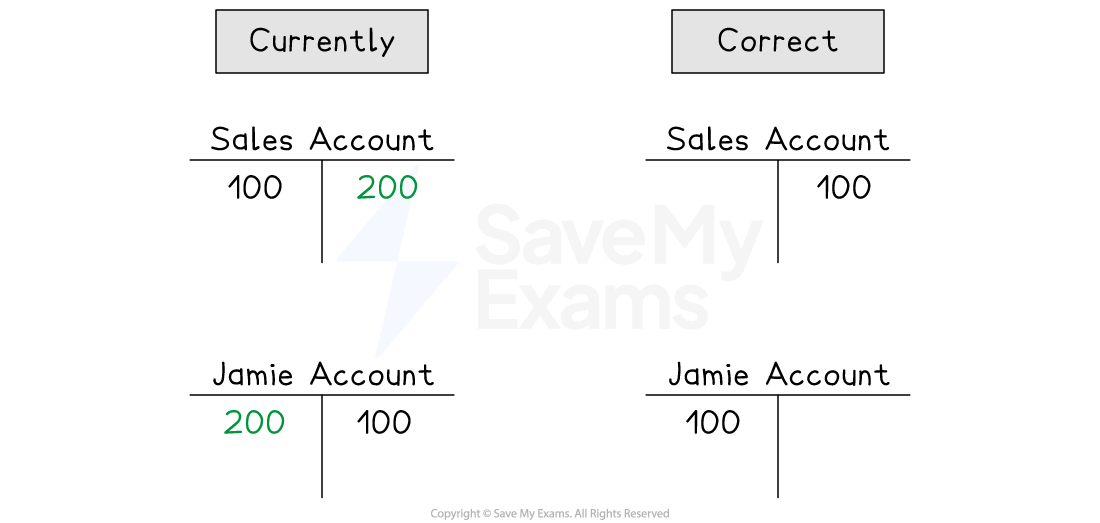
Example of correction of errors
Exam Hint If you are not given the actual figures, then you can make them up to help you spot how to correct them. For example, if the sales account is overcast by $20, then pretend it should be $100 which means it currently has a balance of $120.
How do I correct errors using journal entries?
-
You can correct errors by making the appropriate entries into the ledger accounts
-
The journal will be used as the book of prime entry
-
Enter the account that needs to be debited
- It is conventional for debit entries to appear first
-
Enter the account that needs to be credited
- It is conventional to indent the details for credit entries
-
Give a narrative for the journal entry
- State “Correction of error”
- Give a brief description of the error
Exam Hint Narratives are not always required. The exam question will make it clear whether they are needed.
Worked Example Constance is a trader. On 1 December 2025, Constance identified an error in her accounts. She had sold $100 goods on credit to Jamie but make the entries on the wrong side of both accounts.
Prepare journal entries to fix the error. Narratives are required.
Answer:
$200 needs to be entered on the correct side of both accounts
- $100 to undo the error
- $100 to enter the correct transaction
Make the journal entries
Final answer: Journal
Final answer: Details Final answer: Debit
$**Final answer: Credit
$Final answer: Jamie Final answer: 200 Final answer:** Sales Final answer: 200 Final answer: Correction of error of putting the values on the wrong side of the accounts
Was this revision note helpful?