Redistributive Policies (Cambridge International A-Level Economics)
Redistribution policies
- Governments use redistribution policies to reduce inequality and improve equity by transferring income or resources from higher-income to lower-income groups
- The central evaluative tension for every policy is the equity-efficiency trade-off: does the policy improve fairness, and at what cost to productive and dynamic efficiency?
- There are four key policies to consider: means-tested benefits, universal benefits, negative income tax and universal basic income
1. Means-tested benefits
-
These are benefits paid only to individuals whose income and/or wealth falls below a specified threshold - recipients must demonstrate financial need to qualify
- The government targets support at those who need it most, making this approach cost-effective relative to universal provision
- Examples include housing benefit, food assistance, unemployment support and healthcare subsidies for low-income households
Evaluating means-tested benefits
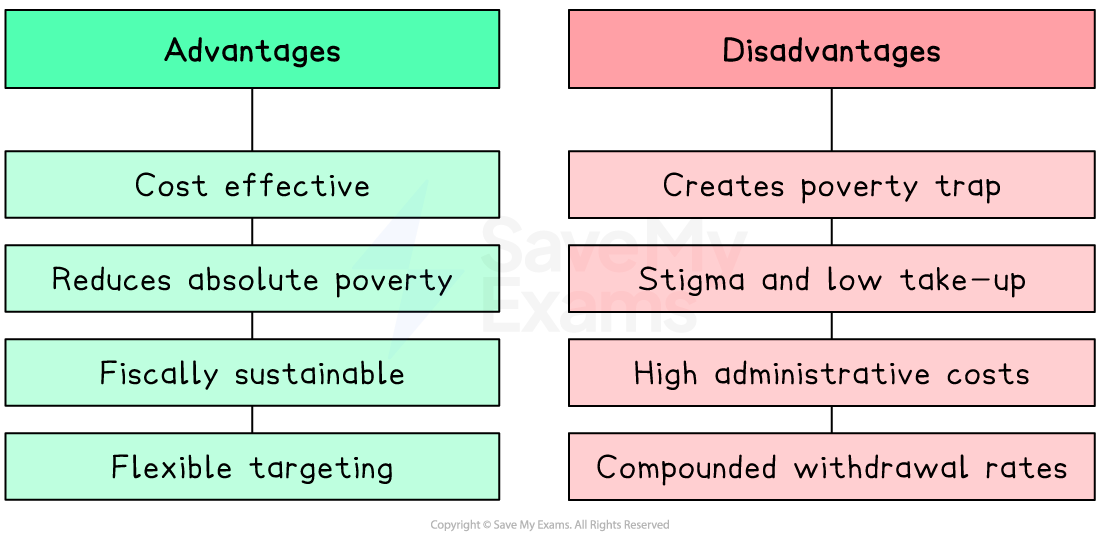
The advantages and disadvantages of means tested benefits
| Advantages | Disadvantages |
|---|---|
| - Cost-effective - targets spending at those genuinely in need, avoiding payments to higher-income groups | - Creates the poverty trap - benefit withdrawal as income rises produces high effective marginal tax rates, reducing the incentive to work |
| - Reduces absolute poverty - ensures a minimum income floor for the most vulnerable | - Stigma and low take-up - means-testing requires individuals to prove need, which can deter eligible claimants due to shame or bureaucratic complexity |
| - Fiscally sustainable - lower cost than universal provision, leaving resources for other public spending | - High administrative costs - assessing and monitoring eligibility is expensive and resource-intensive |
| - Flexible - can be targeted at specific groups such as families with children, elderly or disabled | - Poverty trap worsens with multiple benefits - individuals receiving several means-tested benefits simultaneously face compounded withdrawal rates |
Case Study Universal Credit in the United Kingdom
The context
The UK's legacy benefit system consisted of six separate means-tested benefits including housing benefit, tax credits and income support
Each had different withdrawal rates and eligibility rules, creating a complex system where some low-income workers faced effective marginal tax rates (EMTR) above 90% - a severe poverty trap discouraging progression into work
Actions taken
- Universal Credit (UC) was introduced from 2013, merging six benefits into a single payment with a unified taper rate of 55p withdrawn per £1 of earned income
- The policy aimed to make work always pay by ensuring the EMTR never exceeded 55% - significantly below the rates in the legacy system
- By 2023, approximately 6 million households were receiving Universal Credit
Outcomes
- Evidence suggests UC improved work incentives at the margin compared to the legacy system
- The unified taper rate reduced the most extreme poverty trap cases
- However critics argue a 55% taper rate remains high, and that the interaction with childcare costs pushes effective marginal tax rates above 70% for many families
- The five-week wait for first payment also pushed many new claimants into debt, illustrating that poorly designed implementation can undermine a well-intentioned policy - a form of government failure
2. Universal benefits
-
These are benefits paid to all individuals in a category regardless of income or wealth - no means test is applied
- Examples include universal child benefit, state pensions paid to all retirees, and universal healthcare
-
The defining feature is that entitlement is based on status (being a child, being retired, being a citizen) rather than financial need
Evaluating universal benefits
| Advantages | Disadvantages |
|---|---|
| - No poverty trap - benefits are not withdrawn as income rises, so there is no disincentive to work | - Poor targeting - payments go to higher-income individuals who do not need them, reducing cost-effectiveness |
| - No stigma - universal entitlement removes the shame associated with means-testing, improving take-up | - Very expensive - universal provision is significantly more costly than means-tested alternatives |
| - Low administrative cost - no eligibility assessment required | - Regressive in relative terms - if a flat-rate universal benefit represents a larger share of a low-income household's budget, this partially addresses inequality, but the absolute payment is the same for all |
| - Social cohesion - universal benefits foster a sense of shared entitlement across income groups | - Opportunity cost - fiscal resources used for universal payments cannot be used for targeted poverty reduction or other public goods |
3. Negative income tax
-
This is a system in which the tax and benefit systems are merged
- Individuals above a specified income threshold pay tax in the normal way, while those below it receive a government payment (the negative tax) rather than paying tax
-
Proposed by economist Milton Friedman as a way to eliminate the poverty trap while maintaining work incentives
-
The mechanism:
- A break-even income is set - above this level individuals pay tax; below it they receive payments
- As earned income rises towards the break-even point, the negative tax payment falls at a constant taper rate
- Because the taper rate is consistent and moderate, the EMTR never becomes prohibitively high - work always pays at the margin
-
This replaces the complex array of means-tested benefits with a single, streamlined system
Evaluating negative income tax
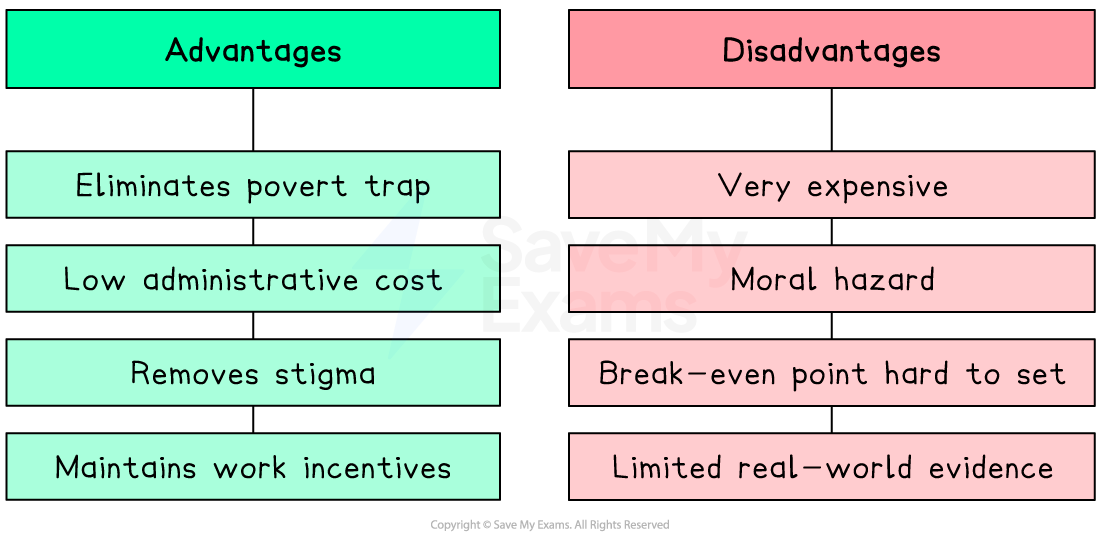
The advantages and disadvantages of negative income tax
| Advantages | Disadvantages |
|---|---|
| - Eliminates the poverty trap - consistent taper rate ensures work always pays at the margin | - Very expensive - providing a guaranteed income to all below the threshold has significant fiscal cost |
| - Low administrative cost - operated through the existing tax system, replacing multiple benefit bureaucracies | - Moral hazard - guaranteed income may reduce labour supply as some individuals choose not to work |
| - Removes stigma - payments are made through the tax system with no means-testing | - Setting the correct break-even point is difficult - too low and poverty persists; too high and fiscal costs become unsustainable |
| - Maintains incentives - individuals always gain from earning more, unlike means-tested systems | - No country has fully implemented it - evidence on real-world effectiveness is limited to small-scale pilots |
4. Universal basic income
-
Universal basic income (UBI) a regular, unconditional cash payment made to every citizen regardless of income, employment status or need
- Unlike negative income tax, UBI is paid to everyone, not just those below a threshold
- Unlike means-tested benefits, it is never withdrawn as income rises, eliminating the poverty trap entirely
-
UBI has gained significant policy attention as a potential response to technological unemployment and the gig economy
Evaluating universal basic income
| Advantages | Disadvantages |
|---|---|
| - Completely eliminates the poverty trap - no withdrawal means no disincentive to work | - Extremely expensive - paying every citizen an unconditional income requires very high government expenditure or tax rates |
| - Provides income security - guarantees a floor below which no one can fall, reducing absolute poverty | - Moral hazard - unconditional payment may significantly reduce labour supply, reducing productive capacity |
| - Adapts to changing labour markets - supports workers in the gig economy and those displaced by automation | - Poor targeting - paying wealthy citizens the same as poor ones is highly inefficient use of fiscal resources |
| - Low administrative cost - no means-testing or eligibility assessment | - Inflationary risk - large unconditional cash injections may increase aggregate demand and push up prices |
| - Removes stigma - universal entitlement with no conditions attached | - Limited real-world evidence - pilots have been small-scale and short-term, making it difficult to assess long-run behavioural effects |
Case Study Universal basic income pilot in Kenya
The context
Kenya has high levels of both absolute and relative poverty, with significant rural populations engaged in subsistence agriculture and informal work
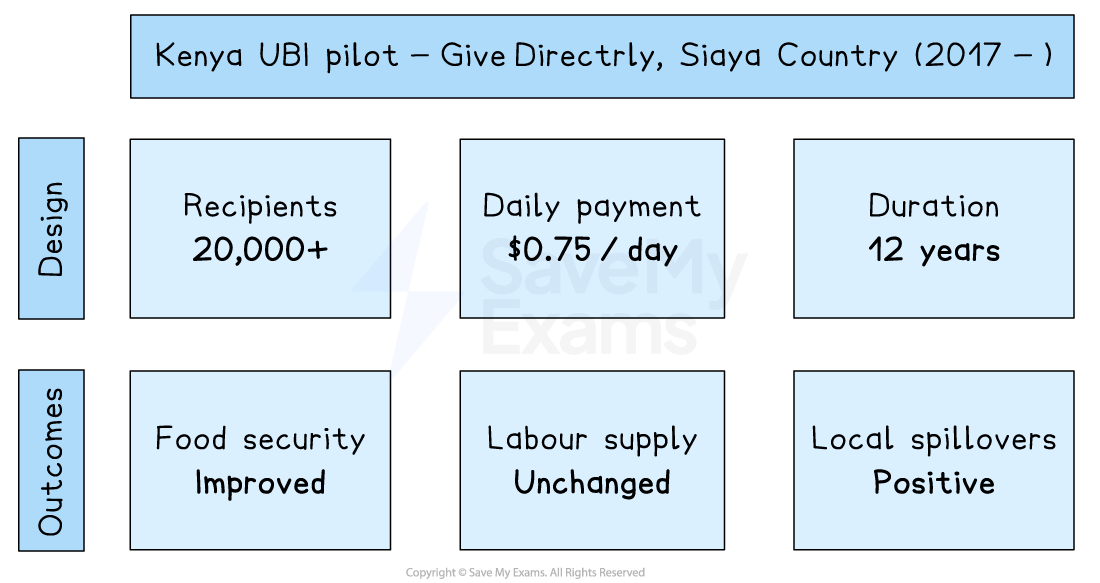
GiveDirectly, an NGO working with the Kenyan government, launched the world's largest and longest-running UBI experiment in 2017, providing unconditional cash transfers to over 20,000 recipients in rural villages in Siaya County
Actions taken
- Long-term recipients received approximately $0.75 per day - roughly 75% of the average consumption level in recipient villages - for a guaranteed period of 12 years
- Short-term recipients received the same total amount as a lump sum over two years
- A control group of villages received no payments, allowing rigorous comparison of outcomes
Outcomes
Early results published by researchers from Princeton and UC San Diego found significant positive effects
- Recipient households increased assets, food security and psychological wellbeing
- There was evidence of positive spillover effects to non-recipient households in the same villages through increased local economic activity
- Crucially, there was no significant reduction in labour supply - recipients worked as much as control group households, challenging the moral hazard concern
However critics note that a donor-funded pilot with a guaranteed end date cannot replicate the fiscal and behavioural dynamics of a permanent government-funded UBI at national scale
Comparing the four policies
| Policy | Poverty trap? | Targets the poorest? | Administrative cost | Fiscal cost |
|---|---|---|---|---|
| Means-tested benefits | - Yes — benefit withdrawal | - Yes | - High | - Medium |
| Universal benefits | - No | - No — paid to all | - Low | - High |
| Negative income tax | - No — consistent taper | - Partially | - Low | - High |
| Universal basic income | - No — never withdrawn | - No — paid to all | - Very low | - Very high |
Exam Hint The poverty trap is the central weakness of means-tested benefits - benefit withdrawal combined with income tax creates a high EMTR, so work does not pay at the margin.
NIT and UBI both solve the poverty trap but at significant fiscal cost - the key distinction is that NIT targets those below a threshold; UBI is paid to everyone.
Structure evaluation using the equity-efficiency trade-off: means-tested benefits are fiscally efficient but damage work incentives; UBI preserves incentives but is poorly targeted and very expensive.
The Kenya pilot challenges the moral hazard assumption - but pilot evidence may not generalise to permanent national-scale implementation.
Was this revision note helpful?
Build on this topic