Foreign Direct Investment (FDI) & External Investment (Cambridge International A-Level Economics)
External capital flow that affect developing economies
-
FDI is an equity flow — foreign firms acquire ownership of productive assets in the host economy
-
External debt is a credit flow — the host country borrows from foreign lenders and is obliged to repay
-
FDI and external debt are two of the main forms of external capital flow that affect developing economies — alongside aid and remittances
- Both can support development, but both also carry significant risks if poorly managed
-
FDI brings risk-sharing (the foreign investor bears losses if the project fails), while external debt creates fixed repayment obligations regardless of how the borrowed funds perform
Foreign direct investment (FDI)
-
Foreign Direct Investment (FDI) is long-term cross-border investment in productive assets (factories, equipment, infrastructure) by foreign firms establishing or expanding operations abroad
-
The investing firm acquires significant ownership and control - typically defined as a stake of 10% or more in the host-country entity
- FDI is the main vehicle through which multinational companies operate internationally
- FDI is distinct from portfolio investment, which involves the purchase of shares or bonds without controlling stakes and is far more volatile
- FDI typically involves a long-term commitment, making it more stable than portfolio flows that can reverse rapidly during financial stress
Consequences of FDI
- The consequences overlap with those of MNCs, but should be understood as the effects of the capital flow itself, not the firm
Positive consequences
| Consequence | Explanation |
|---|---|
| Fills the savings gap | - FDI provides external capital where domestic savings are insufficient to fund needed investment |
| Job creation | - Direct employment in FDI-funded operations and indirect employment through local supplier linkages |
| Technology and skills transfer | - Workers and local firms gain exposure to advanced production methods and management practices |
| Tax revenue | - Corporate, employment and indirect taxes from FDI operations expand the host government's tax base |
| Export earnings | - FDI-funded production destined for global markets generates foreign exchange |
| More stable than portfolio flows | - Long-term commitment makes FDI less prone to sudden reversal during crises |
Negative consequences
| Consequence | Explanation |
|---|---|
| Profit repatriation | - Returns flow back to the home country, reducing the long-run benefit to the host economy |
| Limited local linkages | - If MNCs import most inputs from abroad, the multiplier effect on the host economy is small |
| Crowding out | - Better-resourced foreign firms may displace local enterprises |
| Tax avoidance | - Transfer pricing can shift reported profits to low-tax jurisdictions, reducing host tax revenue |
| Vulnerability to MNC decisions | - Host economies can lose significant employment and revenue if MNCs relocate |
External debt
-
External debt is owed to foreign creditors - including foreign governments, international financial institutions and private bondholders
- Most low- and middle-income economies carry some external debt; problems arise when the burden becomes unsustainable
| Cause | Explanation |
|---|---|
| Borrowing for development | - Governments borrow to fund infrastructure, education and healthcare investment that exceeds domestic resources |
| Persistent trade deficits | - Countries that consistently import more than they export must finance the gap through external borrowing |
| External shocks | - Sudden events such as oil price spikes, commodity price collapses or pandemics disrupt revenue and force additional borrowing |
| Rising global interest rates | - When global rates rise (such as during the 1979–82 Volcker shock or the 2022–23 Federal Reserve tightening), debt service costs rise sharply for borrowers |
| Currency depreciation | - Debt denominated in foreign currency (typically US dollars) becomes more expensive to service when the local currency falls |
| Capital flight | - Sudden withdrawal of foreign capital can force governments to borrow at unfavourable terms to maintain reserves |
| Lender enthusiasm | - Periods of abundant global credit (1970s petrodollar recycling, 2010s low interest rates) encourage over-borrowing |
Consequences of debt
-
Debt is not inherently negative - borrowing for productive investment can support growth
- The problems arise when debt becomes excessive or is used unproductively
Negative consequences
| Consequence | Explanation |
|---|---|
| Debt service burden | - Interest and principal repayments divert resources from productive uses |
| Crowding out public spending | - Debt service competes with spending on health, education and infrastructure - Many heavily indebted economies spend more on debt than on healthcare |
| Currency risk | - Debt in foreign currencies becomes more expensive when the local currency depreciates, creating self-reinforcing crisis dynamics |
| Loss of policy autonomy | - Restructuring agreements with the IMF often require austerity measures, tax rises or privatisation |
| Sovereign default risk | - Inability to repay forces default, damaging the country's credit rating and access to future borrowing |
| Debt overhang | - Very high debt levels deter both foreign and domestic investment, as future returns are expected to be taxed away to service debt |
Case Study Sri Lanka's 2022 Debt Crisis
Context
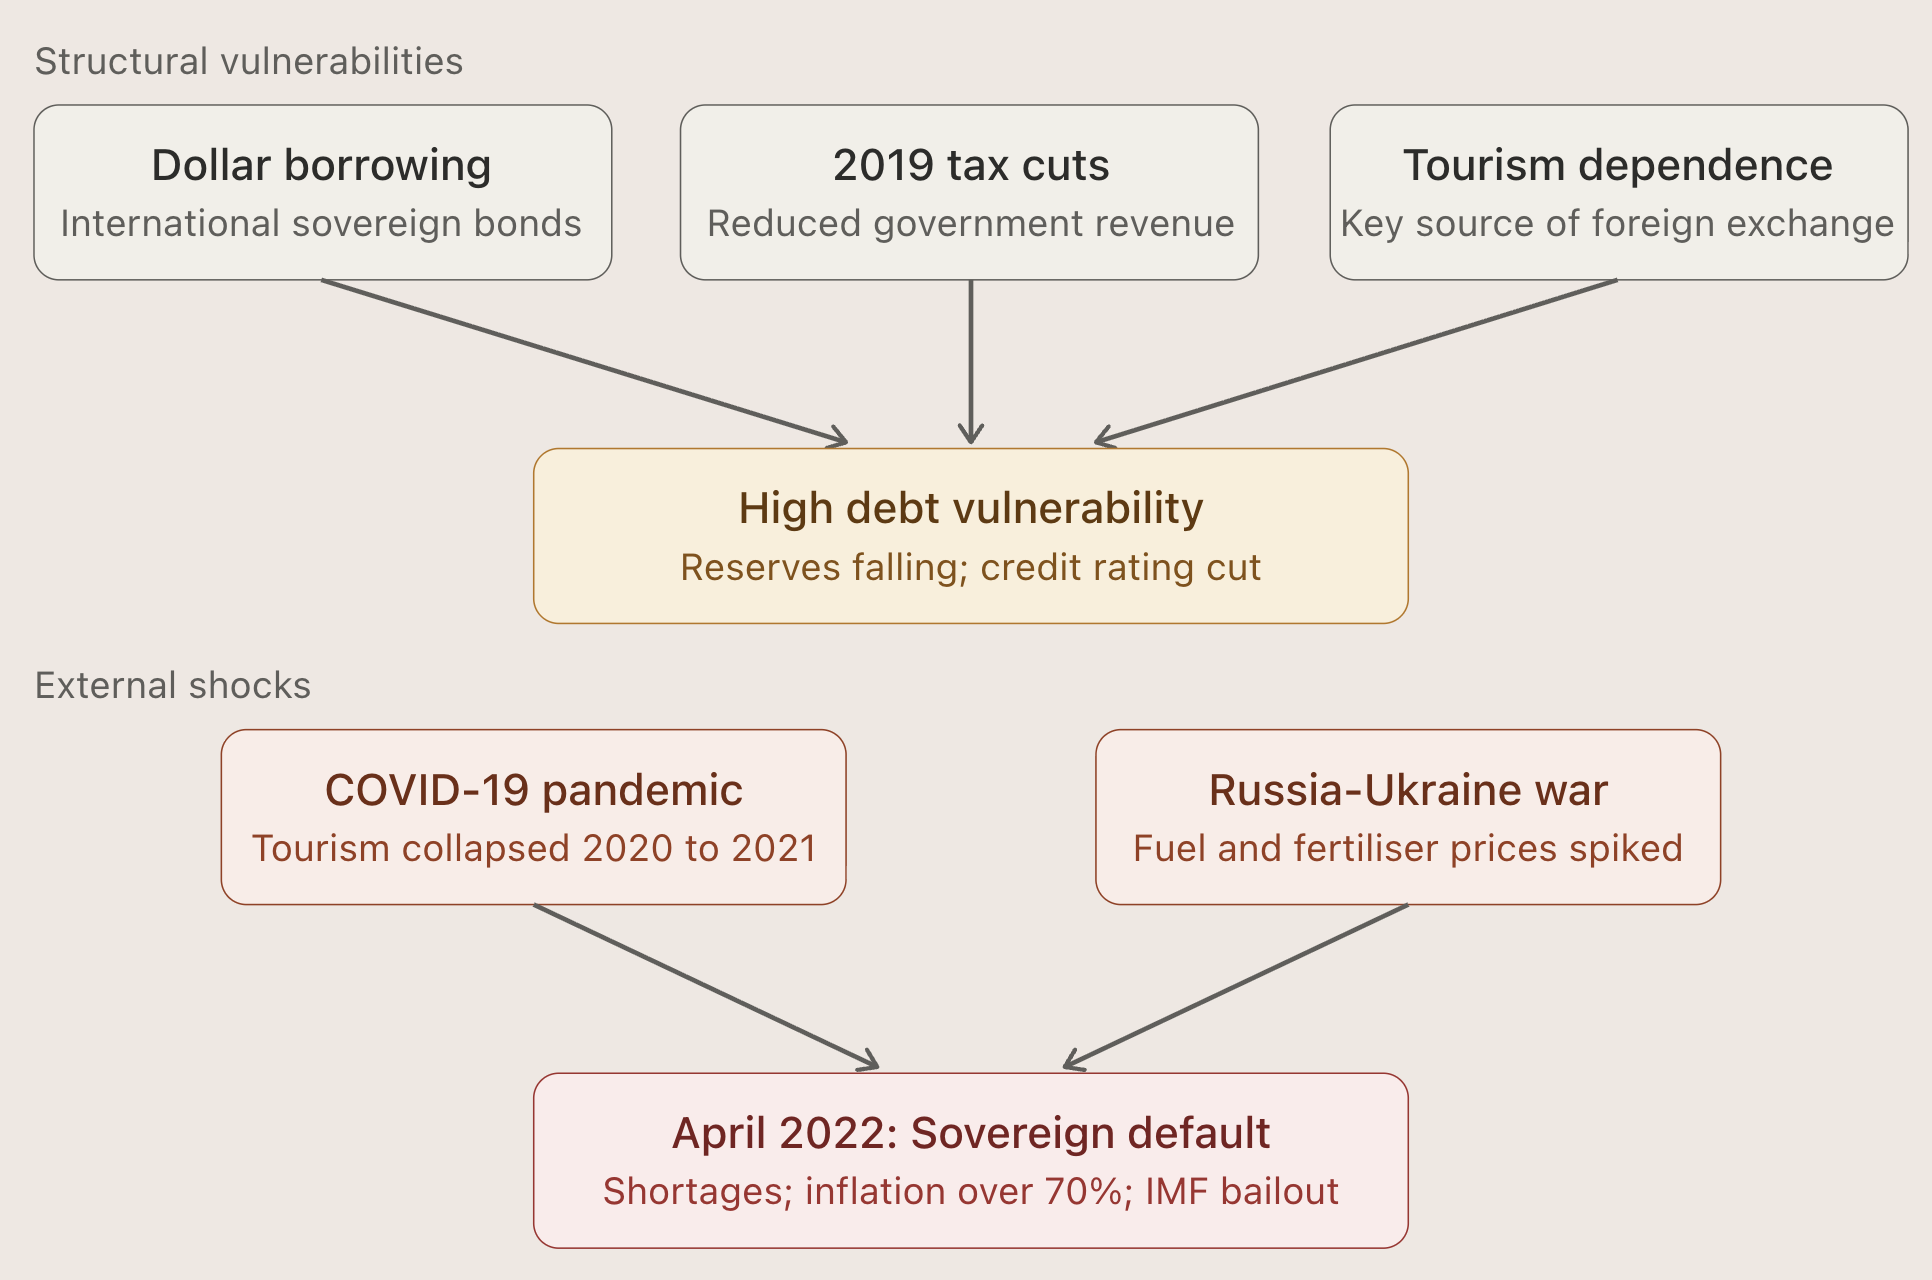
After the end of its civil war in 2009, Sri Lanka pursued ambitious infrastructure-led development funded substantially through external borrowing — including international sovereign bonds, loans from China for infrastructure projects, and multilateral lending. Debt-to-GDP rose sharply through the 2010s.
Causes of the crisis
- Heavy reliance on foreign-currency external debt, particularly US dollar-denominated international sovereign bonds
- 2019 tax cuts that reduced government revenue and widened fiscal deficits
- COVID-19 collapse of tourism in 2020–21 — Sri Lanka's largest source of foreign exchange
- 2022 Russian invasion of Ukraine raised global fuel and fertiliser prices, draining reserves
- Loss of access to international capital markets as credit ratings fell
Outcomes
- April 2022: Sri Lanka announced its first sovereign default in its history
- Severe shortages of fuel, food and medicine triggered mass protests and the resignation of the President
- Inflation peaked above 70% in 2022; the rupee lost more than half its value against the dollar
- IMF bailout agreement of approximately US$3 billion approved in March 2023, requiring tax increases and spending reforms
- Debt restructuring with bilateral creditors (including China and India) and private bondholders followed
- Poverty rates rose sharply; long-term economic damage will take years to reverse
The Sri Lankan case illustrates how external debt vulnerability can compound rapidly when external shocks combine with weak domestic fiscal management.
Exam Hint The strongest analytical move is to distinguish FDI from external debt clearly — FDI involves risk-sharing with the foreign investor; debt creates fixed repayment obligations regardless of project success. This distinction is the foundation of higher-mark answers comparing the two flows.
For FDI evaluation, the two strongest critical points are profit repatriation (which reduces long-run host benefits) and limited local linkages (which reduces the multiplier effect when MNCs import most inputs).
For debt evaluation, distinguish between debt for productive investment (supports growth if returns exceed interest costs) and debt for consumption or non-productive uses (creates obligations without revenue to service them). The currency denomination matters too — foreign-currency debt carries exchange rate risk that local-currency debt does not.
Was this revision note helpful?