Profit Statements (Cambridge International A-Level Accounting)
Profit statements using absorption costing
Spec point — how to prepare costing and profit statements using absorption costing
What are profit statements?
- Profit statements show the profit or loss made from selling a product/service
How do I prepare a profit statement using absorption costing?
-
STEP 1 Calculate the sales revenue
- Selling price per unit × number of units sold
-
STEP 2 Calculate the cost of sales
-
Start with opening inventory
-
Add production cost
- Including the fixed costs
-
Subtract closing inventory
-
-
STEP 3 Calculate the gross profit
- Sales revenue - cost of sales
-
STEP 4 Adjust for the under-absorption or over-absorption to find the profit or loss
- Add overheads over-absorbed
- Subtract overheads under-absorbed
-
STEP 5 Subtract any other non-production costs to calculate the profit or loss
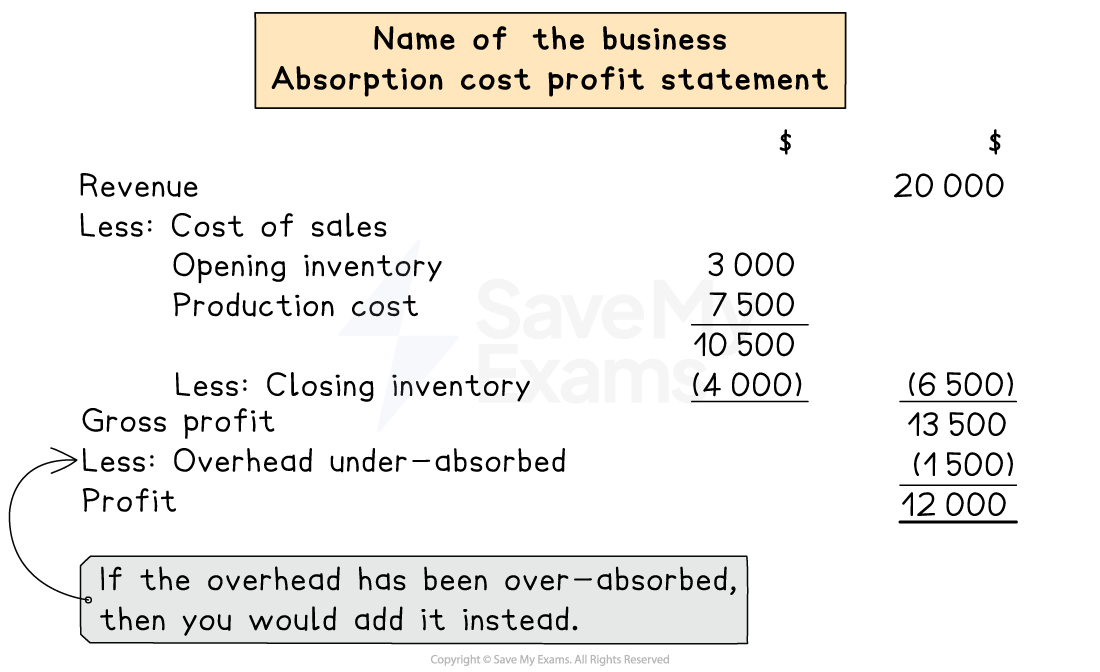
Layout of a profit statement using absorption costing
Worked Example Jane manufactures a single product. She uses a system of absorption costing.
The following budgeted data is available for one unit of the product.
$ Selling price 14 Direct materials 4 Direct labour 3 Budgeted production: 20 000 units per month
Budgeted fixed overheads: $23 000 per month
On 1 August, Jane held 2 000 units.
The following actual results are available.
Sales: 12 000 units
Production: 18 000 units
Fixed overheads: $25 000
Prepare the profit statement for the month of August to calculate the profit or loss.
Answer:
Sales revenue $14 × 12 000 = $168 000
Production cost
- Direct materials $4 × 18 000 = $72 000
- Direct labour $3 × 18 000 = $54 000
- Fixed overheads 25 000 ÷ 20 000 = $1.25 per unit $1.25 × 18 000 = $22 500
- Total
$72 000 + $54 000 + $22 500 = $148 500
Opening inventory ($4 + $3 + $1.25) × 2 000 = $16 500
Closing inventory Opening inventory + Production - Sales = 2 000 + 18 000 - 12 000 = 8 000 units ($4 + $3 + $1.25) × 8 000 = $66 000
Calculate the overheads that are over-absorbed or under-absorbed
- Actual overheads - Overheads absorbed
25 000 - 22 500 = 2 500 under-absorbed
Profit statement for the month of August
$ Revenue 168 000 Cost of sales: Opening inventory 16 500 Production costs 148 500 Less: Closing inventory (66 000) (99 000) Gross profit 69 000 Less: Overheads under-absorbed (2 500) Profit for the month 66 500 Final answer: Profit for August is $66 500
Was this revision note helpful?