Statement of Changes in Equity (Cambridge International IGCSE Accounting)
Statements of changes in equity
What is a statement of changes in equity?
-
A statement of changes in equity is a statement showing how the equity of a limited company has changed over a year
-
It shows the changes to:
- The ordinary share capital
- The non-redeemable preference share capital
- The retained earnings
- The general reserve
-
It shows how the profits are used
-
Some of the profits will be distributed to the shareholders as dividends
-
The remaining profits are carried forward to the next financial year as retained earnings
- Some of the retained earnings might be transferred to the general reserve
-
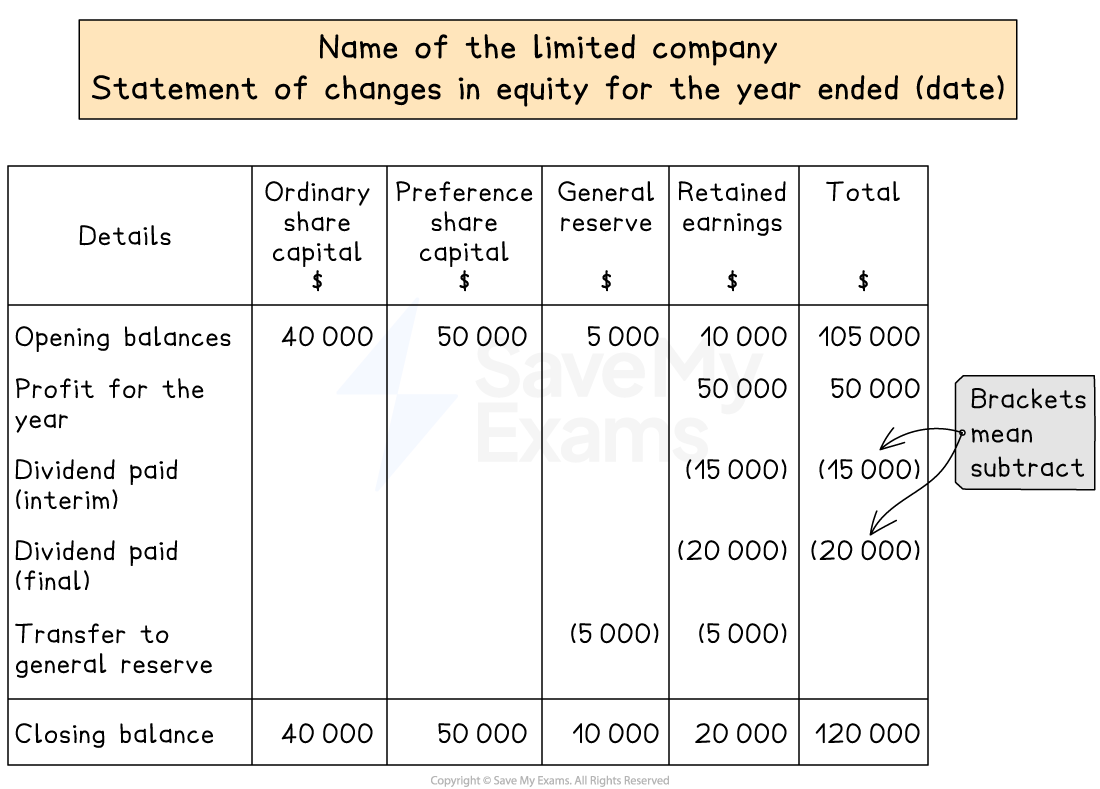
Layout of a statement of changes in equity
What are the reasons for the changes in the value of the total equity?
-
The equity of the limited company is likely to change due to the following
- The profit for the year is added to the retained earnings
- The profit is distributed or paid to shareholders in the form of interim and final dividends
- Some of the profit for the year is transferred to the general reserve
How are dividends treated on the statement of changes in equity?
-
Shareholders get a share or portion of the profits as dividends
-
The statement of changes in equity shows the dividends paid to shareholders during the year for any ordinary shares and non-redeemable preference shares
- Dividends that are paid halfway through the year are known as interim dividends
- Dividends that are paid at the end of the year are known as final dividends
-
Dividends proposed by the directors to be paid are not to be included in the statement of changes in equity until the amount is paid
Are redeemable preference shares included on the statement of changes in equity?
-
No information about redeemable preference shares is stated on the statement of changes in equity
- They are a liability so they are included on the statement of financial position
- Payment of their dividends is a finance cost and is included on the statement of profit or loss
Worked Example On 1 April 2023, P and Q Limited supplied the following information:
- In total, there were 800 000 ordinary shares of $0.75 each
- In total, there were 400 000 5% redeemable preference shares of $1 each
- The balance of the general reserve was $62 000
- The retained earnings amounted to $55 000
On 31 March 2024, P and Q Limited supplied the following information:
- The profit from operations for the year ended 31 March 2024 was $90 000
- Half of the preference share dividends were paid on 1 October 2023 and the rest were outstanding at 31 March 2024
- There were no other finance costs apart from the preference share dividends
- On 1 January 2024, an interim dividend of $32 000 was paid
- On 31 March 2024, $12 000 was transferred from the retained earnings to the general reserve
- On 31 March 2024, the directors proposed the payment of an ordinary share dividend of 10%
Prepare the statement of changes in equity for the year ended 31 March 2024 for P and Q Limited.
Answer:
Identify the key information given on 1 April 2023
In total, there were 800 000 ordinary shares of $0.75 each
- Calculate the ordinary share capital on 1 April 2023 by multiplying the number of shares by the price of a share
Ordinary share capital: 800 000 × $0.75 = $600 000
In total, there were 400 000 5% redeemable preference shares of $1 each
- Redeemable preference shares are liabilities so they do not appear on the statement of changes in equity
The balance of the general reserve was $62 000
- This is the opening balance on the statement of changes in equity
The retained earnings amounted to $55 000
- This is the opening balance on the statement of changes in equity
Identify the key information given on 31 March 2024.
The profit from operations for the year ended 31 March 2024 was $90 000
- This is before the finance costs are subtracted
Half of the preference share dividends were paid on 1 October 2023 and the rest were outstanding at 31 March 2024
The full dividend is a finance cost for the year as it was owed that year
- Regardless of how much of it was actually paid
Calculate the dividends by multiplying the percentage by the number of shares and then multiply by the value of a share
5% × 400 000 × $1 = $20 000
There were no other finance costs apart from the preference share dividends
Subtract the dividends for redeemable preference shares from the profit from operations
- This will increase the retained earnings
Profit for the year: $90 000 - $20 000 = $70 000
On 1 January 2024, an interim dividend of $32 000 for the ordinary shares was paid
This will decrease the retained earnings
- The interim dividend was paid in the current year so it is entered on the statement of changes in equity
On 31 March 2024, $12 000 was transferred from the retained earnings to the general reserve
- This will decrease the retained earnings but increase the general reserve
On 31 March 2024, the directors proposed the payment of an ordinary share dividend of 10%
- Any proposed dividend at the end of the year that remains unpaid, should not be included on the statement of changes in equity
Complete the statement of changes in equity using the required format
- Remember to total up rows and columns
- Put brackets around values if they are to be subtracted.
Final answer: P and Q Limited
Final answer: Statement of Changes in Equity for the year ended 31 March 2024Final answer: Ordinary share capital
Final answer: $**Final answer: General Reserve
Final answer: $Final answer: Retained Earnings
Final answer:****$Final answer: Total
Final answer: **$Final answer: On 1 April 2023 Final answer: 600 000 Final answer: 62 000 Final answer: 55 000 Final answer: 717 000 Final answer: Profit for the year Final answer: 70 000 Final answer: 70 000 Final answer: Dividend paid Final answer: (32 000) Final answer: (32 000) Final answer: Transfer to general reserve Final answer: 12 000 Final answer: (12 000) Final answer: On 31 March 2024 Final answer: 600 000 Final answer: 74 000 Final answer: 81 000 Final answer: 755 000
Was this revision note helpful?
Build on this topic