Statement of Financial Position (Cambridge International IGCSE Accounting)
Statements of financial position for sole traders
Statement of financial position for sole traders
What is the statement of financial position?
-
The statement of financial position is one of the financial statements of a sole trader business
-
It shows the position of the business in terms of its assets, liabilities and capital *at a particular date
- It provides a snapshot of the business on a particular date
-
The statement of financial position is split into two halves
- The assets are listed in the first half
- The capital and liabilities are listed in the second half
- The totals for each half will be equal
-
The statement of financial position is prepared in exactly the same way for a trading and a service business
-
The figures used to prepare the statement of financial position will be taken from the trial balance or list of balances
- Additional information will be given after the trial balance
- This is where the valuation of the closing inventory is given
-
The statement of the financial position is prepared after the income statement
- The profit or loss for the year will increase or decrease the capital
-
The statement of financial position is not part of the double entry system
- The balances of the accounts are stated on the statement
- They are not transferred to the statement
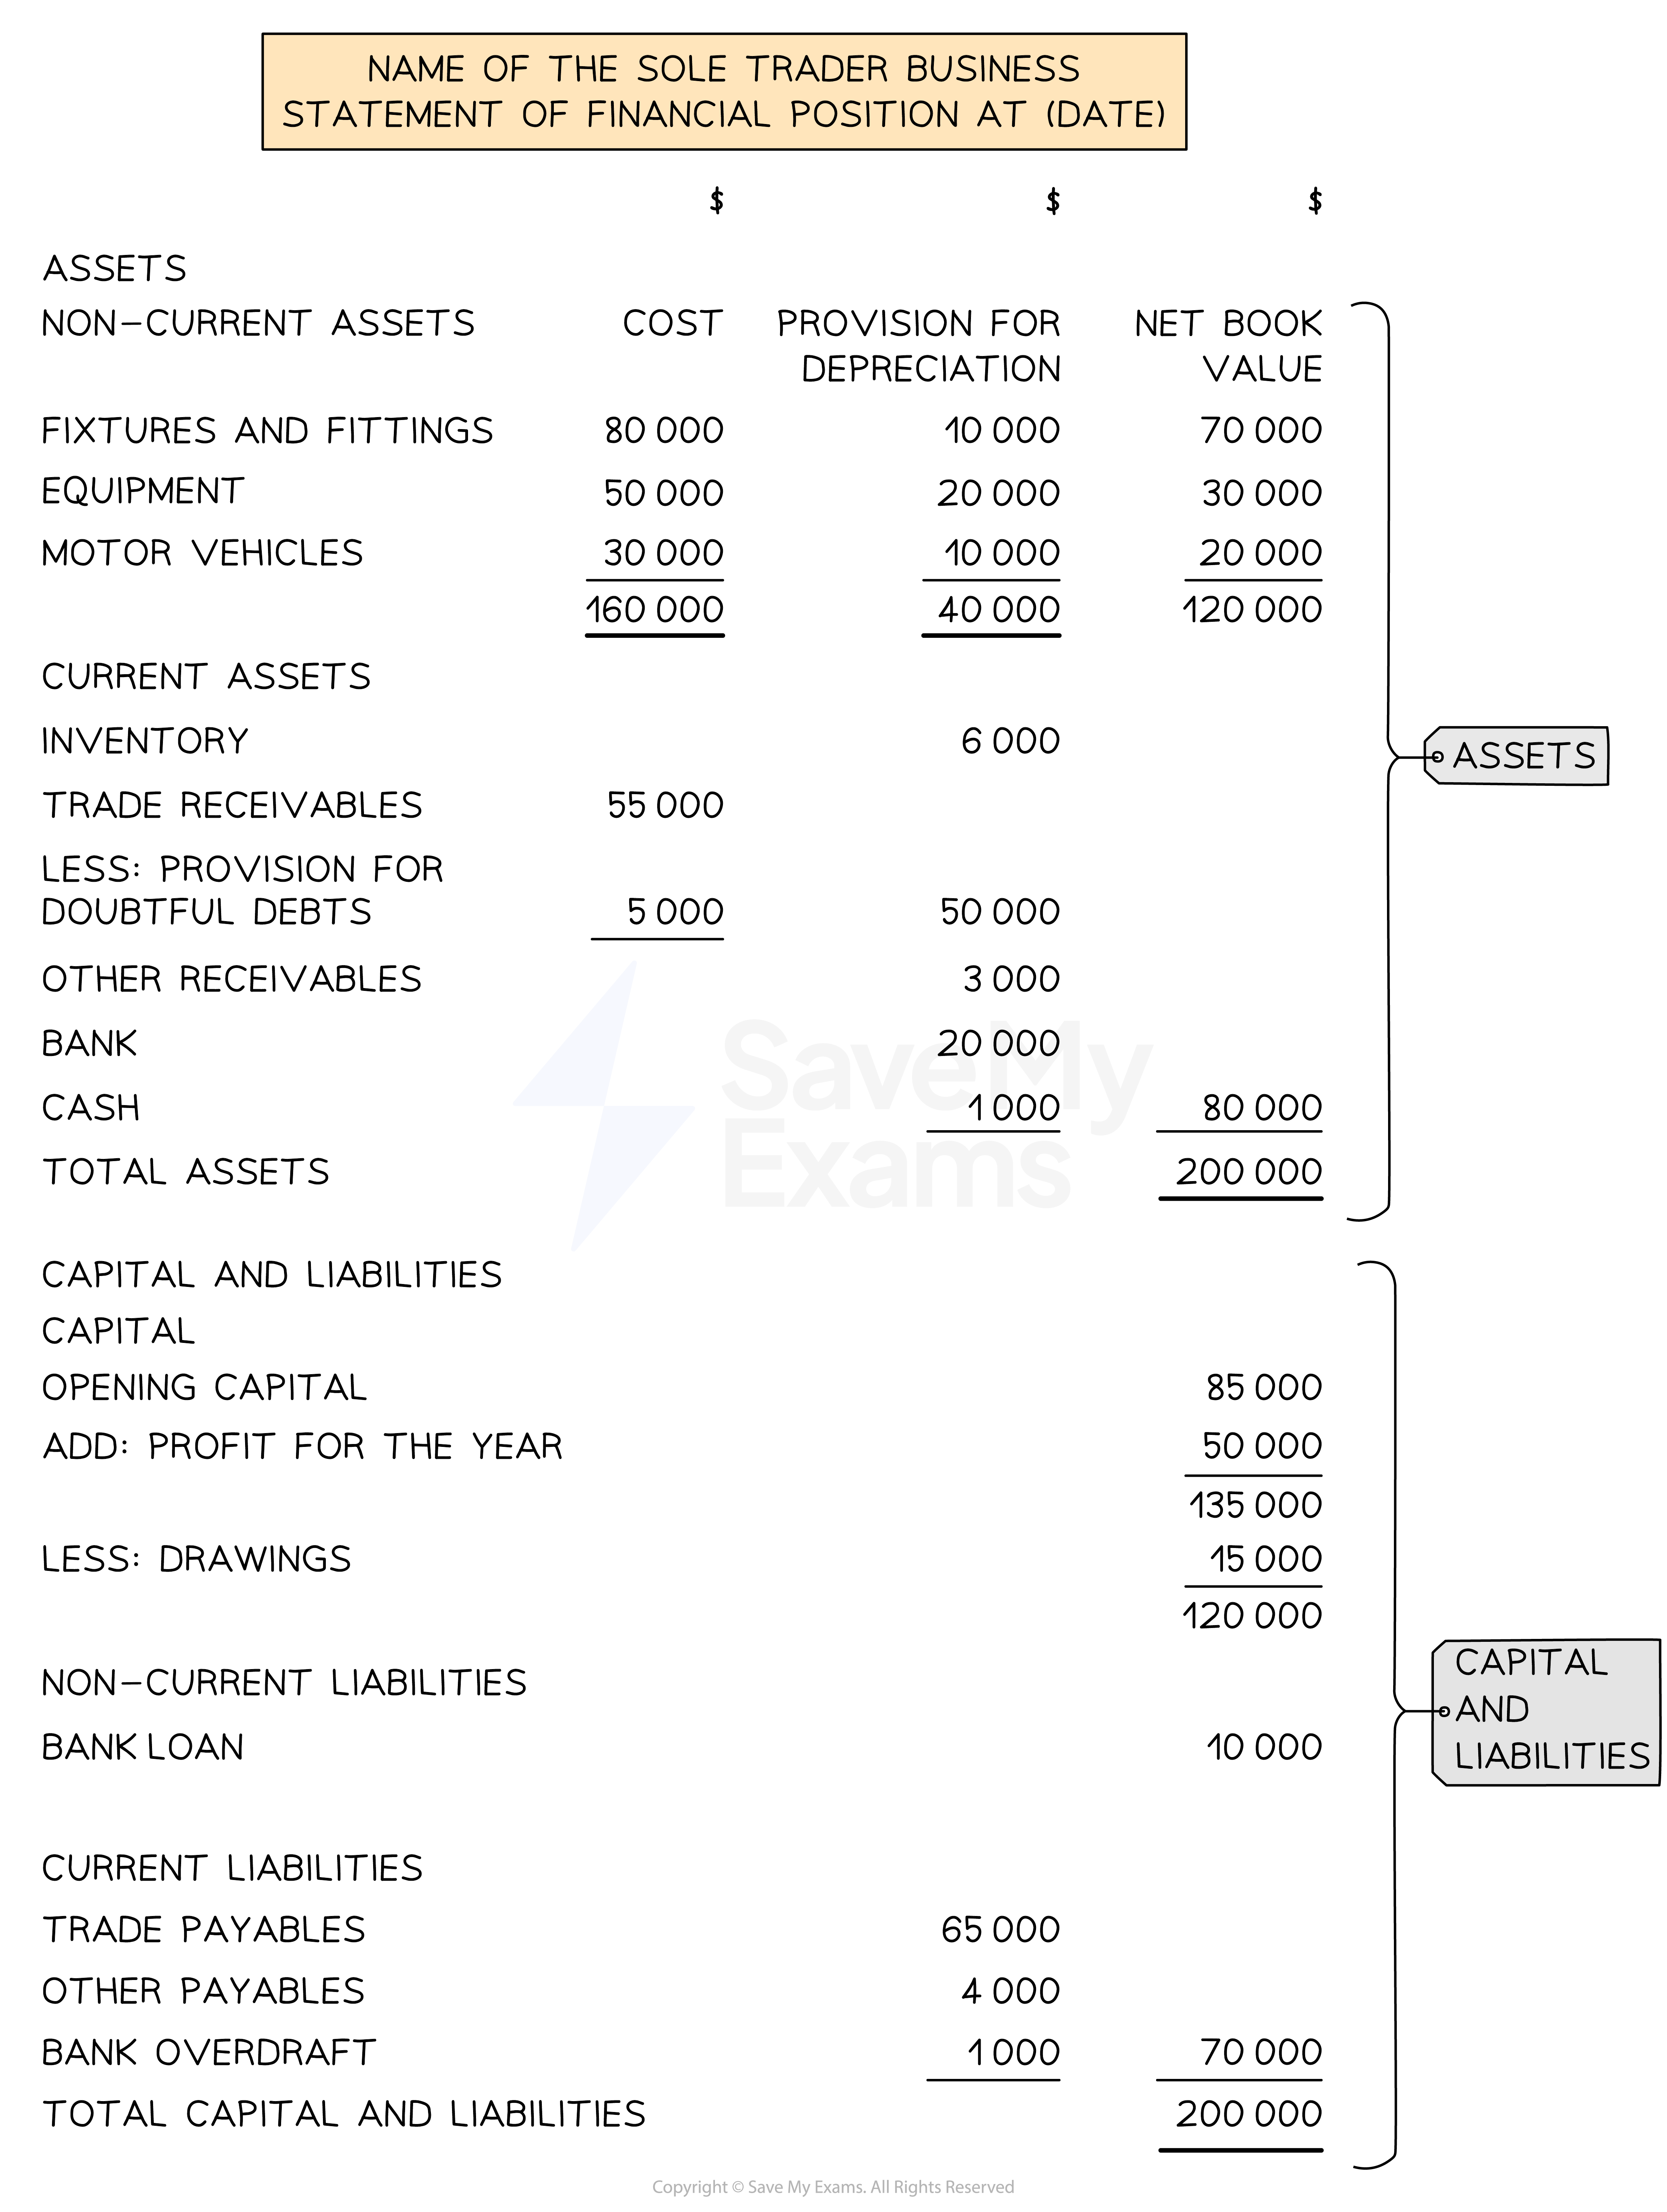
Layout of a statement of financial position
Exam Hint On a trial balance, both bank and bank overdraft will be listed as "bank". If it is a debit balance, then there is money in the bank, and it is an asset. If it is a credit balance, then money is owed to the bank (it is a bank overdraft), and it is a liability.
What is the layout for the assets section?
-
The non-current assets are listed first
-
Any intangible non-current assets are listed first
- These are the non-current assets that do not have a physical form but still add value to the business
- Such as intellectual property, goodwill and brand names
-
Followed by tangible non-current assets
- These are the non-current assets that have a physical form and are obtained to help the business generate profit rather than for resale
- Such as equipment, machinery, motor vehicles, land and buildings etc
-
-
Three values are stated for each non-current asset in separate columns in the following order:
- Cost
- Provision for depreciation
- Net book value
-
The total for each column is calculated
- The total for the net book value column is the total value for the non-current assets
-
The current assets are listed after the non-current assets
-
The values for the current assets are listed in the middle column
- If there is a provision for doubtful debt then the far left column is used to subtract its balance from the trade receivables
- The total is put in the far right column
-
The total assets value is found by adding the total non-current assets and the total current assets
-
It is conventional to list the assets within each section in order of their liquidity
- Starting with the least liquid assets
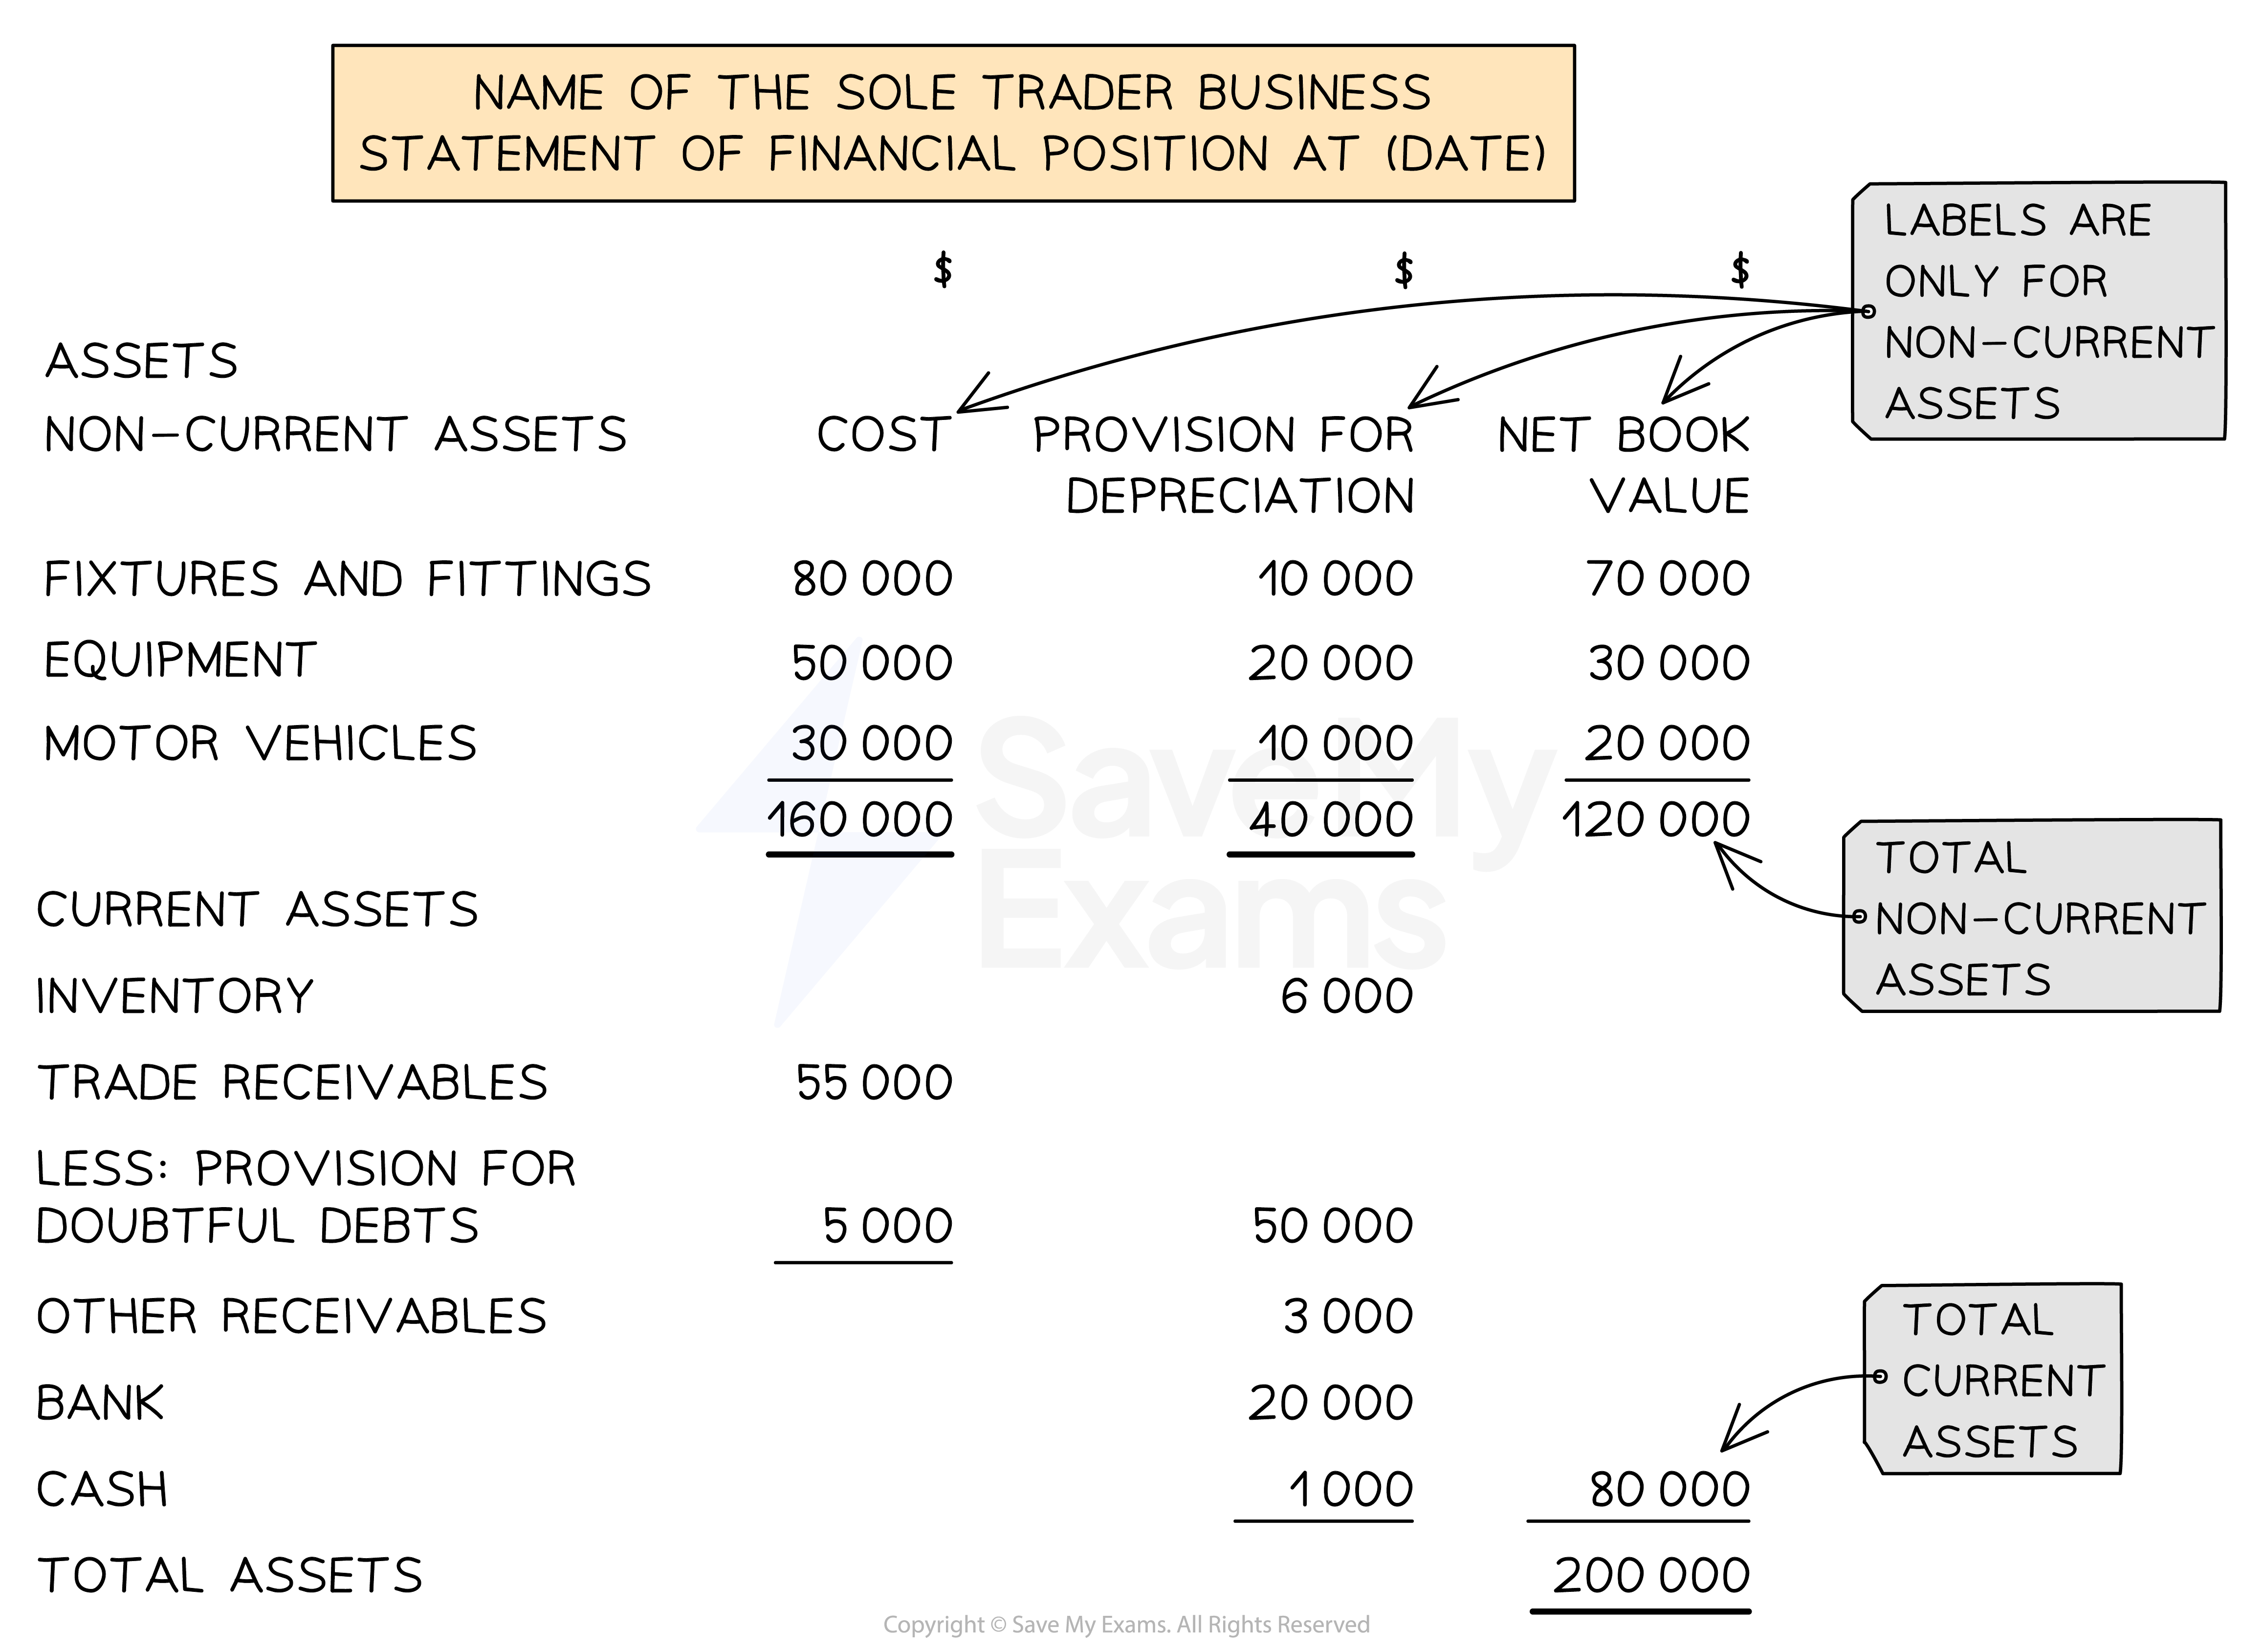
Layout of the assets section of the statement of financial position
Exam Hint For the inventory value, make sure you use the value of the closing inventory. A service business might not have inventory. For example, a taxi driver will not have any inventory.
How do I complete the capital and liabilities section?
-
Firstly, calculate the capital in the far right column
- Start with the opening capital from the beginning of the financial year
- Add (or subtract) the profit (or loss) for the year
- Subtract any drawings
- This gives the capital at that date
-
Secondly, list the non-current liabilities
- If there is just one item then put it in the far right column
- Otherwise, list them in the middle column and put the total in the far right column
-
Thirdly, list the current liabilities
- List them in the middle column and put the total in the far right column
-
Finally, calculate the total capital and liabilities by adding together:
- The capital
- The total non-current liabilities
- The total current liabilities
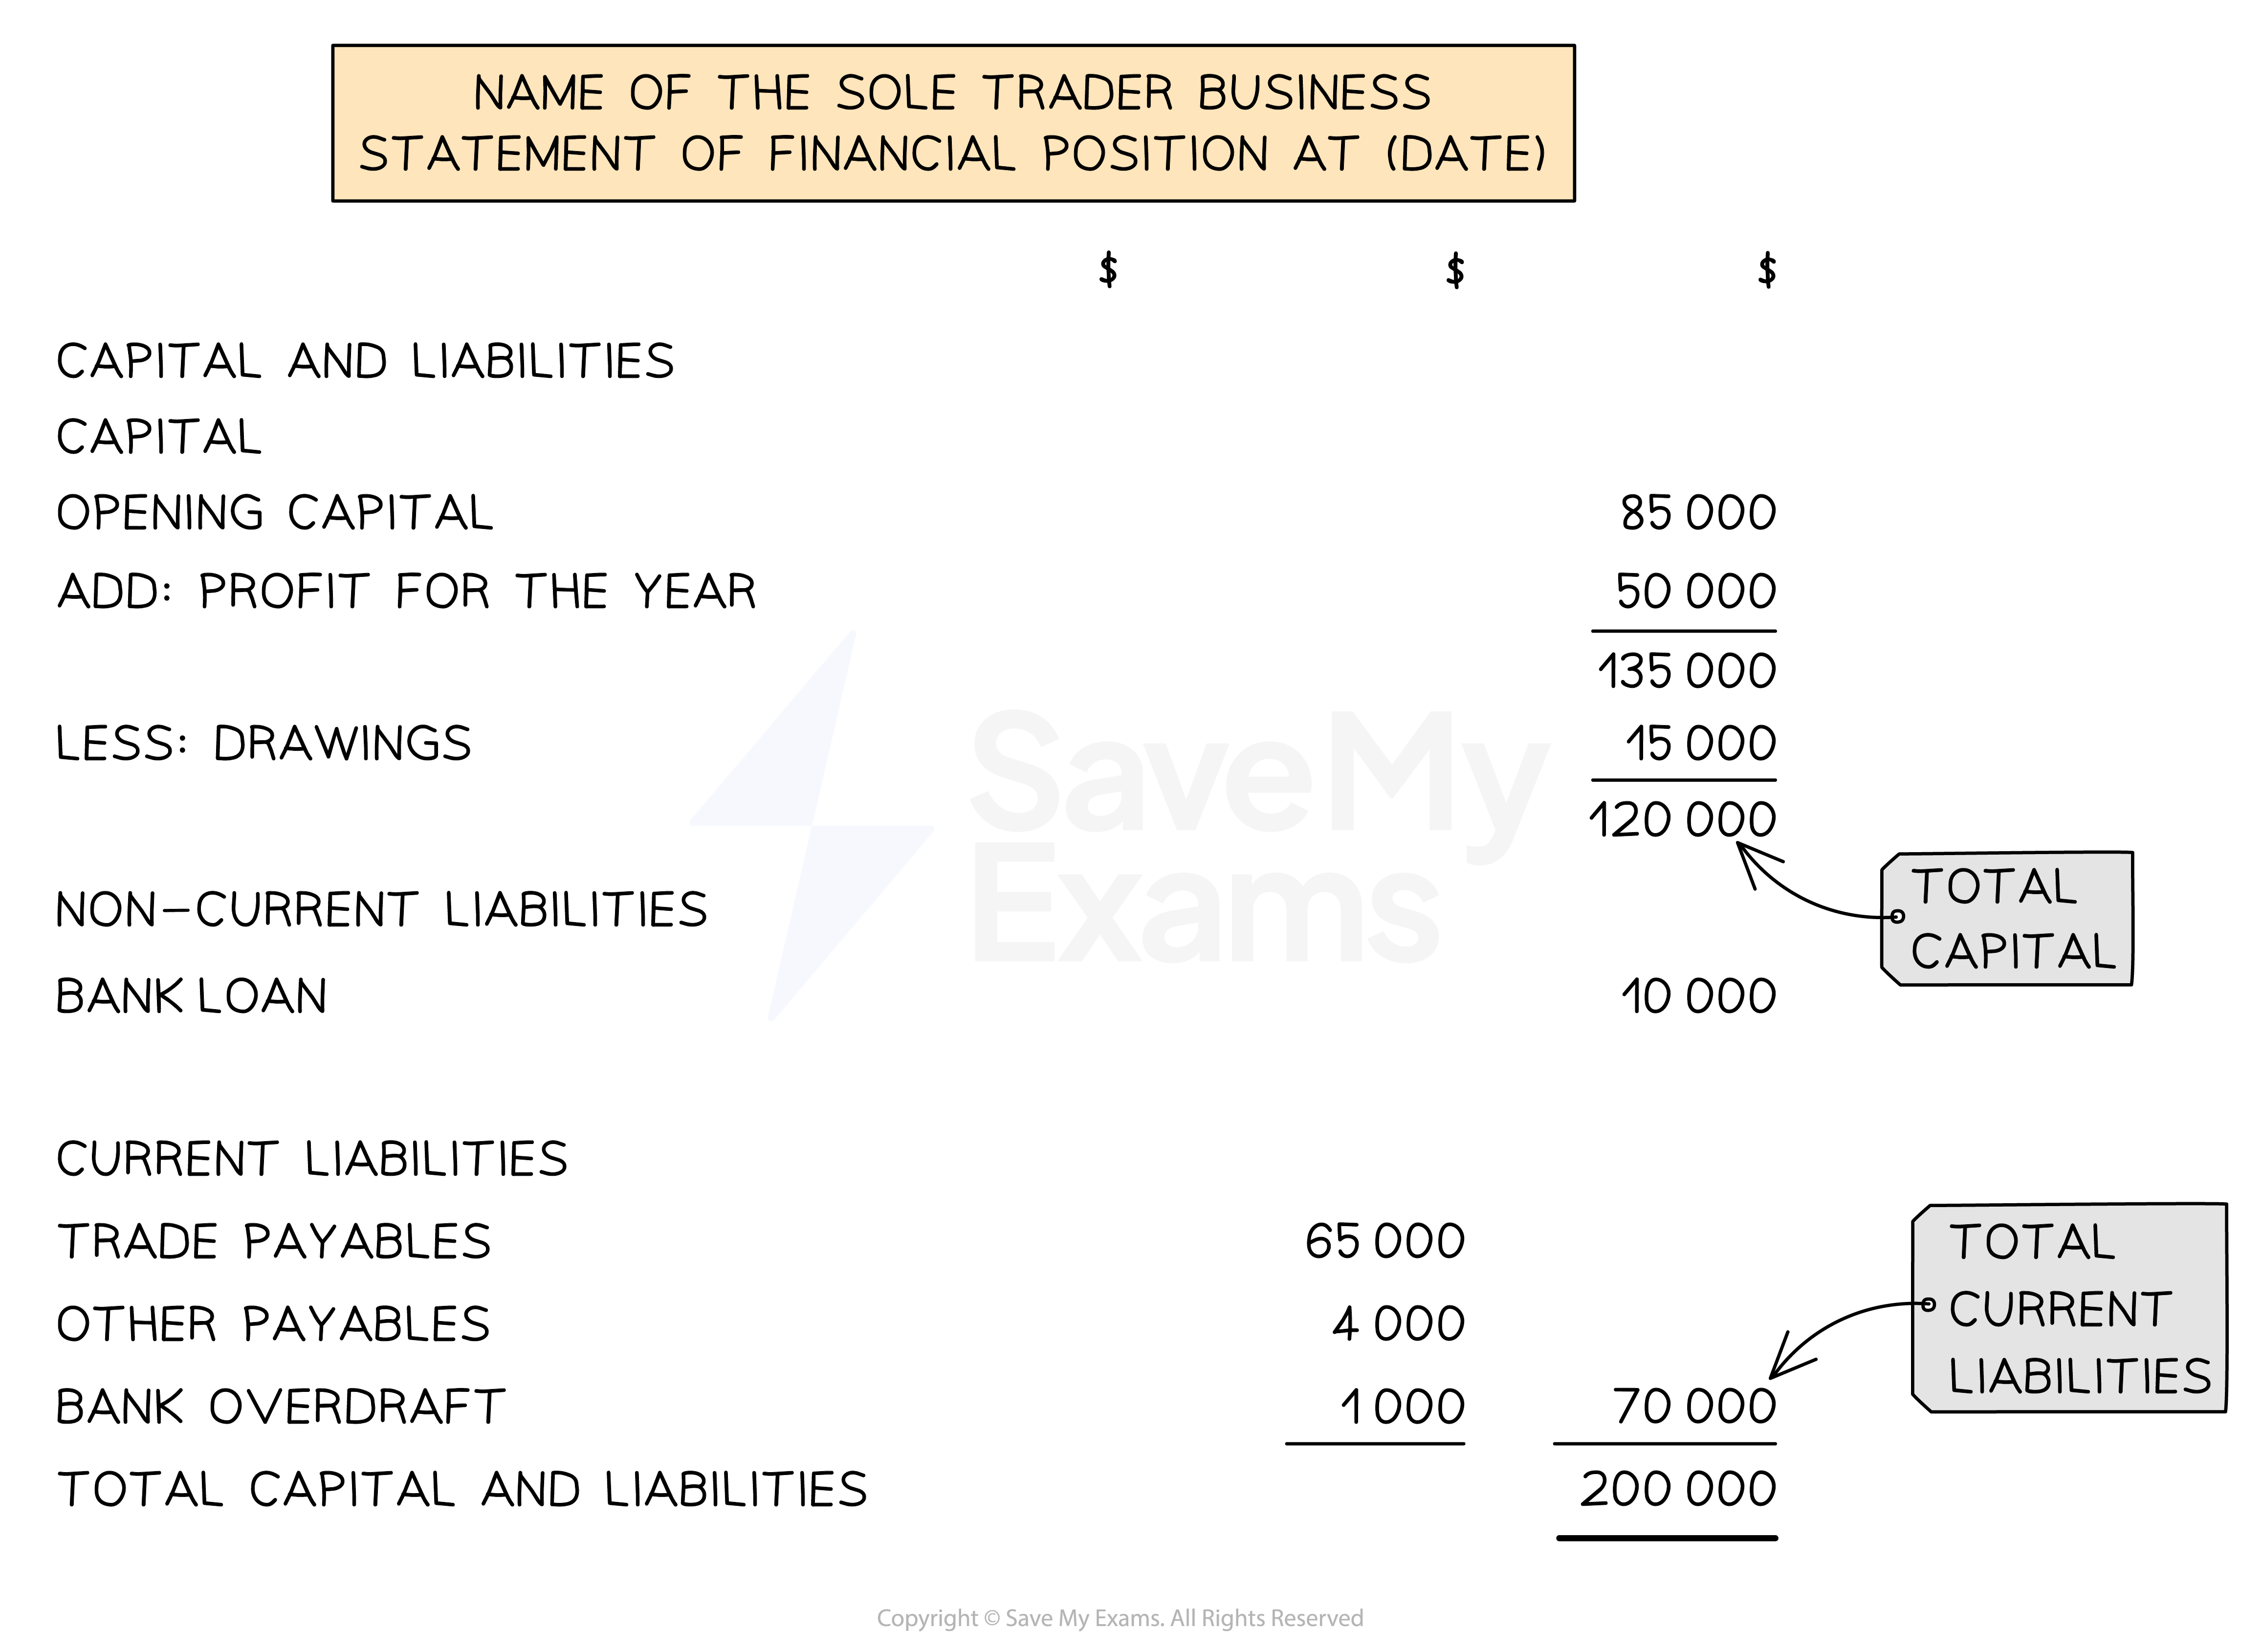
Layout of the capital and liabilities section of the statement of financial position
Exam Hint If you are given the information in a trial balance, identify the items that would appear on the statement of financial position. You might find it helpful to annotate with SoFP to differentiate from those which would appear on the income statement.
Worked Example The following trial balance has been extracted by the book-keeper of Bilal Aba at 31 December 2023.
Debit
$**Credit
$Trade receivables 73 217 Trade payables 19 745 Capital at 1 January 2023 58 466 Bank 550 Cash 400 Bank loan 10 000 Loan interest 500 Rent and rates 4 862 Salaries 33 872 Machinery 8 000 Drawings 12 715 Purchases 141 195 Revenue (Sales) 205 471 Inventory at 1 January 2023 19 471 294 232 294 232 Additional information:
- Inventory at 31 December 2023 is valued at $4 060
- The machinery was purchased during the year and the depreciation charge is $600
- The profit for the year, after including depreciation, is $9 031
Prepare a statement of financial position for Bilal Aba at 31 December 2023.
Answer:
Identify which items appear on the statement of financial position by labelling them as SoFP
Add extra rows for
- the closing inventory
- provision for depreciation
- and profit for the year
Debit
$Credit
$Statement of financial position? Trade receivables 73 217 SoFP Trade payables 19 745 SoFP Capital at 1 January 2023 58 466 SoFP Bank 550 SoFP Cash 400 SoFP 5 year loan 10 000 SoFP Loan interest 500 Rent and rates 4 862 Salaries 33 872 Machinery 8 000 SoFP Drawings 12 715 SoFP Purchases 141 195 Revenue (Sales) 205 471 Inventory at 1 January 2023 19 471 294 232 294 232 Inventory at 31 December 2023 4 060 SoFP Provision for depreciation of machinery 600 SoFP Profit for the year 9 031 SoFP Complete the statement of financial position.
Assets
- Non-current assets
- Current assets
Capital and liabilities
- Capital
- Non-current liabilities
- Current liabilities
Note that the bank has a credit balance so this means it is overdrawn
Final answer: Bilal Aba
Final answer:** Statement of Financial Position at 31 December 2023 **Final answer:****$ Final answer: $ Final answer: $ Final answer: Assets Final answer: Non-current assets Final answer: Cost Final answer: Provision for depreciation Final answer: Net book value Final answer: Machinery Final answer: 8 000 Final answer: 600 Final answer: 7 400 Final answer: Current assets Final answer: Inventory Final answer: 4 060 Final answer: Trade receivables Final answer: 73 217 Final answer: Cash Final answer: 400 Final answer: 77 677 Final answer: Total assets Final answer: 85 077 Final answer: Capital and liabilities Final answer: Capital Final answer: Opening capital Final answer:** 58 466 Final answer: Profit for the year Final answer: 9 031 Final answer: 67 497 Final answer: Less: Drawings Final answer: 12 715 Final answer: 54 782 Final answer: Non-current liabilities Final answer: Loan Final answer: 10 000 Final answer: Current liabilities Final answer: Trade payables Final answer: 19 745 Final answer: Bank overdraft Final answer: 550 Final answer: 20 295 Final answer: Total capital and liabilities Final answer: 85 077
Was this revision note helpful?
Build on this topic