Realisation Account (Cambridge International A-Level Accounting)
Spec point — how to prepare a realisation account
Realisation account
What is a realisation account?
-
A realisation account is used when a business (usually a partnership) is being dissolved, sold, or acquired by another business
-
It is a temporary account
- It is opened only when the business is closing
-
It is used to close the accounting books of the old partnership and calculate the final profit or loss on realisation
- This is the overall net gain or loss made from selling off or dissolving the business
-
The resulting profit or loss is then transferred to the partners' capital accounts in their profit-sharing ratio
- The realisation account is then closed
-
It is very similar to a revaluation account
How do I prepare a realisation account?
-
STEP 1 Enter the non-current assets into the realisation account
-
Non-The current net book value is entered on the debit side
-
The proceeds from the sale of the assets is entered on the credit side
- This includes an agreed amount if a partner takes an asset for their personal use
-
-
STEP 2 Enter the current assets(apart from the bank balance) into the realisation account
- The current amount owed by customers is entered on the debit side
- The actual amount received is entered on the **credit **side
-
STEP 3 Enter the liabilities (apart from the bank overdraft)**** into the realisation account
- The current amount owed to suppliers is entered on the credit side
- The actual amount paid is entered on the debit side
-
STEP 4 Enter any additional amounts such as discounts or realisation costs
-
Expenses are entered on the debit side
- Such as discount allowed, realisation costs
-
Incomes are entered on the credit side
- Such as discount received
-
-
STEP 5 Find the balancing figure
- It is a net profit on realisation if it is on the debit side
- It is a net loss on realisation if it is on the credit side
-
STEP 6 Share the net profit or loss on realisation between the partners' capital accounts using the profit-sharing ratio
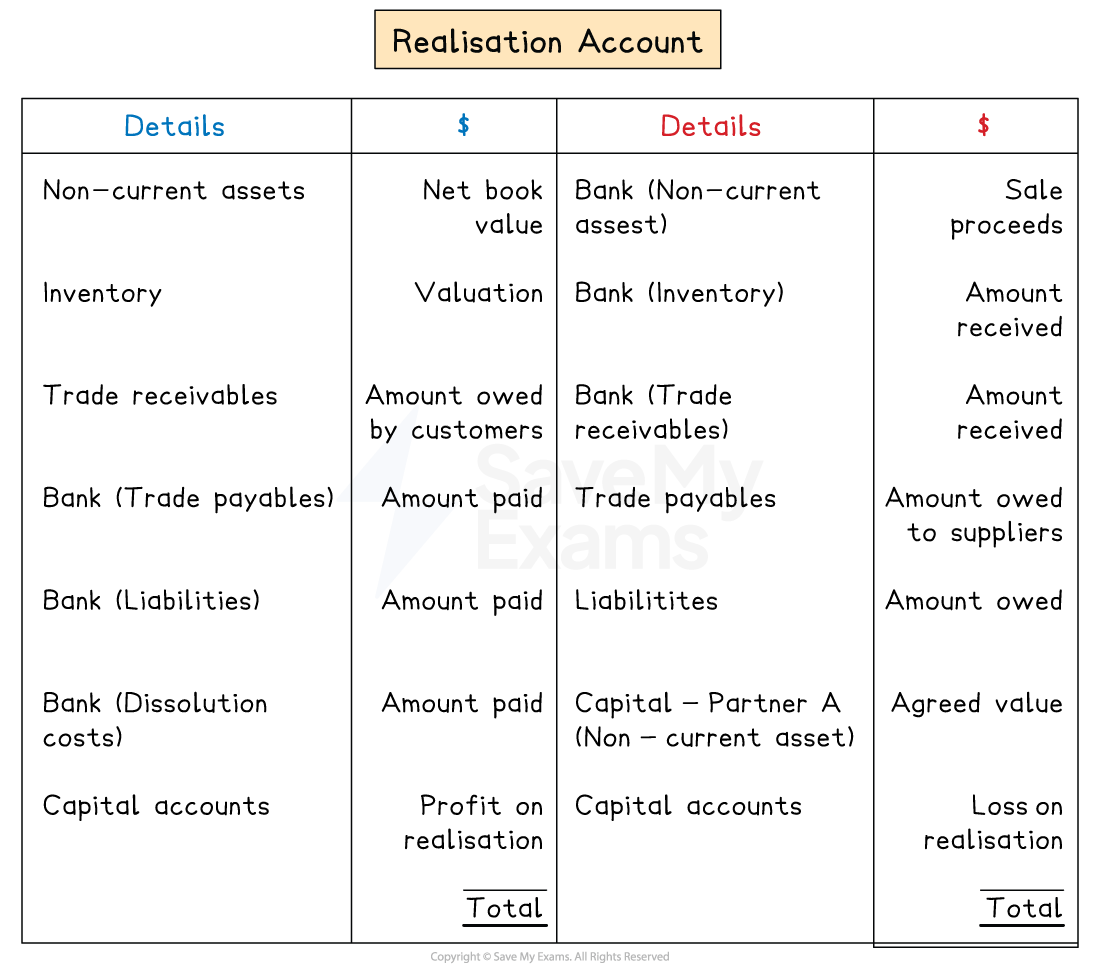
Layout of a realisation account
Exam Hint Remember, the bank balance or the bank overdraft is not entered into the realisation account.
If you struggle to remember what goes on which side, then consider the other side of the transaction.
For example, to remove a loan, a debit entry is made in its account. Therefore, the entry in the realisation account is on the credit side.
Worked Example Clark and Lois were in partnership sharing profits and losses in the ratio 3:2 respectively.
The statement of financial position at 31 December 2025 was as follows:
$ $ $ Assets Non-current assets 125 000 Current assets Inventory 37 000 Trade receivables 23 000 60 000 Total assets 185 000 Capital and liabilities Capital Clark Lois Total Capital accounts 80 000 60 000 140 000 Current accounts (1 000) 5 000 4 000 79 000 65 000 144 000 Non-current liabilities Bank loan 20 000 Current liabilities Bank overdraft 8 000 Trade payables 13 000 21 000 Total capital and liabilities 185 000 The partners agreed to dissolve the partnership on 31 December 2025.
The following transactions took place as part of the dissolution process.
- As part of his settlement, Clark took a vehicle with a net book value of $20 000.
- As part of her settlement, Lois took a vehicle with a net book value of $25 000.
- All remaining non-current assets were sold for $75 000.
- Inventory was sold for $29 000.
- Irrecoverable debts of $500 were written off and the remaining credit customer paid their balances in full.
- $22 500 was paid to clear the bank loan including early repayment charges.
- Trade payables were paid in full.
- Dissolution costs of $3 000 were paid.
Prepare the realisation account to record the dissolution of the partnership.
Answer:
Calculate the amount received from trade receivables
$23 000 - $500 = $22 500
Enter the amounts into the realisation account
- Find the balancing figure
$223 500 - $204 500 = $19 000
- Share the figure between Clark and Lois
$19 000 ÷ (3 + 2) = $3 800
Clark: 3 × $3 800 = $11 400
Lois: 2 × $3 800 = $7 600
$ $ Non-current assets 125 000 Capital - Clark (Vehicle) 20 000 Inventory 37 000 Capital - Lois (Vehicle) 25 000 Trade receivables 23 000 Bank (Non-current assets) 75 000 Bank (Bank loan) 22 500 Bank (Inventory) 29 000 Bank (Trade payables) 13 000 Bank (Trade receivables) 22 500 Dissolution costs 3 000 Bank loan 20 000 Trade payables 13 000 Capital - Clark (Loss on realisation) 11 400 Capital - Lois (Loss on realisation) 7 600 223 500 223 500
Was this revision note helpful?
Build on this topic