Statement of Cash Flows (Cambridge International A-Level Accounting)
Statements of cash flows
Spec point — how to prepare for a limited company in line with the relevant international accounting standards and legal requirements: – statement of cash flows
Statements of cash flows
What is a statement of cash flows?
-
A statement of cash flows shows the movement of cash and cash equivalents during the year
-
It separates the cash flows into three sections to show the cash from or used in these activities
- Cash flows from operating activities
- Cash flows from investing activities
- Cash flows from financing activities
-
Use "cash from" if the net cash for the activities is positive
-
Use "cash used in" if the net cash for the activities is negative
What are the uses of a statement of cash flows?
- To show the amount of money that has entered and left the business during a period
- To show why the profit for a period is different to the increase in cash
- To show sources of finance during a period
- To enable the directors to assess the liquidity of the business
- To enable stakeholders to see how well cash has been used
- To enable stakeholders to compare the year's cash flow with previous years or with other businesses
How do I prepare a statement of cash flows?
Cash flows from operating activities
-
Start with the profit from operations
- This is the profit before loan interest and tax
-
Make adjustments for non-cash items included in the calculation for the profit
- Add the depreciation charge for the year
- Add the loss on disposal of non-current assets
- **Subtract **the profit on disposal of non-current assets
-
Make adjustments for** changes in working capital**
-
Change in inventories
- Add if it is a decrease
- Subtract if it is an increase
-
Change in trade receivables
- Add if it is a decrease
- Subtract if it is an increase
-
Change in trade payables
- Add if it is an increase
- Subtract if it is a decrease
-
-
This gives the cash from or used in operations
-
Subtract the actual amount paid for interest and tax
-
This gives the net cash from or used in operating activities
Exam Hint It can be helpful to understand why changes to assets and liabilities are added or subtracted from the cash flows from operating activities.
A decrease to an asset is added to the cash flow because a part of its balance at the beginning of the year has been converted to cash. Whereas, a decrease to a liability is subtracted from the cash flow because the company has paid some of the balance off.
Cash flows from investing activities
-
Add the sale proceeds from the disposals of non-current assets
-
Subtract the **purchase **amounts of non-current assets
-
The net amount is the** net cash from or used in investing activities**
- It is usually net cash used in investing activities
Cash flows from financing activities
-
Add the amounts raised to finance the company
- Issue of share capital
- Money from new debentures or loans
-
Subtract the amounts paid to investors, lenders and shareholders
- Repayment of debentures or loans
- Dividends paid
-
The net amount is the net cash from or used in financing activities
Exam Hint A bonus issue raises no cash, so it is excluded from the cash flow statement. A rights issue raises cash, so the full amount received (nominal value + share premium) appears as a cash inflow under financing activities.
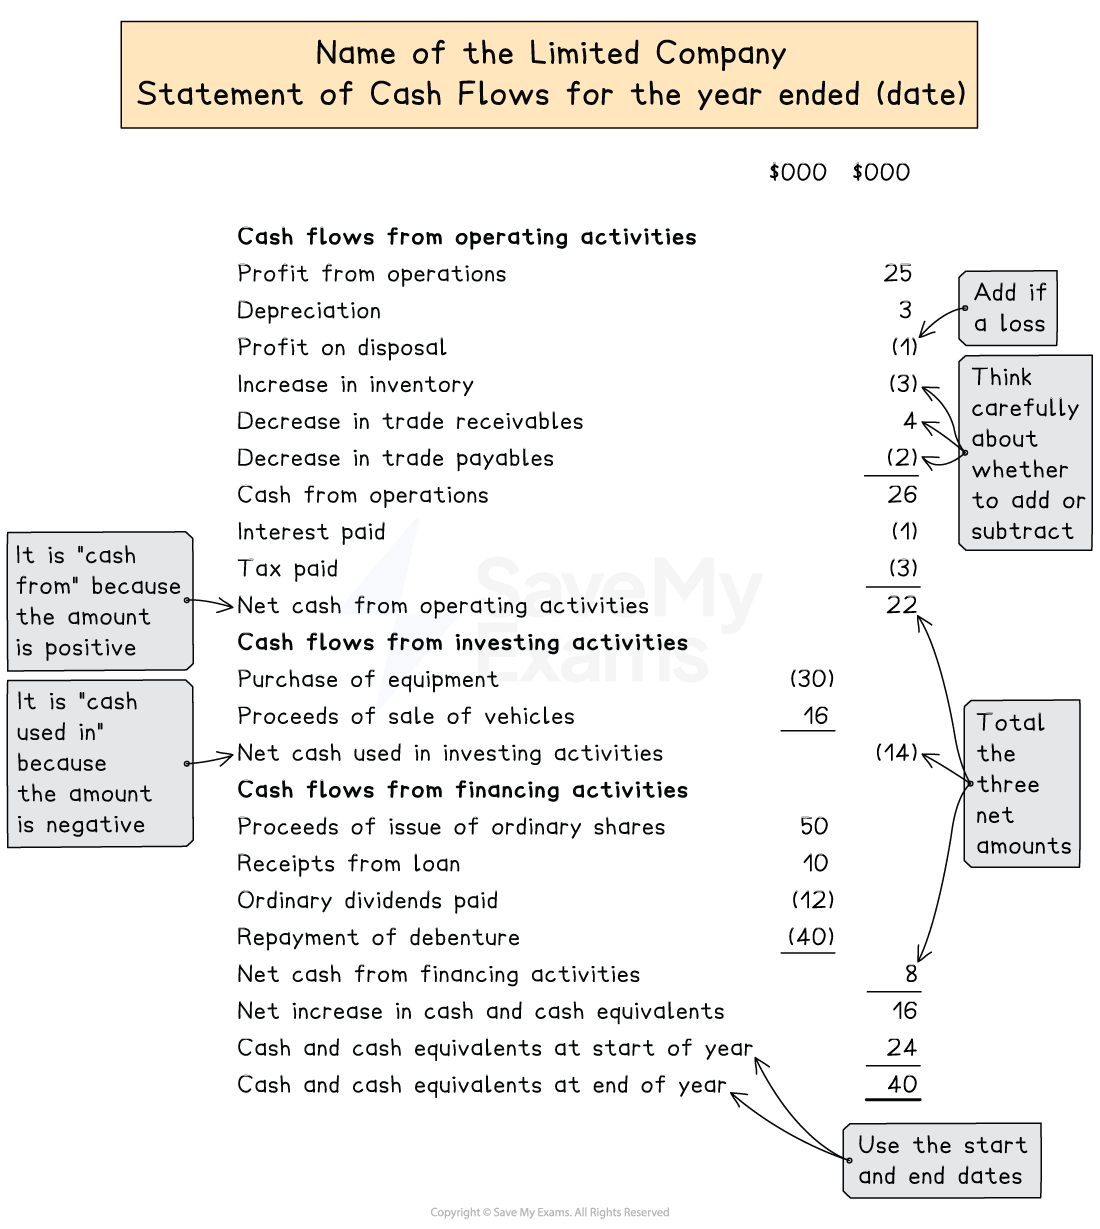
Layout of a statement of cash flows
How do I calculate the profit from operations?
-
You might be given the profit from operations in the question or you might be required to calculate it
-
You can calculate the profit or the loss for the year by looking at the change in equity
- Calculate the change in retained earnings
- Add back the dividends paid
- Add back any amounts of retained earnings that were transferred or used in a bonus issue of shares
-
You can then work backwards from the profit or loss to find the profit from operations
- Add back the amount due for finance costs for the year
- Add back the amount due for taxation for the year
Exam Hint The amounts due for interest and tax might not be the amounts that were actually paid. The amounts due are used to calculate the profit from operations. The amounts paid are used to calculate the net cash from operating activities.
Worked Example W plc's financial year ends on 31 December.
The following information for the year ended 31 December 2025 is available.
- The following balances are given.
1 January 2025
$31 December 2025
$Inventory 29 000 21 000 Trade receivables 32 000 33 000 Trade payables 27 000 30 000 Cash and cash equivalents 11 000 17 000 Accrued loan interest - 1 000 Ordinary share capital 100 000 120 000 Share premium 10 000 20 000 Retained earnings 30 000 34 000 Debentures 20 000 20 000
- The following balances were on 1 January 2025.
$ Non-current assets at cost 200 000 Provision for depreciation 85 000
- Office equipment costing $25 000 was sold for $7 000. It had a carrying value of $10 000 at the point of sale. New office equipment was purchased for $105 000. Non-current assets are depreciated at 20% per annum using the straight-line method. A full year's depreciation is charged in the year of purchase but none is charged in the year of disposal.
- There was a rights issue of shares during the year.
- Loan interest, $1 000, was paid.
- Taxation, $2 000, was paid.
- Dividends, $12 000, were paid.
(a) Calculate the profit for the year 2025.
(b) Prepare the statement of cash flows for the year ended 31 December 2025.
Answer:
(a)
Calculate the profit
- Find the increase in the retained earnings
- Add the dividends paid
$ Retained earnings at 31 December 2025 34 000 Retained earnings at 1 January 2025 (30 000) Dividends paid 12 000 Profit for the year 16 000 Final answer: Profit for the year was $16 000
(b)
Calculate the loan interest that was due
- Add the amount paid to the amount that is still accrued
$1 000 + $1 000 = $2 000
Calculate the profit from operations
$ Profit for the year 16 000 Add: Loan interest 2 000 Add: Tax 2 000 Profit from operations 20 000 Calculate the depreciation charge for the year
- Find the total cost of the non-current assets at the end of the year
$200 000 - $25 000 + $105 000 = $280 000
- Find 20% of this amount
20% × $280 000 = $56 000
Calculate the loss on sale of equipment
$10 000 - $7 000 = $3 000
Calculate the amount received from the rights issue
- Subtract the old share capital from the new share capital
($120 000 + $20 000) - ($100 000 + $10 000) = $30 000
Calculate the change in inventory, trade receivables and trade payables
$ Inventory 29 000 - 21 000 8 000 Decrease Trade receivables 33 000 - 32 000 1 000 Increase Trade payables 30 000 - 27 000 3 000 Increase Prepare the statement of cash flows
$000 $000 Cash flows from operating activities Profit from operations 20 Depreciation 56 Loss on sale of equipment 3 Decrease in inventory 8 Increase in trade receivables (1) Increase in trade payables 3 Cash from operations 89 Interest paid (1) Tax paid (2) Net cash from operating activities 86 Cash flows from investing activities Purchase of equipment (105) Proceeds of sale of equipment 7 Net cash used in investing activities (98) Cash flows from financing activities Proceeds of rights issue of ordinary shares 30 Dividends paid (12) Net cash from financing activities 18 Net increase in cash and cash equivalents 6 Cash and cash equivalents at 1 January 2025 11 Cash and cash equivalents at 31 December 2025 17
Was this revision note helpful?
Build on this topic