Statement of Profit or Loss (Cambridge International A-Level Accounting)
Statements of profit or loss for partnerships
Spec point — how to prepare a statement of profit or loss, appropriation account and statement of financial position for a partnership from full or incomplete accounting records. The business may be a trading or a service business
What is the layout of the statement of profit or loss of a partnership?
-
The statement of profit or loss for a partnership is **very similar **to that for a sole trader
-
The statement of profit or loss for a partnership will have one new addition, for the** interest on a partner’s loan**
- A partner may choose to lend money to the partnership
- If this is the case, interest on the loan is a finance cost and an expense to the business
-
The following do not appear on the statement of profit or loss
- Interest on partners' capital
- Interest on partners' drawings
- Partners' salaries
-
You may have to make adjustments to a statement of profit or loss
- This is the same idea as when preparing a statement of profit or loss for a sole trader
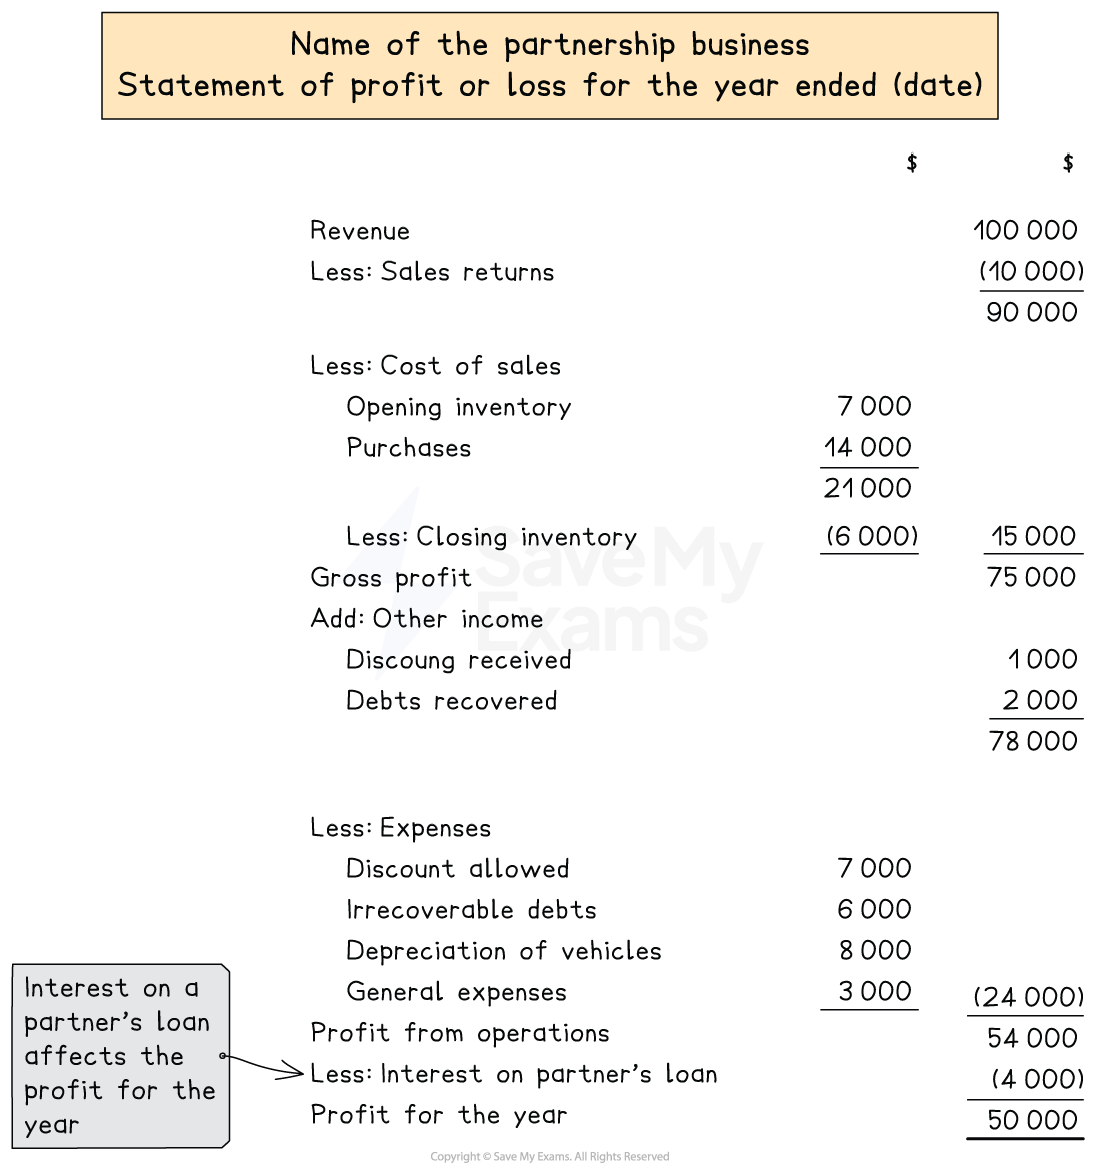
Layout of a statement of profit or loss for a partnership
Worked Example Tam and Pan are in partnership providing car repair services in their local area. The following is a list of their balances for the year ended 30 June 2023.
$ Income from repair services 101 260 Salaries of employees 30 400 Electricity 2 420 Telephone 3 110 Rent and rates 10 000 Trade payables 12 190 Trade receivables 14 220 Discount allowed 1 400 Office expenses 10 610 Supplies for repairs 41 570 Irrecoverable debts 1 200 Machinery and Equipment at cost 52 000 Provision for depreciation on machinery and equipment 20 800 Tam:
- Capital
- Current account
- Drawings60 000
430
20 600Pan
- Capital
- Current account
- Drawings30 000
300
15 700Bank 21 750 Additional information 30 June 2023:
- Depreciate the office equipment at 20% per year using the straight-line method
- On 1 July 2022, Pan loaned $5 000 to the partnership with loan interest at 5% per annum
- Pan is to receive an annual partnership salary of $12 000
- Remaining profits and losses are shared as follows: Tan ⅔, Pam ⅓
- 5% interest is allowed on partners’ capital accounts
- 10% interest is charged on partners’ drawings
Prepare the statement of profit or loss for Tam and Pan for the year ended 30 June 2023.
Answer:
Identify which balances affect the statement of profit or loss
$ Statement of profit or loss? Income from repair services 101 260 SoPoL Salaries of employees 30 400 SoPoL Electricity 2 420 SoPoL Telephone 3 110 SoPoL Rent and rates 10 000 SoPoL Trade payables 12 190 Trade receivables 14 220 Discount allowed 1 400 SoPoL Office expenses 10 610 SoPoL Supplies for repairs 41 570 SoPoL Irrecoverable debts 1 200 SoPoL Machinery and Equipment at cost 52 000 Provision for depreciation on machinery and equipment 20 800 Tam:
- Capital
- Current account
- Drawings60 000
430
20 600Pan
- Capital
- Current account
- Drawings30 000
300
15 700Bank 21 750 Deal with the additional information.
Depreciate the machinery and equipment at 20% per year using the straight-line method
- Find the year's depreciation by multiplying the cost by 20%
$52 000 × 20% = $10 400
On 1 July 2022, Pan loaned $5 000 to the partnership with loan interest at 5% per annum
- Find the year's interest by multiplying the loan amount by 5%
$5 000 × 5% = $250
Pan is to receive an annual partnership salary of $12 000
- This does not affect the statement of profit or loss
Remaining profits and losses are shared as follows: Tan ⅔, Pam ⅓
- This does not affect the statement of profit or loss
5% interest is allowed on partners’ capital accounts
- This does not affect the statement of profit or loss
10% interest is charged on partners’ drawings
- This does not affect the statement of profit or loss
Prepare the statement of profit or loss using the required format
Note that it is a service business so will not have a trading section
Final answer: Tam and Pan
Final answer: Statement of Profit or Loss for the year ended 30 June 2023Final answer: $** Final answer: $ Final answer: Income from repair services Final answer: 101 260 Final answer: Less: Expenses Final answer:** Supplies for repairs ** Final answer: 41 570 Final answer:** Salaries ** Final answer: 30 400 Final answer:** Offices expenses ** Final answer: 10 610 Final answer:** Irrecoverable debts ** Final answer: 1 200 Final answer:** Rent and rates ** Final answer: 10 000 Final answer:** Electricity ** Final answer: 2 420 Final answer:** Telephone ** Final answer: 3 110 Final answer:** Discount allowed ** Final answer: 1 400 Final answer:** Depreciation on machinery and equipment Final answer: 10 400 Final answer: (111 110) Final answer: Loss from operations Final answer: (9 850) Final answer: Less: Loan interest (Pan) Final answer: (250) Final answer: Loss for the year Final answer: (10 100)
Was this revision note helpful?
Build on this topic