Revaluation Account (Cambridge International A-Level Accounting)
Spec point — how to prepare a revaluation account
Revaluation account
What is a revaluation account?
-
A revaluation account is a temporary account
-
It is used to calculate the net profit or loss when adjusting the book values of assets and liabilities to their current fair values
-
It is used when a partnership continues to operate but its structure changes
- Such as the introduction of a new partner or the retirement of an existing partner
Why is a revaluation account used?
-
It is important that an accurate current value of a business is found before making any changes to the structure of the partnership
-
The assets might have increased in value since their purchase
- The current partners should benefit from this increase before changing the structure
-
Revaluing assets and liabilities, before changing the structure of the partnership, ensure that
- new partners do not unfairly benefit from past gains
- new partners are not unfairly penalised for past losses
How do I prepare a revaluation account?
-
STEP 1 Work out the increase or decrease of each asset
- Increases are on the credit side
- Decreases are on the debit side
-
STEP 2 Work out the increase or decrease of each liability
- Increases are on the debit side
- Decreases are on the credit side
-
STEP 3 Find the balancing figure
- It is a net profit on revaluation if it is on the debit side
- It is a net loss on revaluation if it is on the credit side
-
STEP 4 Share the net profit or loss on revaluation between the partners' capital accounts using the old profit-sharing ratio
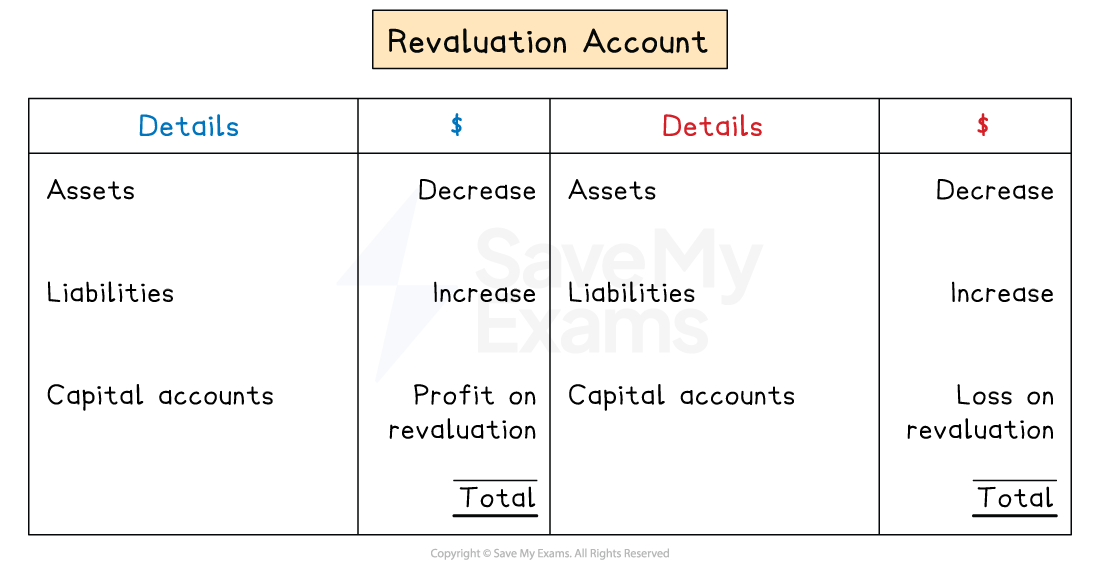
Layout of a revaluation account
Exam Hint If you struggle to remember what goes on which side, then consider the other side of the transaction.
For example, if an asset increases in value, then the asset account will have a debit entry to increase its value. Therefore, the revaluation account will have a credit entry.
Questions do not tend to ask you to prepare the revaluation account, they mainly ask you to find the effects on the capital accounts. However, it is helpful to sketch a quick revaluation account to help with this calculation.
Worked Example Ameena and Bilal are in partnership and share profits and losses in the ratio 7:4 respectively.
The following balances were available on 31 December 2025.
$ Vehicles at cost 30 000 Accumulated depreciation of vehicles 12 500 Trade receivables 62 500 Inventory 11 000 Capital accounts Ameena 60 000 Bilal 35 000 Ameena and Bilal admit a new partner, Carry, on 1 January 2026. Profits and losses are to be shared between Ameena, Bilal and Carry in the ratio 4:2:1 respectively.
They agree the following valuations:
$ Vehicles 20 000 Inventory 9 000 They also agreed to write off trade receivables' balances totalling $6 000 as irrecoverable debts.
Find the balance on Ameena's capital account after the revaluation.
Answer:
Calculate the net book value of the vehicles before the revaluation
$30 000 - $12 500 = $17 500
Calculate the increase in value of the vehicles
$20 000 - $17 500 = $2 500
Calculate the decrease in inventory
$11 000 - $9 000 = $2 000
Work out the net loss on revaluation
$ Increase in vehicles 2 500 Decrease in inventory (2 000) Decrease in trade receivables (6 000) Loss on revaluation (5 500) Find the share of the loss for Ameena using the old ratio
$ 5 500×7 / 11=$ 3 500Note that the revaluation account would look like:
Revaluation account
$ $ 2026 2026 Jan 1 Inventory 2 000 Jan 1 Vehicles 2 500 Trade receivables 6 000 Capital - Ameena (loss on revaluation) 3 500 Capital - Bilal (loss on revaluation) 2 000 8 000 8 000 Calculate Ameena's capital account balance
$ Increase in vehicles 2 500 Balance on 31 December 2025 60 000 Loss on revaluation (3 500) Balance on 1 January 2026 Final answer: 56 500 Final answer: $56 500
Was this revision note helpful?
Build on this topic