Capital & Current Accounts (Cambridge International A-Level Accounting)
Partners' capital & current accounts
Spec point — why partners may maintain separate capital accounts and current accounts how to prepare partners’ capital and current accounts
Partners' capital & current accounts
What is a partner's capital account?
-
The capital account shows the amounts that were originally invested in the partnership by each partner
- Plus any amounts of money they may put in at a later date
- Loans to the business from a partner are not entered into the capital account
-
The capital account of each partner is only used for recording the partners’ capital contribution and partners’ withdrawal of capital
- Withdrawal of capital is different to taking drawings
- Drawings are not entered into the capital account
What is the layout of a partner's capital account?
-
Each partner might have a separate capital account or there might be one combined capital account for the partnership
- If a combined account is used then there are columns for each partner on both sides
-
The capital account has a credit balance and shows the amount owed by the business to the partner(s)
-
Entries are only made when the amount of capital invested by the partners changes
- The entry is on the credit side if it is an increase
- The entry is on the debit side if it is a decrease
What is a partner's current account?
-
The current accounts are prepared after the appropriation account
-
The current accounts are treated as working accounts to show the change in the amount owed to each partner by the business
-
Permanent changes go into the capital accounts
- Such as further investments into the business
-
Temporary changes go into the current accounts
- Such as profit shares, salaries and interest on capital, drawings and loans
-
What is the layout of a partner's current account?
-
Each partner might have a separate current account or there might be one combined current account for the partnership
- This is same as for a capital account
-
Entries are made on the debit side if the amount the business owes the partner(s) decreases
- Loss for the year
- Partner's drawings
- Interest on a partner's drawings
-
Entries are made on the credit side if the amount the business owes the partner(s) increases
- Profit for the year
- Interest on a partner's capital
- Interest on a partner's loan
- A partner's salary
-
The closing balance of the current account shows how much undrawn or overdrawn profits the partner has
- A debit balance indicates that the partner has taken too much money from the partnership in anticipation of profits
- A credit balance indicates that the partner has not taken all of their share of the profits
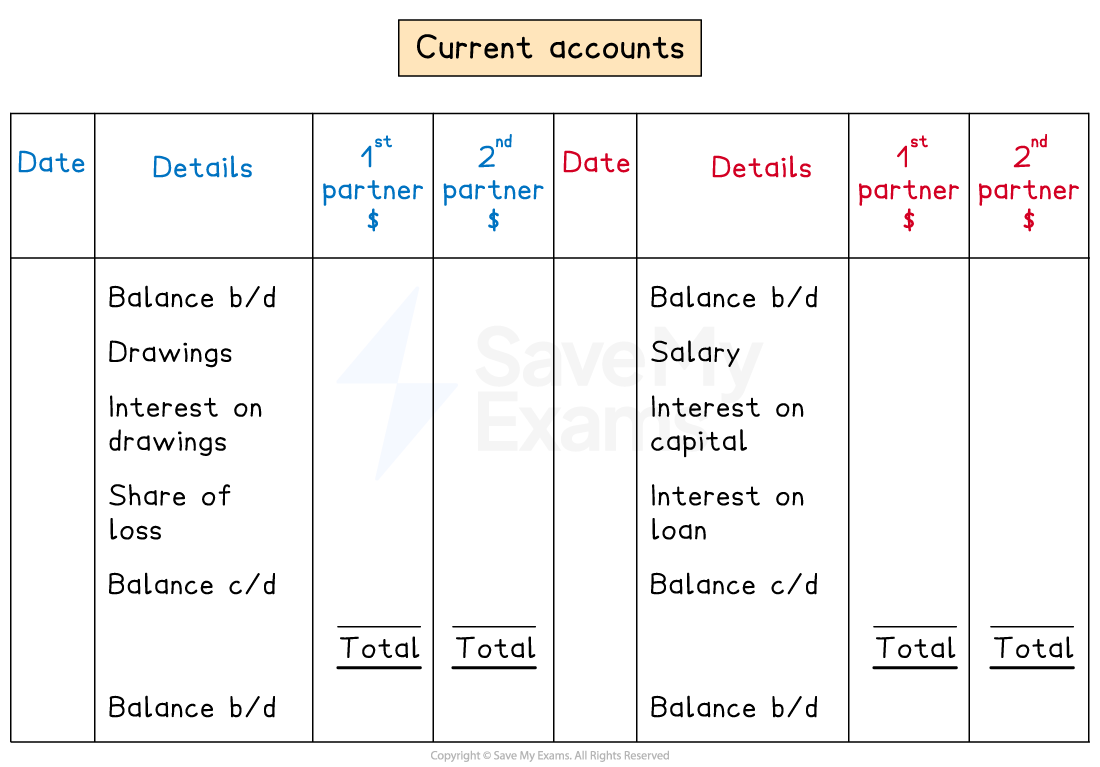
Layout of the partners' current accounts
Exam Hint If you use a combined current account then remember to balance each column separately, similar to how you balance the cash and bank columns in the cash book.
Why do partnerships maintain separate current accounts and capital accounts?
-
Partnerships use both a current account and a capital account to keep different types of entries separate
-
The capital account only contains the amounts invested by each partner
- This means that partners can easily see how much everyone has invested
- This makes it easier to calculate the interest on capital
-
The current account shows annual changes made to the amounts owed to the partners by the business
- This allows the partners to see which partners are withdrawing more money than their profit share
How are loans from partners treated in the accounts of a partnership?
-
Loans from partners are treated in a similar way to other loans
-
They are not treated as part of the partner’s capital account
- A loan account is created
-
The loan is a liability on the statement of financial position
-
The interest is added to the partner's current account
- The partner can withdraw the interest from the business bank account as drawings
What are the journal entries for the partners' current account?
-
At the end of the year journal entries are made for the items in the partner's current accounts
-
To remember the journal entries:
- Identify whether the entry is on the debit or credit side of the partner's current account
- Identify where the amount has come from
| Account to be debited | Account to be credited | |
|---|---|---|
| Awarding interest on partners' capital | Appropriation account | Partners' current account |
| Transferring a partner's drawings to the current account at the end of the year | Partner's current account | Partner's drawings account |
| Awarding interest on partners' drawings | Partners' current account | Appropriation account |
| Paying a partner's salary | Appropriation account | Partners' current account |
| Awarding interest on a partner's loan | Statement of profit or loss | Partners' current account |
| Transferring shares of the residual profit to the current account | Appropriation account | Partners' current account |
| Transferring shares of the residual loss to the current account | Partners' current account | Appropriation account |
Why are there no entries made in the cash or bank account for salaries and interest?
-
A partner does not receive cash when they are awarded interest on their capital or a salary
- Interest and salaries are a way of sharing the profit
-
They are added to the partners' current accounts
- The balances that the business owes them increases
-
The partners may choose to withdraw these amounts as drawings
- The cash and bank accounts are used at this stage
Worked Example Lydia and Moses are in partnership and own a business which specialises in selling clothing to young people called Top Trends. The following information was extracted from their accounts for the year ended 31 December 2023:
Capital accounts at 1 January 2023 Lydia 50 000 Moses 40 000 Current accounts at 1 January 2023 Lydia 3 420 credit balance Moses 1 780 credit balance Drawings for the year ended 31 December 2023 Lydia 6 000 Moses 5 000 Share of profits for the year ended 31 December 2023 Lydia 12 000 Moses 8 000 The partnership agreement provides for
- 5% interest on capital
- 10% interest on drawings
- $1 500 salary for Lydia
Prepare the current accounts for Lydia and Moses for the year ended 31 December 2023. Balance the accounts and bring down the balance at 1 January 2024.
Answer:
- Calculate the interest on capital by multiplying the capital by 5%
Lydia: 5% × $50 000 = $2 500
Moses: 5% × $40 000 = $2 000
- Calculate the interest on drawings by multiplying the drawings by 10%
Lydia: 10% × $6 000 = $ 600
Moses: 10% × $5 000 = $500
Enter the amounts into a combined current account
Enter the opening balances on the credit side
Enter the following on the debit side:
- drawings
- interest on drawings
Enter the following on the credit side:
- interest on capital
- salary
- profit share
Balance the accounts
Final answer: Lydia and Moses
Final answer: Current AccountsFinal answer: Date Final answer: Details Final answer: Lydia
Final answer: $**Final answer: Moses
Final answer: $Final answer: Date Final answer: Details Final answer: Lydia
Final answer:****$Final answer: Moses
Final answer: $Final answer: 2023
Final answer: Jan 1Final answer:** **
Final answer: DrawingsFinal answer: 6 000 Final answer: 5 000 Final answer: 2023
Final answer: Jan 1Final answer:** **
Final answer: Balance b/dFinal answer:** **
Final answer: 3 420Final answer:** **
Final answer: 1 780Final answer: Dec 31 Final answer: Interest on drawings Final answer: 600 Final answer: 500 Final answer: Dec 31 Final answer: Interest on capital Final answer: 2 500 Final answer: 2 000 Final answer: Dec 31 Final answer: Balance c/d Final answer: 12 820 Final answer: 6 280 Final answer: Dec 31 Final answer: Salary Final answer: 1 500 Final answer: Dec 31 Final answer: Profit share Final answer: 12 000 Final answer: 8 000 Final answer: 19 420 Final answer: 11 780 Final answer: 19 420 Final answer: 11 780 Final answer: 2024
Final answer: Jan 1Final answer:** **
Final answer: Balance b/dFinal answer:** **
Final answer: 12 820Final answer:**
Final answer: 6 280
Was this revision note helpful?