Break-even Analysis (Cambridge International A-Level Accounting)
Break-even charts
Spec point — how to interpret a break-even chart
What is a break-even chart?
-
A break-even chart is a graphical representation of costs, revenue, and profit at different levels of output
-
The number of units sold or produced is plotted on the horizontal axis
-
The costs and revenue in monetary terms ($) are plotted on the vertical axis
-
The line for fixed cost is horizontal because it doesn’t change with the output level
-
The lines for variable cost and revenue increase as output level increases
-
The line for total cost
- starts at the same value as the fixed cost
- and is parallel to the line for variable cost
-
The break-even point is the point at which total revenue equals total costs
- Total costs are covered by sales
- No profit or loss is made
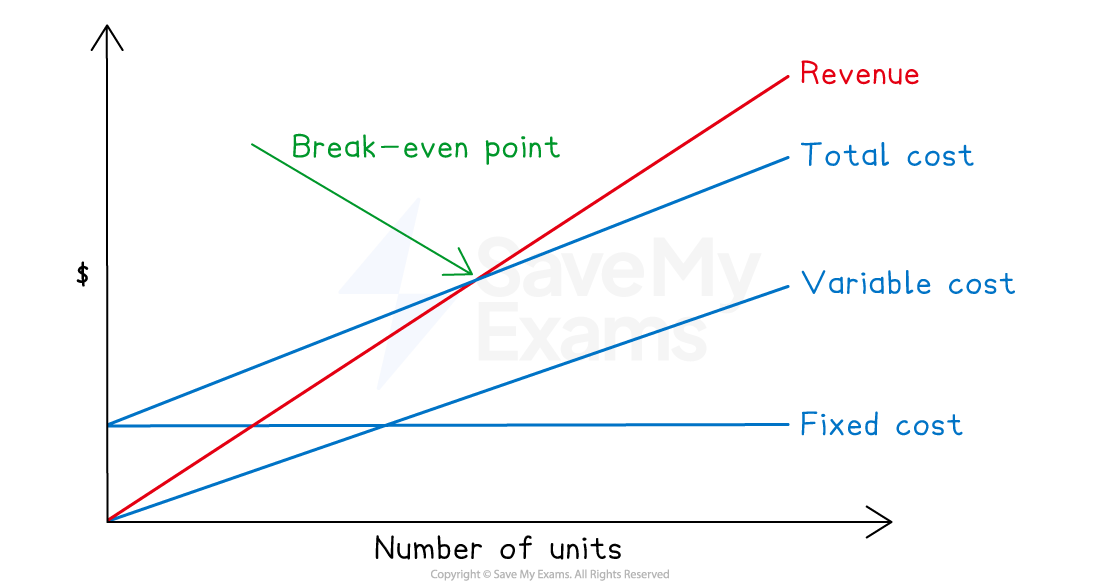
Break-even chart
Exam Hint You will never be required to construct a break-even chart in the exam. You just need to be able to interpret them and use them in calculations.
Calculations using a break-even chart
Spec point — how to calculate the break-even point, contribution to sales ratio, level of output or sales to achieve a target profit, and margin of safety
How do I calculate the break-even point?
-
The formula for the number of units required to break-even is:
- If your answer is a decimal, you should always round your answer up to the next whole number
-
There are two formulas for the sales revenue required to break-even:
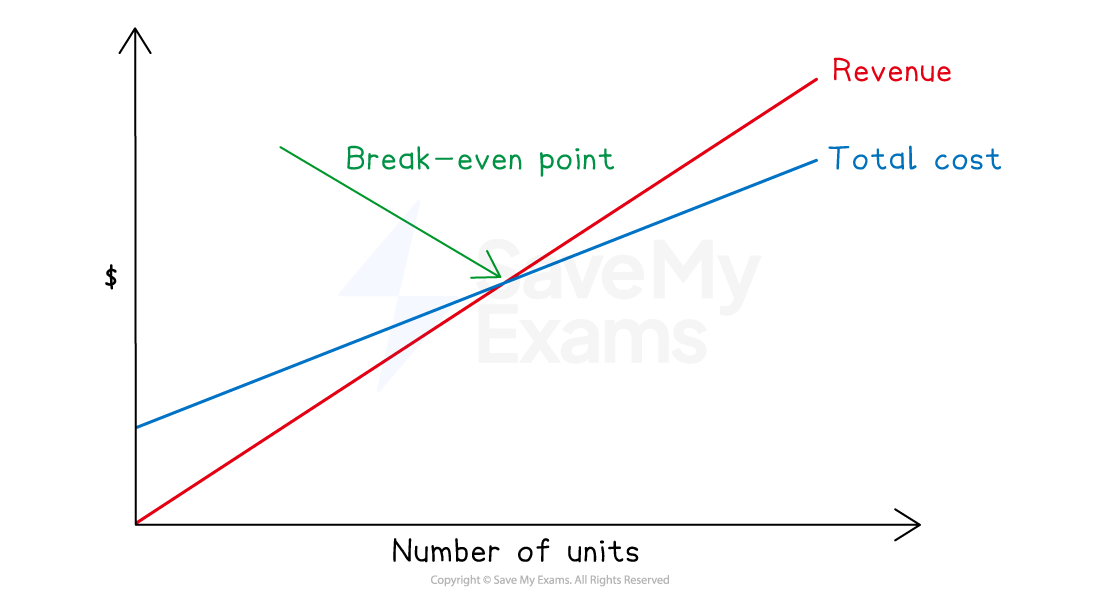
Break-even point
Exam Hint You can use whichever formula you want. However, if a question first asks you to find the contribution to sales ratio, then it is easier to use that to find the break-even point.
If you forget the formulas, you can easily derive them using algebra. Let be the number of units sold, be the selling price per unit, be the fixed cost and be the variable cost per unit.
Worked Example The following forecasted data is available.
$ Total fixed costs 100 000 Direct materials 3 000 Direct labour 5 000 Other direct costs 6 000 Sales revenue (10 000 units) 200 000 Calculate the break-even point in units.
Answer:
Calculate the total variable cost
Variable costs = Direct materials + Direct labour + Other direct costs
= $3 000 + $5 000 + $6 000
= $14 000
Calculate the total contribution
Contribution = Revenue - Variable costs
= $200 000 - $14 000
= $186 000
Calculate the contribution per unit
Contribution per unit = Total contribution ÷ Number of units
= $186 000 ÷ 10 000
= $18.60 per unit
Calculate the break-even point in units
Break-even point in units = Total fixed costs ÷ Contribution per unit
= $100 000 ÷ 18.6 *
= 5 376.34*
Round up to the next whole number
Final answer: Break-even point in units is 5 377 units
How do I calculate the level of output required to achieve a target profit?
-
The formula for the number of units required to achieve a target profit is:
- If your answer is a decimal, you should always round your answer up to the next whole number
-
There are two formulas for the sales revenue required to achieve a target profit:
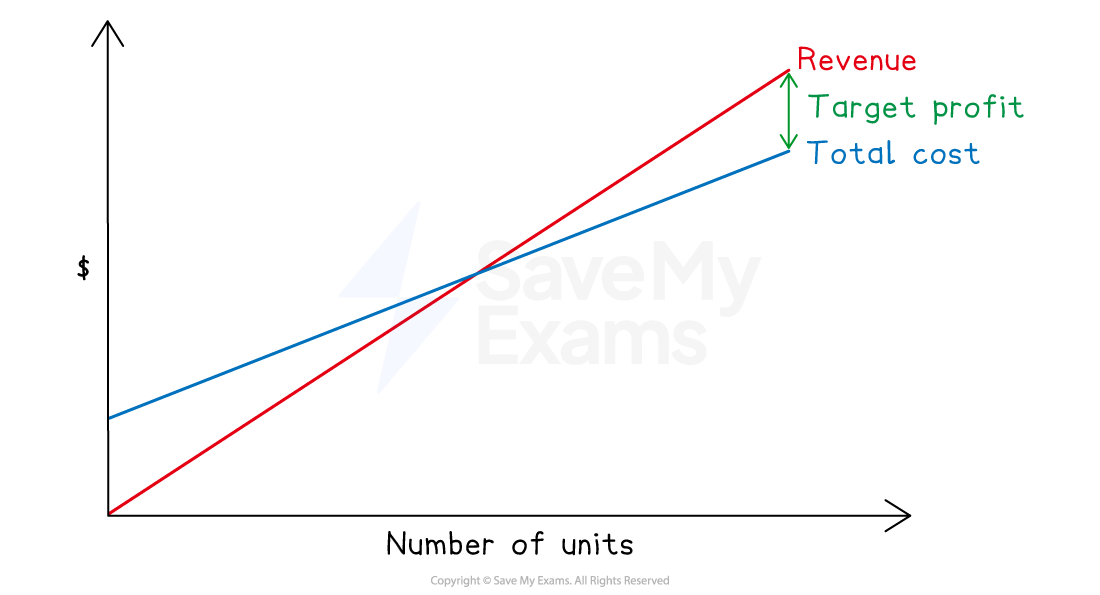
Target profit
Worked Example Total fixed cost $40 000
Variable cost per unit $30 per unit
Selling price per unit $50 per unit
What is the level of output required in units and in sales revenue for a target profit of $60 000?
Answer:
Calculate the contribution per unit
Contribution per unit = Selling price per unit - Variable cost per unit
= $50 -$ 30
= $20 per unit
Calculate the number of units required to make the profit
Level of output required in units = (Total fixed costs + Target profit) ÷ Contribution per unit
= ($40 000 + $60 000) ÷ $20
= 5 000 units
Final answer: The level of output required to achieve a target profit of $60 000 is 5 000 units
Multiply this by the selling price per unit
5 000 × $50
= $250 000
Or calculate the contribution to sales ratio and use the relevant formula
Sales to contribution ratio = $20 ÷ $50 = 0.4
Level of output required in sales revenue = (Total fixed costs + Target profit) ÷ Contribution to sales ratio
= ($40 000 + $60 000) ÷ 0.4
= $250 000
Final answer: The level of output required to achieve a target profit of $60 000 is $250 000 in sales revenue**
How do I calculate the margin of safety?
-
The margin of safety is the difference between actual/forecast output and the break-even level of output
-
It shows how much sales can fall before a business reaches the break-even point
-
The formula for the number of units in the margin of safety is:
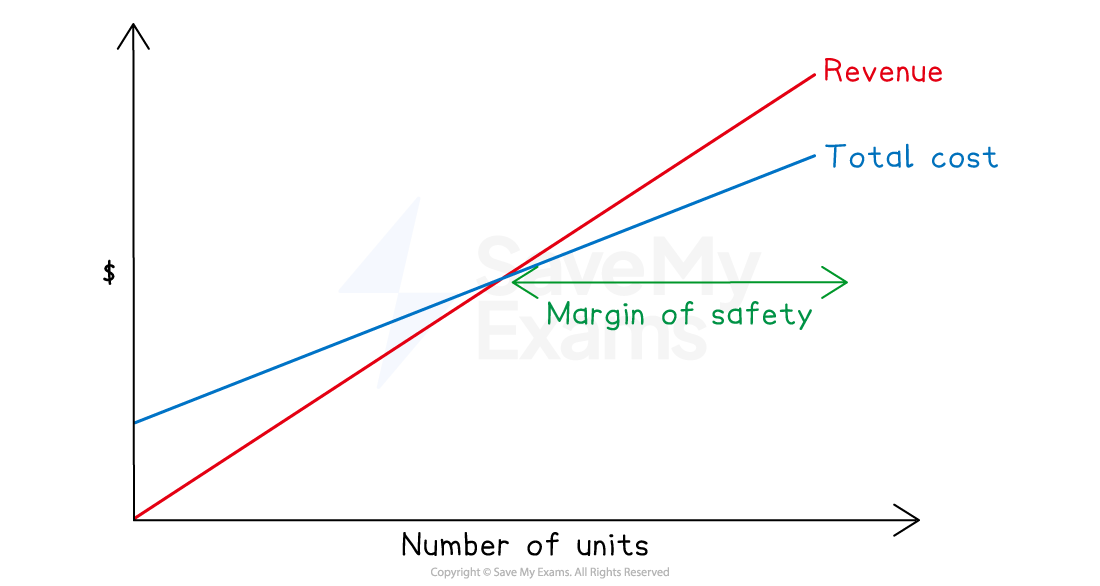
Margin of safety
Worked Example Forecasted production 15 000 units.
Break-even point units 10 000 units.
Calculate the margin of safety in units.
Answer:
Use the formula
Margin of safety in units = Forecasted production - Break-even point in units
= 15 000 - 10 000
Final answer: Margin of safety is 10 000 units
Uses & limitations of break-even analysis
Spec point — the use and limitations of break-even analysis
What are the uses of break-even analysis?
-
Break-even analysis can calculate break-even point, level of output to achieve target profit, margin of safety which helps management with marketing decisions
-
The visual graphical representation is easy to understand
-
Assists short-term decision-making
- Such as setting selling prices
What are the limitations of break-even analysis?
-
Fixed costs are treated as staying the same, but they may only stay fixed up to a certain point
- i.e. they may be stepped
-
Analysis is only based on budgets
-
Costs may change due to changes in market
Was this revision note helpful?