Cash Budgets (Cambridge International A-Level Accounting)
Spec point — how to prepare the following budgets: – cash
Cash budgets
How to prepare a cash budget?
- The cash budget shows all the projected **money coming in **and going out
- The cash budget includes all transactions relating to cash, cheque and** bank transactions**
- Here is an example of the cash budget
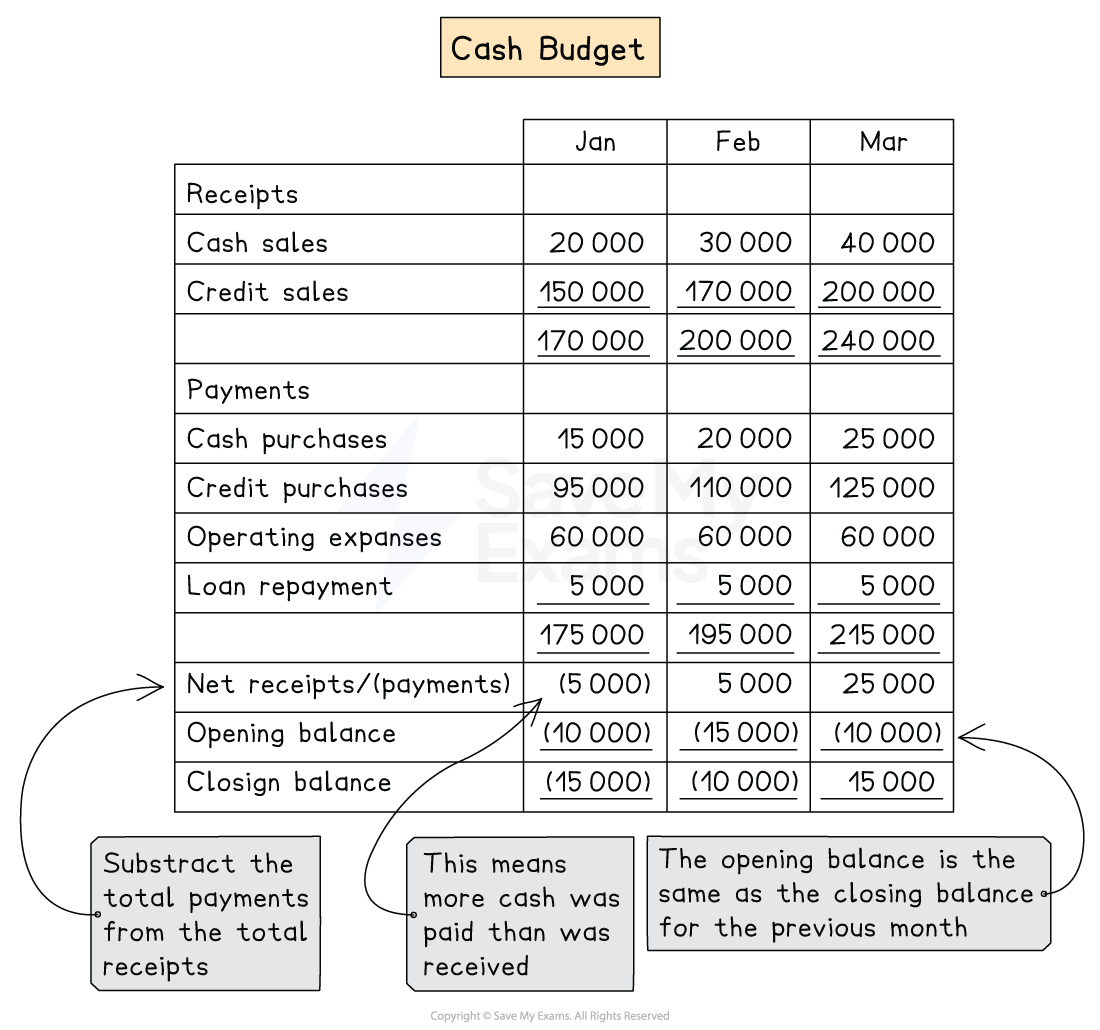
Example of a cash budget
-
STEP 1 Calculate the receipts for each period
-
This may include:
- Receipts of cash sales
- Receipts from credit sales
- Sale of non-current assets
- Capital
- Loans
-
-
STEP 2 Calculate the payments for each period
-
This may include:
- Payment of cash purchases
- Payments for credit purchases
- Purchase of non-current assets
- Drawings
- Loan repayments
- Cash expenses only
-
-
STEP 3 Calculate the net receipts or payments by using this formula
- Total receipts - total payments
-
STEP 4 Write down the opening balance
- This is the same as the closing balance for the previous month
- Brackets indicate that the bank is overdrawn
-
STEP 5 Find the closing balance
- Add the net cash flow to the opening balance
Exam Hint If depreciation is included in the expenses, then you need to subtract it from the total. Depreciation does not affect the cash budget.
Worked Example Cushions manufacture a range of cushions. Here is the following information relating to a cash budget:
January February March Sales $ 60 000 58 000 66 000 Purchases $ 30 000 28 000 31 000 Expenses (including depreciation) 15 000 12 000 12 000 Additional information
- 40% of sales are made on cash basis. The remaining 60% of customers will pay one month later. Sales in December are expected to be $40 000.
- Payments to suppliers are made one month later. The purchases expected in December is to be $20 000.
- Expenses are paid in the month they are incurred.
- The opening balance in January is expected to be $3 000 overdrawn.
- Depreciation for existing non-current assets for the year is $12 000.
- In February a new van was purchased for $17 000. The policy is that vehicles are not depreciated in the year of purchase.
- Loan repayments will be $1 500 each month starting in February
Prepare the cash budget for January, February and March
Answer
Calculate the receipts for all three months
- Sales:
January
Cash sales = 40% × $60 000 = $24 000
Credit sales = 60% × $40 000 = $24 000
February
Cash sales = 40% × $58 000 = $23 200
Credit sales = 60% × $60 000 = $36 000
March
Cash sales = 40% × $66 000 = $26 400
Credit sales = 60% × $58 000 = $34 800
Calculate the payments for all three months
- Purchases January = $20 000 February = $30 000 March = $28 000
- Expenses
Depreciation for the month = $12 000 ÷ 12 = $1 000 per month January = $15 000 - $1 000 = $14 000 February = $12 000 - $1 000 = $11 000 March = $12 000 - $1 000 = $11 000
The answer will be presented as the following cash budget:
January
$February
$March
$Receipts Cash sales 24 000 23 200 26 400 Credit customer - one month 24 000 36 000 34 800 Total receipts 48 000 59 200 61 200 Payments Credit suppliers - one month 20 000 30 000 28 000 Expenses 14 000 11 000 11 000 Van 17 000 Loan repayment 1 500 1 500 Total Payments 34 000 59 500 40 500 Net receipts or payments 14 000 (300) 20 700 Opening balance (3 000) 11 000 10 700 Closing balance 11 000 10 700 31 400
Was this revision note helpful?
Build on this topic