Purchases Ledger Control Accounts (Cambridge International A-Level Accounting)
Spec point — entries in control accounts sales ledger control accounts and purchases ledger control accounts
Purchases ledger control accounts
What is a purchases ledger control account?
-
A purchases ledger control account is an account that summarises all the transactions for trade payables
-
A purchases ledger control account can either be a ledger account or a memorandum account
-
If it is part of the double-entry system, then the individual ledger accounts are memorandum accounts
- The purchases ledger control account is used for journal entries instead of the individual trade payables accounts
-
Where do I find the information to complete a purchases ledger control account?
-
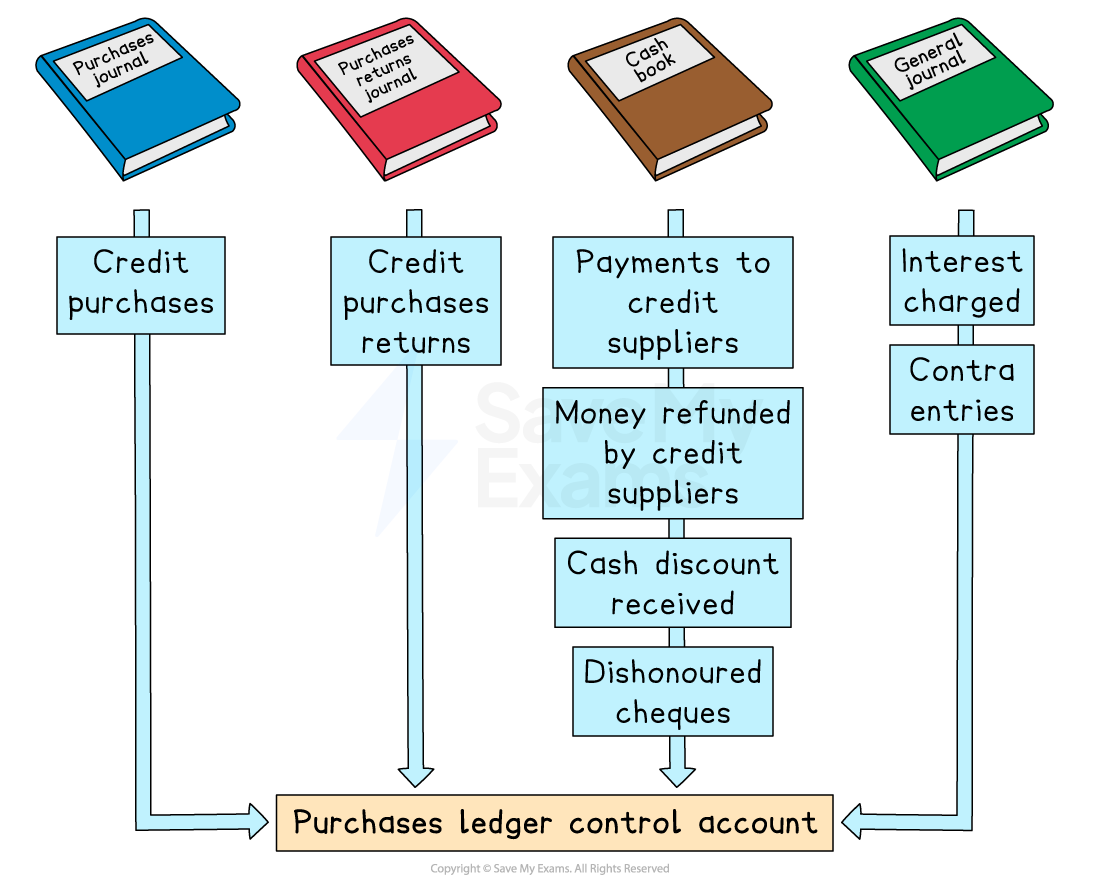
The books of prime entry are used to find the totals
-
The purchases journal is used to find the total value of credit purchases
-
The purchases returns journal is used to find the total value of returned goods
-
The cash book is used to find the total values for:
- Money paid to credit suppliers
- Money refunded by credit suppliers
- **Cash discounts received **from credit suppliers
-
The** journal** is used to find the total values for:
- Interest charged by credit suppliers on overdue accounts
- Contra entries against the sales ledger
Exam Hint The ledger accounts are not used when preparing control accounts. The information is taken from the books of prime entry.
Why might there be a debit balance in a purchases ledger control account?
-
A trade payables account will usually have a credit balance
- This indicates that the business owes the credit supplier money
-
However, a trade payables account could have a debit balance
- This indicates that the credit supplier owes the business money
-
Debit balances can occur when:
-
The business pays credit suppliers in advance
-
The business makes overpayments to credit suppliers
-
The business is owed refunds from the credit suppliers
- The business has paid for goods and then returned them
-
-
Debit and credit balances are totalled separately in the purchases ledger control account
- This means there could be two opening balances and two closing balances
What is the layout of a purchases ledger control account?
-
The layout looks very similar to the layout of a trade payables ledger account
-
The main differences are:
- There could be two opening balances
- There could be two closing balances
| Entries on the debit side: | Entries on the credit side: |
|---|---|
| - Opening balance - Money that credit suppliers owe - Purchases returns - Credit purchases only - Bank - Bank transfers to credit suppliers - Cash - Cash paid to credit suppliers - Discount received - Contra | - Opening balance - Money owed to credit suppliers - Purchases - Credit purchases - Interest - Bank - Refunds from credit suppliers |
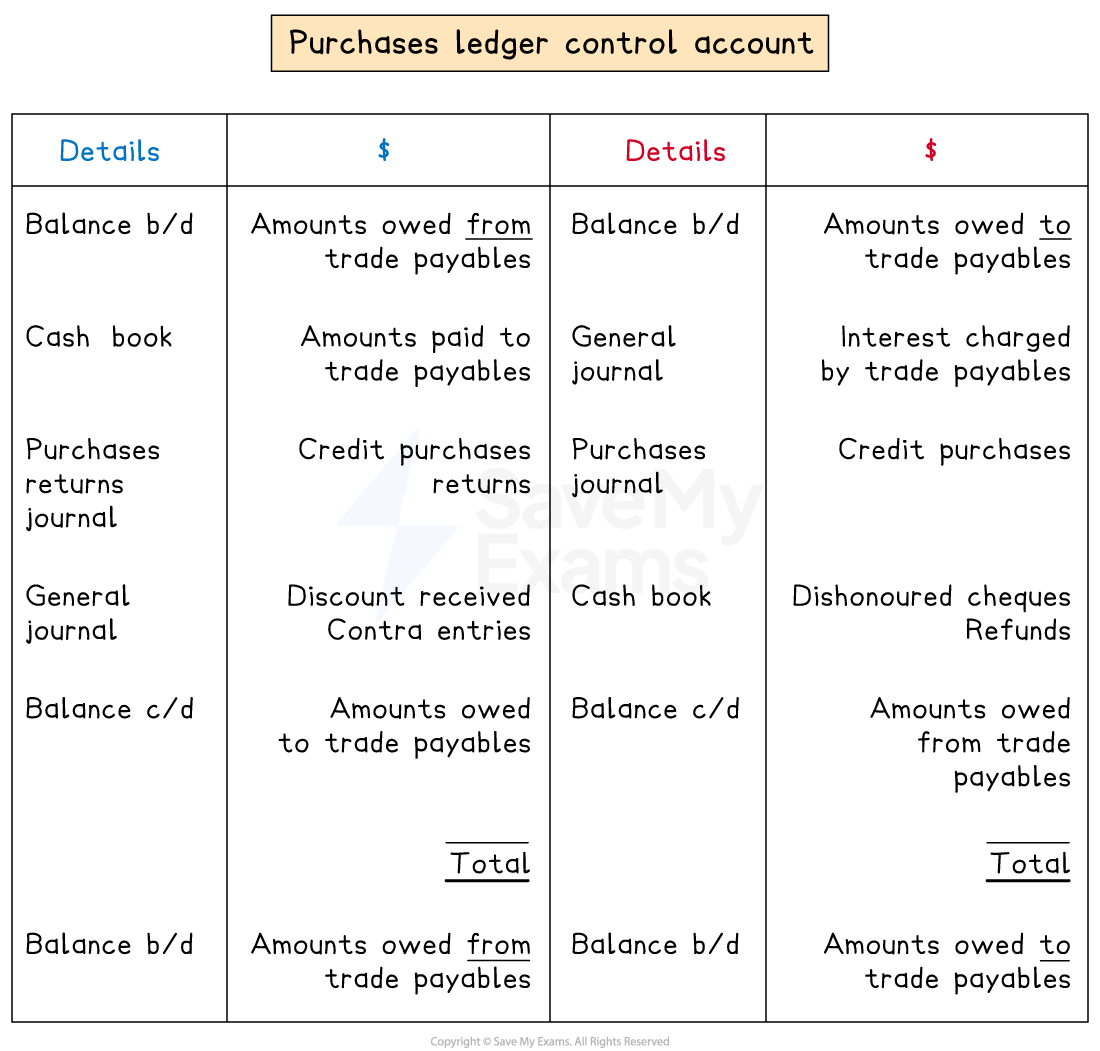
Layout of a purchases ledger control account
Exam Hint Remember that cash purchases are not recorded in the purchases ledger. Only enter cash paid to credit suppliers when the cash is used to make a payment towards an invoice.
Worked Example Mika is a trader and does not maintain control accounts as part of his accounts. He has provided the following information
2023 $ 1 March Purchases ledger control account credit balance 17 150 Purchases ledger control account debit balance 1 350 2024 29 February Totals for the year: Credit purchases 231 200 Cash purchases 5 000 Bank payments to credit suppliers 210 600 Cash payments to credit suppliers 1 500 Returns to credit suppliers 6 400 Discount received 3 200 Contra entries 2 100 Interest charged by credit suppliers 800 Purchases ledger control account credit balance ? Purchases ledger control account debit balance 450 Prepare the purchases ledger control account for the year ended 29 February 2024. Balance the account and bring down the balances on 1 March 2024.
Answer:
Ignore the cash purchases, as they do not affect the purchases ledger accounts.
Enter the balances and totals on the correct sides of the account.
Transactions which increase the amount the business owes appear on the credit side.
- Credit purchases
- Interest
Transactions which reduce the amount the business owes appear on the debit side.
- Payments to credit suppliers using cash or bank transfers
- Purchases returns
- Discount received
- Contra entries
At the end of the month there is $450 debit balance. On 1 March 2024, there will be a debit balance of $450; therefore, there will need to be a balance c/d on the credit side on 29 February 2024.
Final answer: Mika Purchases Ledger Control Account
Final answer: Date Final answer: Details Final answer: $** Final answer: Date Final answer: Details Final answer: $ Final answer: 2023
Final answer: Mar 1Final answer:** **
Final answer: Balance b/dFinal answer: 1 350 Final answer: 2023
Final answer: Mar 1Final answer: Balance b/d Final answer: 17 150 Final answer: 2024
Final answer: Feb 29Final answer: Bank Final answer: 210 600 Final answer: 2024
Final answer: Feb 29Final answer: Purchases Final answer: 231 200 Final answer: 29 Final answer: Cash Final answer: 1 500 Final answer: 29 Final answer: Interest Final answer: 800 Final answer: 29 Final answer: Purchases returns Final answer: 6 400 Final answer: 29 Final answer: Balance c/d Final answer: 450 Final answer: 29 Final answer: Discount received Final answer: 3 200 Final answer: 29 Final answer: Contra Final answer: 2 100 Final answer: 29 Final answer: Balance c/d Final answer: 24 450 Final answer:** Final answer: 249 600 Final answer: 249 600 Final answer: Mar 1 Final answer: Balance b/d Final answer: 450 Final answer: Mar 1 Final answer: Balance b/d Final answer: 24 450
Was this revision note helpful?
Build on this topic