Income & Expenditure Account (Cambridge International A-Level Accounting)
Spec point — how to prepare, from full or incomplete accounting records: – an income and expenditure account
Income & expenditure account
What is an income and expenditure account?
-
An income and expenditure account is a statement that calculates the surplus or deficit
-
A surplus is comparable to a profit for a business
-
A deficit is comparable to a loss for a business
- Clubs and societies do not operate to make a profit so the terms profit and loss are not used
-
-
The total expenses are subtracted from the income
- If the income is greater than the expenses then there is a surplus
- If the income is less than the expenses then there is a deficit
-
The income and expenditure account is similar to a statement of profit or loss of a business
- Only expenses and income are included
- Assets and liabilities are not included
-
Adjustments are made for:
- Depreciation of non-current assets
- Accruals and prepayments of expenses and income
- Any subscriptions which are written off
What are the differences between a receipts and payments account and an income and expenditure account?
- The differences are summarised in the table below
| Receipts and payments account | Income and expenditure account |
|---|---|
| Includes only money that is received or paid | Includes only income and expenses |
| Includes only transactions involving money | Includes transactions involving non-monetary items such as depreciation |
| Includes both capital and revenue receipts and expenditure | Includes only revenue receipts and expenditure |
| Does not include adjustments for accruals or prepayments of expenses and income | Includes adjustments for accruals or prepayments of expenses and income |
| The closing balance represents the bank balance or amount of cash | The final amount represents the surplus or deficit |
What is the layout of an income and expenditure account?
-
The account is prepared in a similar way as the profit section of the statement of profit or loss for other types of businesses
-
Deal with any adjustments
-
Accruals
- Subtract accruals from the previous year
- Add accruals at the end of the current year
-
Prepayments
- Add prepayments from the previous year
- Subtract prepayments at the end of the current year
-
Calculate any depreciation charges
-
-
List the income first
-
If there are any costs associated with a source of income then these should be subtracted in this section
- For example, income from a competition should subtract the cost of the competition's prizes
-
Include any profits calculated on the statements of profit or loss for any trading activities
-
-
List the expenditure next
-
Include any losses calculated on the statements of profit or loss for any trading activities
-
Do not include expenses related to specific trading activities
- These will be included in the statements of profit or loss for those activities and will contribute to the profit or loss
-
-
Find the surplus or deficit of the year by subtracting the two totals
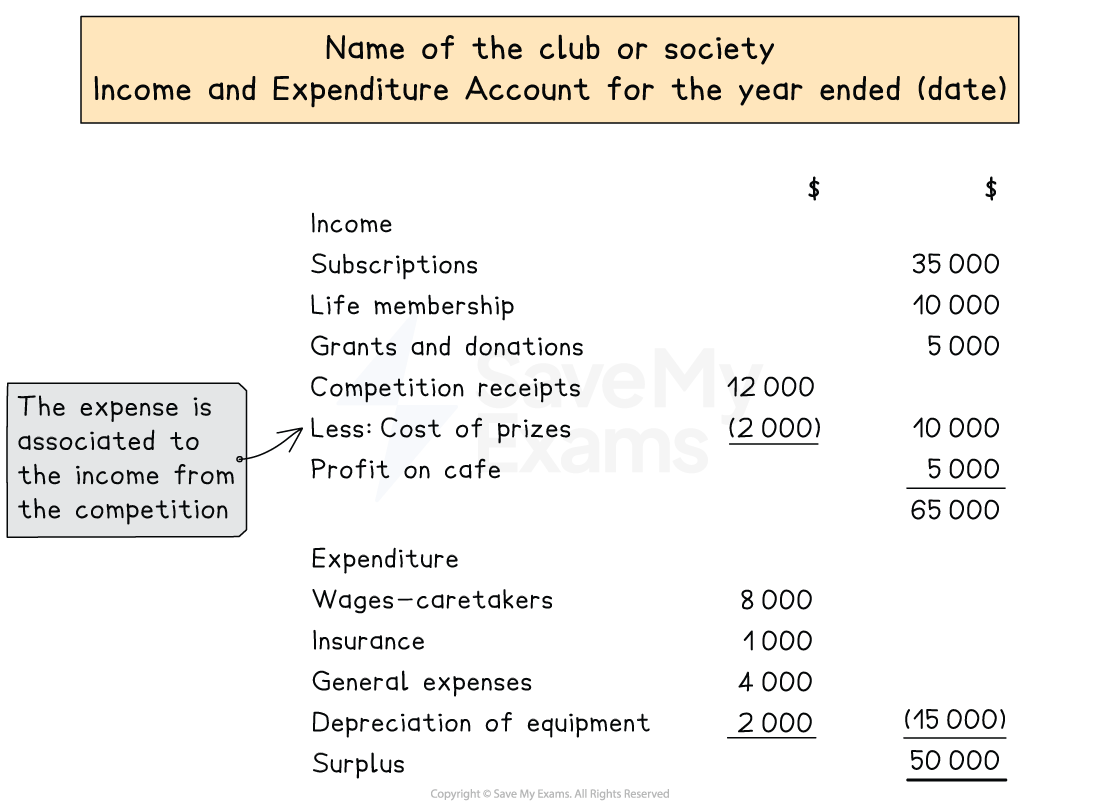
Layout of an income and expenditure account
Exam Hint If the question involves life memberships or donations, read the information carefully to determine how much is released as income for the year.
Worked Example Paramount Badminton Club owns several courts. It also operates a shop where it sells refreshments and badminton equipment. Shop sales are on a cash basis and purchases made for the shop are on credit.
The treasurer of the club provided the following information.
1 January 2023 31 December 2023 $ $ Subscriptions in advance 2 200 2 050 Subscriptions in arrears 6 515 6 850 Other information provided for the year ended 31 December 2023:
Shop profit 9 410 Subscriptions received during the year 36 900 Wages for caretakers 2 650 Insurance 3 640 Bank charges 80 Telephone 380 Advertising 460 Depreciation of equipment 520
- There were a total of 15 life members at 31 December 2023, all of whom joined after 1 January 2021.
- Life members pay $1 200 for lifelong access to the club. Income is released to the income and expenditure account in equal amounts over 10 years.
Prepare the income and expenditure account for Paramount Badminton Club for the year ended 31 December 2023.
Answer:
Calculate the subscriptions for the year by finding the amount that was due for the year
- Add the prepayments from the previous year
- Subtract the accruals from the previous year
- Add accruals at the end of the current year
- Subtract prepayments at the end of the current year
$36 900 + $2 200 - $6 515 + $6 850 - $2 050 = $37 385
Calculate the life membership income
- Divide the membership cost by 10
- Multiply by the number of life members
$1 200 ÷ 10 × 15 = $1 800
Identify the income:
- Subscriptions
- Shop profit
Identify the expenditure:
- Wages
- Insurance
- Bank charges
- Telephone
- Advertising
- Depreciation
Prepare the income and expenditure account using the required format
Final answer: Paramount Badminton Club
Final answer: Income and Expenditure Account for the year ended 31 December 2023Final answer: $** Final answer: **$ Final answer: Subscriptions Final answer: 37 385 Final answer: Life membership Final answer: 1 800 Final answer: Shop profit 9 410 48 595 Final answer: Wages for caretakers 2 650 Final answer: Insurance 3 640 Final answer: Bank charges Final answer: 80 Final answer: Telephone Final answer: 380 Final answer: Advertising Final answer: 460 Final answer: Depreciation of equipment Final answer: 520 Final answer: (7 730) Final answer: Surplus for the year Final answer: 40 865
Was this revision note helpful?