Statement of Profit or Loss (Cambridge International A-Level Accounting)
Statements of profit or loss for manufacturing businesses
Spec point — how to prepare, for a manufacturing business, a statement of profit or loss
What is the layout of the statement of profit or loss of a manufacturing business?
-
The statement of profit or loss for a manufacturing business is prepared in a similar way to the other types of trading businesses
-
The statement of profit or loss is prepared after the manufacturing account
-
For the trading section:
-
Use the inventory for finished goods
-
Use the goods at transfer value in place of purchases
- The business might have also purchased extra finished goods
- Add this in the calculation of the cost of sales
-
-
Make adjustments after the gross profit for the factory profit and the change in the provision for unrealised profit
- Add the factory profit
- If the provision for unrealised profit has increased, then subtract the change
- If the provision for unrealised profit has decreased, then add the change
-
For the profit and loss section:
-
Only include expenses that relate to the non-production aspects of the business
- Such as advertising, carriage outwards, etc
-
The expenses related to manufacturing are included in the cost of production
-
A business might use a factory and an office
- The factory expenses are included in the cost of production
- The office expenses are included in the profit and loss section
-
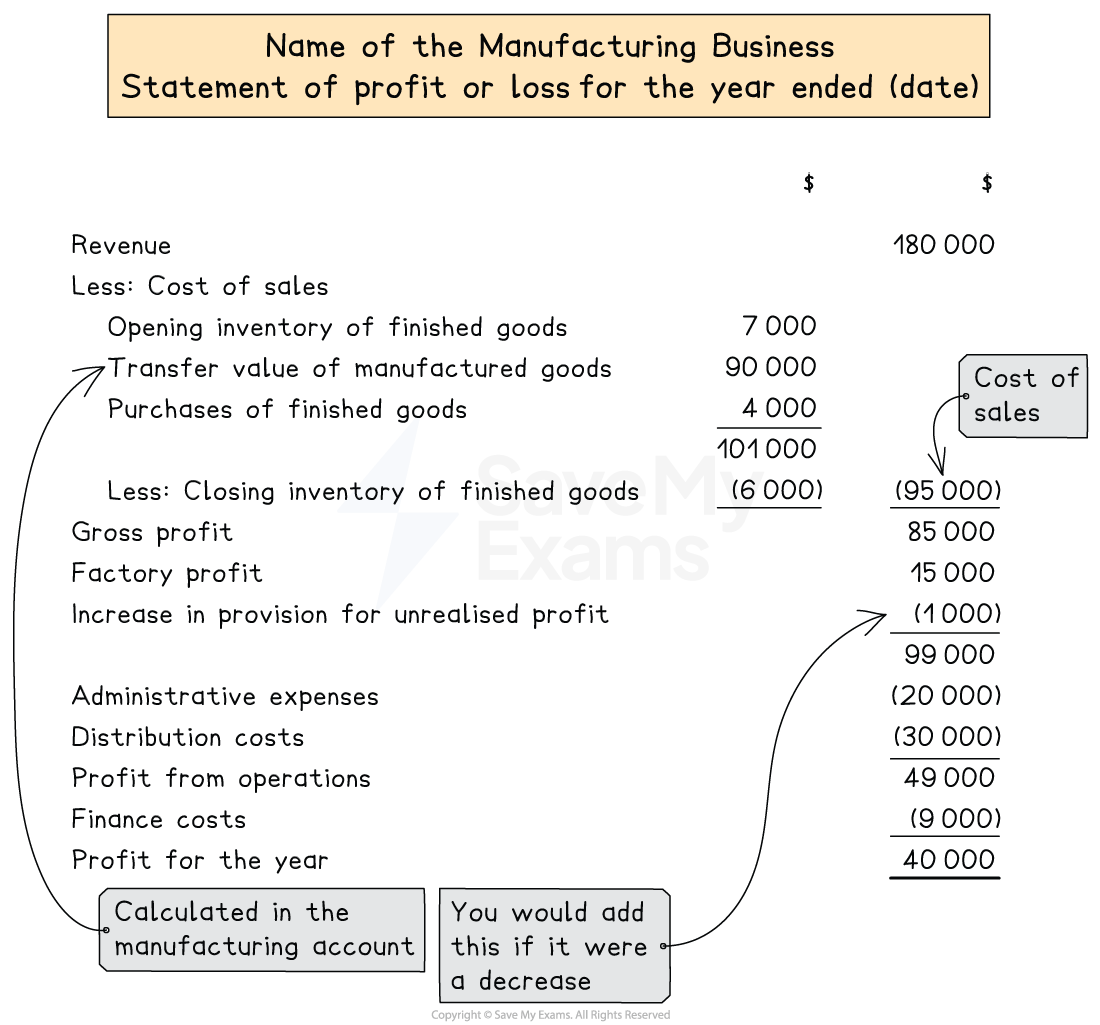
Layout of a statement of profit or loss for a manufacturing business
Worked Example Pablo owns a small carpet and rug factory, making bespoke carpets for local furniture businesses. He applies a rate of factory profit of 20%.
The following balances are provided at 31 December 2023.
$ Revenue 280 050 Inventory at 1 January 2023 Raw materials 7 100 Work in progress 10 420 Finished goods 12 450 Purchases of raw materials 96 200 Wages of factory workers 38 000 Wages of factory supervisors 28 500 Wages of office and sales staff 48 000 Insurance and rates 15 000 General factory expenses 13 180 General office expenses 25 750 Factory equipment at cost 120 000 Provision for depreciation of factory equipment at 1 January 2023 40 000 Provision for unrealised profit at 1 January 2023 2 075 Additional Information
Inventory at 31 December 2023
- Raw materials $6 860
- Work in progress $10 885
- Finished goods $14 640
Insurance and rates are to be apportioned ⅓ to the office and ⅔ to the factory
Factory equipment is to be depreciated at 15% using the reducing balance method
(a) Prepare the manufacturing account for the year ended 31 December 2023.
(b) Prepare the statement of profit or loss for the year ended 31 December 2023.
Answer:
Deal with the additional information
Inventory at 31 December 2023
- These appear as current assets on the statement of financial position
- The raw materials and work in progress appear on the manufacturing account
- The finished goods appear on the statement of profit or loss
Insurance and rates are to be apportioned ⅓ to the office and ⅔ to the factory
Find the amount for the office
- ⅓ × $15 000 = $5 000
- This appears in the profit and loss section of the statement of profit or loss
Find the amount for the factory
- ⅔ × $15 000 = $10 000
- This appears on the manufacturing account as a factory overhead
Factory equipment is to be depreciated at 15% using the reducing balance method
Find the net book value of the factory equipment
- $120 000 - $40 000 = $80 000
Calculate the year's depreciation charge
- 15% × $80 000 = $12 000
- This appears on the manufacturing account as a factory overhead
Multiply the cost of production by 20% to find the factory profit
$197 655 × 20% = $39 531
(a)
Prepare the manufacturing account
Final answer: Pablo
Final answer: Manufacturing Account for the year ended 31 December 2023Final answer: $** Final answer: $ Final answer: Cost of material consumed Final answer: Opening inventory of raw materials Final answer: 7 100 Final answer: Purchases of raw materials Final answer: 96 200 Final answer: 103 300 Final answer:** Less: Closing inventory of raw materials ** Final answer: (6 860) Final answer: 96 440 Final answer: Direct wages - factory workers Final answer: 38 000 Final answer:** Prime cost ** Final answer: 134 440 Final answer: Factory overheads Final answer: Wages - Supervisors Final answer: 28 500 Final answer: Insurance and rates Final answer: 10 000 Final answer: General expenses Final answer: 13 180 Final answer: Depreciation of factory equipment Final answer: 12 000 Final answer: 63 680 Final answer: 198 120 Final answer:** Add: Opening work in progress ** Final answer: 10 420 Final answer: 208 540 Final answer: Less: Closing work in progress Final answer: (10 885) Final answer: Cost of production Final answer: 197 655 Final answer: Factory profit Final answer: 39 531 Final answer: Transfer value Final answer: 237 186 **(b)
- Calculate the balance of the provision for unrealised profit account
20 / 120×$ 14 640=$ 2 440
- Calculate the increase in the provision
$2 440 - $2 075 = $365
Prepare the trading section of the statement of profit or loss
Final answer: Pablo
Final answer: Statement of Profit or Loss (trading section) for the year ended 31 December 2023Final answer: $** Final answer: **$ Final answer: Revenue Final answer: 280 050 Final answer: Less: Cost of sales Final answer: Opening inventory of finished goods Final answer: 12 450 Final answer: Goods at transfer value Final answer: 237 186 Final answer: 249 636 Final answer: Less: Closing inventory of finished goods Final answer: (14 640) Final answer: (234 996) Final answer: Gross Profit Final answer: 45 054 Final answer: Factory profit Final answer: 39 531 Final answer: Increase in provision for unrealised profit Final answer: (365) Final answer: 84 220 Final answer: Insurance and rates Final answer: 5 000 Final answer: Wages of office and sales staff Final answer: 48 000 Final answer: General office expenses Final answer: 25 750 Final answer: (78 750) Final answer: Profit for the year Final answer: 5 470
Was this revision note helpful?